7 Post-Closing Realities That Hit Clients Harder Than the Down Payment
The average Greater Victoria homebuyer closes with roughly $3,200 in liquid savings remaining after the Property Transfer Tax, lawyer fees, and moving costs clear. That's seven weeks of mortgage payments and utilities, no buffer.
1. The first two months feel like the longest stretch of financial holding-your-breath you've ever done.
Property Transfer Tax alone hits at 1% on the first $200,000 and 2% up to $2 million in BC. A $750,000 purchase in Victoria means $13,000 in PTT unless you qualify for the first-time buyer exemption. Closing costs stack another $5,000 to $8,000 on top: legal fees, title insurance, home inspection arrears adjustments, moving trucks. Most buyers budget for these. What they don't budget for is the liquidity void that follows. You've drained the account to get in. Now every unexpected cost, a broken dishwasher, a plumbing call, the deposit on BC Hydro, feels amplified because there's no cushion left.
2. Set up CRD water and BC Hydro accounts 10 days before possession, not the day you move in.
Failing to transfer utilities ahead of time in Victoria often triggers connection fees or service gaps during the first 48 hours. The Capital Regional District water/sewer billing runs independently from municipal property tax in many areas, and new owners frequently discover a $150 reconnection charge because they assumed everything transferred automatically at closing. It doesn't. BC Hydro requires a separate account setup with a security deposit if you don't have an existing payment history with them. That deposit can run $200 to $400. Handle it early or you're unpacking boxes by flashlight.
3. Your first mortgage payment isn't due for six weeks, which creates a false budget surplus that leads to overspending on furniture.
Mortgage interest is paid in arrears in Canada. You close on August 15, your first payment isn't due until October 1. That gap feels like free money. It isn't. Buyers routinely blow $4,000 to $6,000 on furniture, paint, and minor renovations during this window because the mortgage "hasn't started yet." It has. You're accruing interest daily from the day you closed. The payment structure just lags. Treat the first 60 days as a spending fast, not a decorating spree.
4. If you used the Home Buyer's Plan to pull RRSP funds for your down payment, the repayment clock starts ticking after a two-year grace period.
The HBP lets you withdraw up to $60,000 from your RRSP tax-free for a down payment, but you must repay it over 15 years starting in the second year after withdrawal. Most people forget this entirely until CRA sends the first reminder. If you pulled $40,000 in 2024, your first mandatory repayment of roughly $2,667 is due by March 2027. Miss it and that amount gets added to your taxable income for the year. It's not optional. Factor it into your cash flow now.
5. The thing that breaks in month two wasn't covered in the home inspection because inspections are point-in-time visual assessments, not warranties.
Clients feel betrayed when the hot water tank fails six weeks after possession. The inspector didn't catch it because the tank was functioning the day of the inspection. Inspections assess condition and flag visible defects; they don't predict lifespan. A 12-year-old furnace that's running fine during the walkthrough can die three weeks later and that's not negligence, it's statistics. Set aside 1% to 3% of the home's value annually for maintenance. On a $700,000 home, that's $7,000 to $21,000. If you spent everything on the down payment, you don't have it.
6. Buyers in Greater Victoria who intended to rent out a secondary suite often discover municipal compliance requirements they didn't anticipate.
Legal suite rental in many Victoria-area municipalities requires specific egress windows, separate electrical panels, and permits that weren't part of the purchase conversation. A suite that "has always been rented out" doesn't mean it's legally compliant. The previous owner may have been operating in a gray area. New owners face a choice: spend $8,000 to $15,000 on compliance upgrades, or forgo the rental income they were counting on to cover part of the mortgage. That income assumption collapses in week three when the municipal planner sends the letter.
7. The psychological crash happens around day 45, right when the adrenaline of the purchase wears off and the bills start arriving.
Research on buyer satisfaction shows a dip roughly 30 to 60 days post-purchase. The hunt was exciting. The offer was stressful but quick. Closing was a relief. Then you're standing in a half-unpacked house with a leaking bathroom fixture, a strata fee you didn't mentally account for, and a property tax bill that just hit your email. This is normal. It doesn't mean you made the wrong choice. It means you're transitioning from Buyer to Owner, and that shift is harder than anyone mentions during the transaction.
The mortgage conversation shouldn't end at funding. The first 60 days are when clients need the map most.

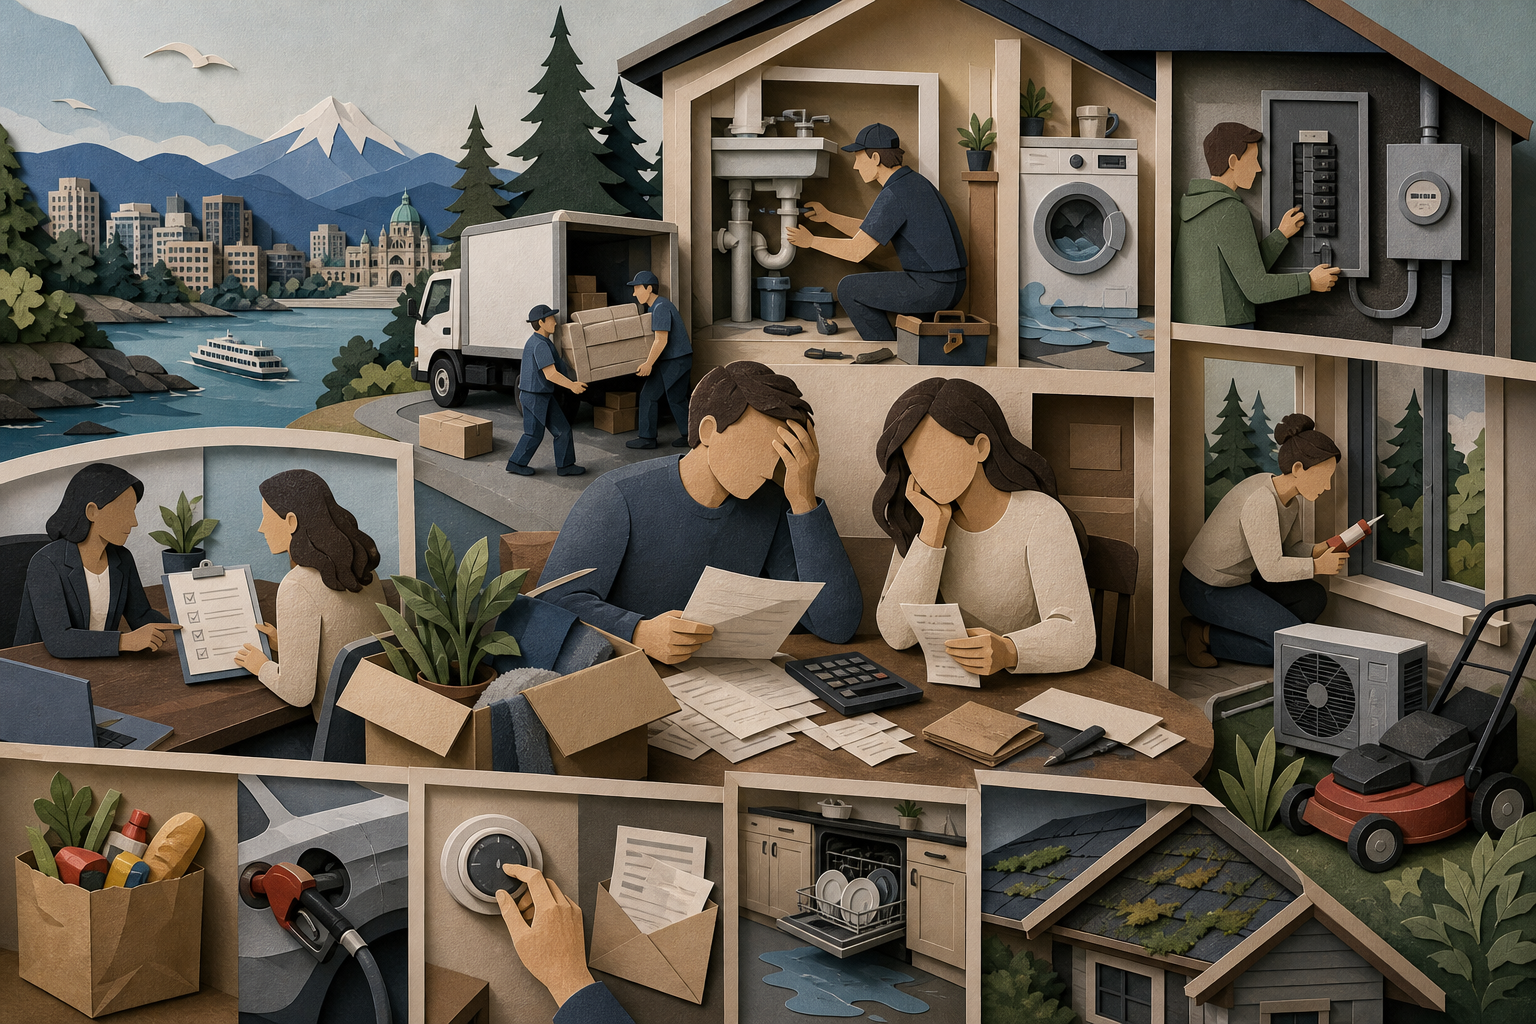

The average Greater Victoria homebuyer closes with roughly $3,200 in liquid savings remaining after the Property Transfer Tax, lawyer fees, and moving costs clear. That's seven weeks of mortgage payments and utilities, no buffer.
1. The first two months feel like the longest stretch of financial holding-your-breath you've ever done.
Property Transfer Tax alone hits at 1% on the first $200,000 and 2% up to $2 million in BC. A $750,000 purchase in Victoria means $13,000 in PTT unless you qualify for the first-time buyer exemption. Closing costs stack another $5,000 to $8,000 on top: legal fees, title insurance, home inspection arrears adjustments, moving trucks. Most buyers budget for these. What they don't budget for is the liquidity void that follows. You've drained the account to get in. Now every unexpected cost, a broken dishwasher, a plumbing call, the deposit on BC Hydro, feels amplified because there's no cushion left.
2. Set up CRD water and BC Hydro accounts 10 days before possession, not the day you move in.
Failing to transfer utilities ahead of time in Victoria often triggers connection fees or service gaps during the first 48 hours. The Capital Regional District water/sewer billing runs independently from municipal property tax in many areas, and new owners frequently discover a $150 reconnection charge because they assumed everything transferred automatically at closing. It doesn't. BC Hydro requires a separate account setup with a security deposit if you don't have an existing payment history with them. That deposit can run $200 to $400. Handle it early or you're unpacking boxes by flashlight.
3. Your first mortgage payment isn't due for six weeks, which creates a false budget surplus that leads to overspending on furniture.
Mortgage interest is paid in arrears in Canada. You close on August 15, your first payment isn't due until October 1. That gap feels like free money. It isn't. Buyers routinely blow $4,000 to $6,000 on furniture, paint, and minor renovations during this window because the mortgage "hasn't started yet." It has. You're accruing interest daily from the day you closed. The payment structure just lags. Treat the first 60 days as a spending fast, not a decorating spree.
4. If you used the Home Buyer's Plan to pull RRSP funds for your down payment, the repayment clock starts ticking after a two-year grace period.
The HBP lets you withdraw up to $60,000 from your RRSP tax-free for a down payment, but you must repay it over 15 years starting in the second year after withdrawal. Most people forget this entirely until CRA sends the first reminder. If you pulled $40,000 in 2024, your first mandatory repayment of roughly $2,667 is due by March 2027. Miss it and that amount gets added to your taxable income for the year. It's not optional. Factor it into your cash flow now.
5. The thing that breaks in month two wasn't covered in the home inspection because inspections are point-in-time visual assessments, not warranties.
Clients feel betrayed when the hot water tank fails six weeks after possession. The inspector didn't catch it because the tank was functioning the day of the inspection. Inspections assess condition and flag visible defects; they don't predict lifespan. A 12-year-old furnace that's running fine during the walkthrough can die three weeks later and that's not negligence, it's statistics. Set aside 1% to 3% of the home's value annually for maintenance. On a $700,000 home, that's $7,000 to $21,000. If you spent everything on the down payment, you don't have it.
6. Buyers in Greater Victoria who intended to rent out a secondary suite often discover municipal compliance requirements they didn't anticipate.
Legal suite rental in many Victoria-area municipalities requires specific egress windows, separate electrical panels, and permits that weren't part of the purchase conversation. A suite that "has always been rented out" doesn't mean it's legally compliant. The previous owner may have been operating in a gray area. New owners face a choice: spend $8,000 to $15,000 on compliance upgrades, or forgo the rental income they were counting on to cover part of the mortgage. That income assumption collapses in week three when the municipal planner sends the letter.
7. The psychological crash happens around day 45, right when the adrenaline of the purchase wears off and the bills start arriving.
Research on buyer satisfaction shows a dip roughly 30 to 60 days post-purchase. The hunt was exciting. The offer was stressful but quick. Closing was a relief. Then you're standing in a half-unpacked house with a leaking bathroom fixture, a strata fee you didn't mentally account for, and a property tax bill that just hit your email. This is normal. It doesn't mean you made the wrong choice. It means you're transitioning from Buyer to Owner, and that shift is harder than anyone mentions during the transaction.
The mortgage conversation shouldn't end at funding. The first 60 days are when clients need the map most.
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure