Altmore MIC Operator Pleads Guilty: What 30 Ontario Investors Missed Before Losing $5.3 Million
Altmore MIC Operator Pleads Guilty: What 30 Ontario Investors Missed Before Losing $5.3 Million
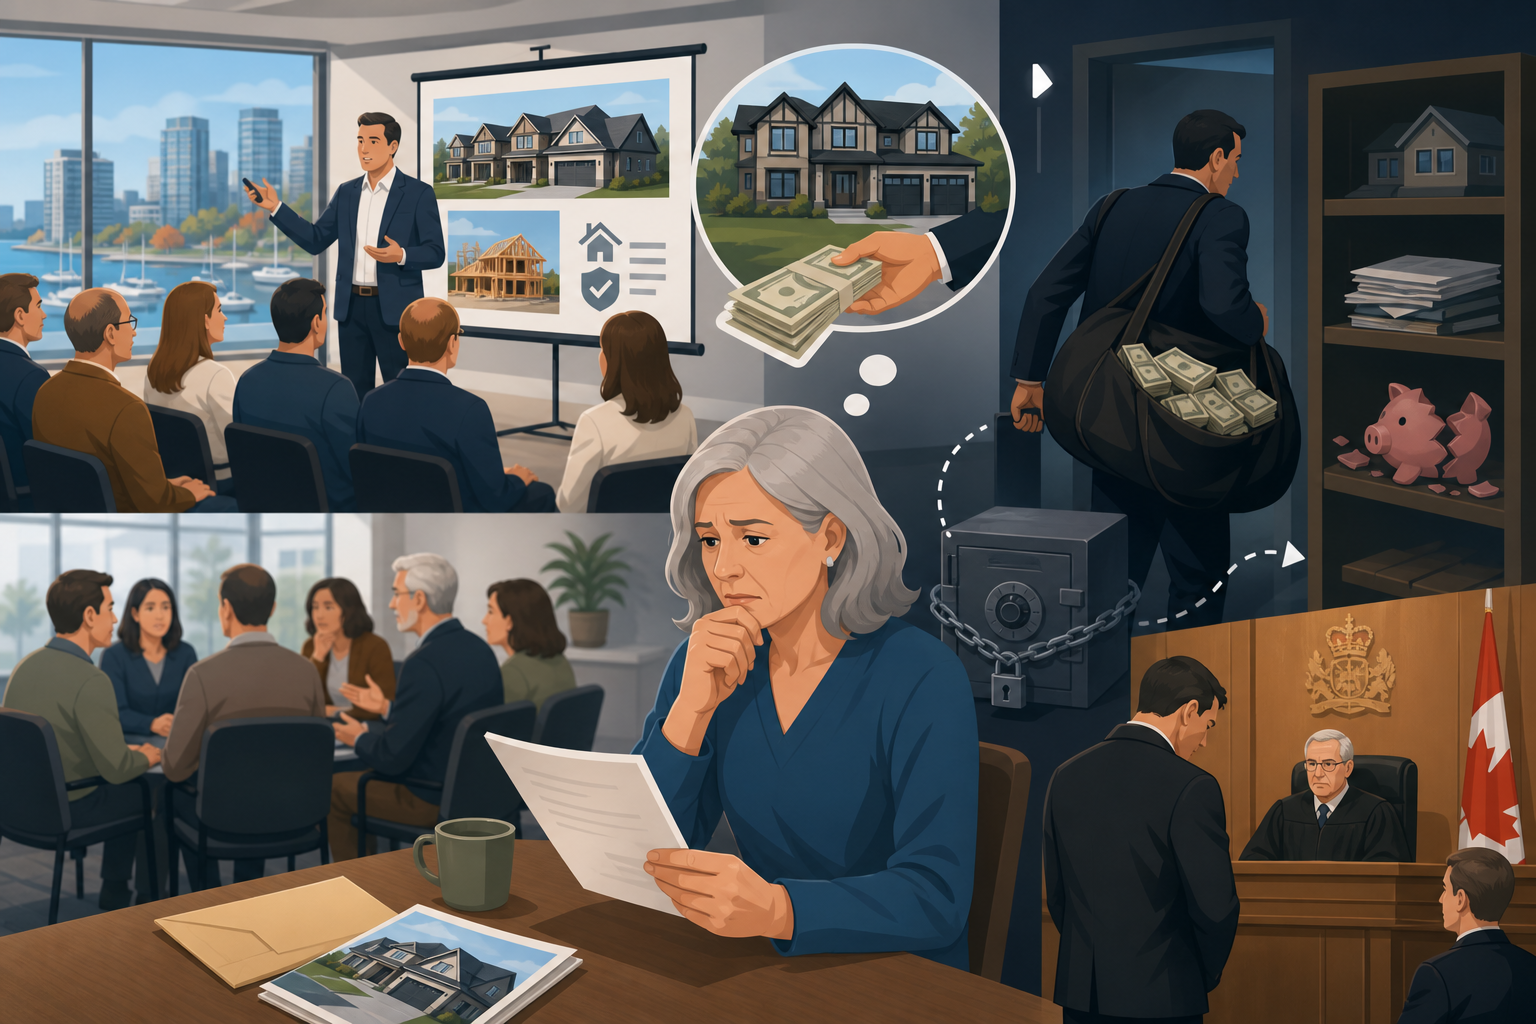
Karen was 62 when she met the Altmore representative at a financial seminar in Oakville in 2019. She had $180,000 in a GIC paying 2.4%. The Altmore pitch was straightforward: pool her money with other investors to fund private mortgages secured by Ontario real estate, earn 7.5% annually, paid monthly. The representative showed her a slide deck with photos of subdivision homes, a table of historical returns, and language about "conservative loan-to-value ratios." She asked about security. He pointed to the word "mortgage" in the name. That felt like enough.
By 2026, that $180,000 was gone. The Ontario Securities Commission announced that Altmore's operator had pleaded guilty after an investigation revealed the funds were never deployed as described. Karen was one of roughly 30 investors. Combined, they lost $5.3 million.
The mortgage label did most of the work
Mortgage Investment Corporations occupy a specific niche in Canadian finance. They allow smaller investors to participate in pools of private mortgages, the kind that fund construction projects, bridge financing, or borrowers who don't qualify at the big banks. The structure is attractive because it's flow-through for tax purposes, income passes directly to investors, and because the term "mortgage" implies a lien on property. That implication is where the vulnerability sits.
A mortgage is only as secure as the registration process behind it. If the funds never reach a lawyer's trust account, if no mortgage gets registered on title, if the borrower doesn't exist or the property is encumbered beyond its value, the word "mortgage" on the marketing material is decorative. The Altmore case turned on that gap. Investors believed their capital was secured by real estate because that's what the corporate structure was designed to suggest. The OSC investigation showed the money went elsewhere.
Thirty investors is a pattern, not an anomaly
The number of victims is worth noting. Thirty people is not a crowd. It's a neighbourhood seminar, a referral chain, a small network event. That scale tells you something about how these schemes work. They don't need mass advertising. They need a few early participants who speak well of the returns, a professional-looking pitch deck, and the kind of credibility that comes from operating under a regulated label like "Mortgage Investment Corporation."
The OSC regulates capital-raising by MICs under securities law. The Financial Services Regulatory Authority of Ontario oversees mortgage brokering. That dual framework creates a seam. An operator who files the right forms in one jurisdiction and keeps a low profile in the other can operate for years before red flags accumulate. By the time enforcement catches up, the money is spent or hidden.
The yield chase made bad diligence feel reasonable
Between 2018 and 2022, GIC rates in Canada sat below 3% for most terms. Bond yields were similarly compressed. Retirees and near-retirees with fixed-income portfolios faced a choice: accept returns that didn't keep pace with inflation, or hunt for yield in less-regulated corners of the market. Private mortgages offered a middle path, real estate backing, monthly income, a rate in the 6-8% range. The risk looked manageable because the underlying asset was housing, and Canadian housing had been a one-way bet for two decades.
The problem is that "backed by real estate" only works if the backing is real. Karen never asked to see a registered mortgage. She didn't request audited financials or ask how Altmore's loan-to-value ratios were calculated. Those questions felt unnecessary because the structure itself seemed to answer them.
Recovery rarely follows enforcement
A guilty plea is a win for the OSC in terms of deterrence and accountability. It almost never results in full recovery for the victims. By the time enforcement proceedings reach a courtroom, the funds are typically gone, spent on operating expenses, diverted to personal accounts, or tied up in legal defenses. Karen got a letter explaining the conviction. She did not get her principal back.
She still attends financial seminars. She asks more questions now.


Altmore MIC Operator Pleads Guilty: What 30 Ontario Investors Missed Before Losing $5.3 Million
Karen was 62 when she met the Altmore representative at a financial seminar in Oakville in 2019. She had $180,000 in a GIC paying 2.4%. The Altmore pitch was straightforward: pool her money with other investors to fund private mortgages secured by Ontario real estate, earn 7.5% annually, paid monthly. The representative showed her a slide deck with photos of subdivision homes, a table of historical returns, and language about "conservative loan-to-value ratios." She asked about security. He pointed to the word "mortgage" in the name. That felt like enough.
By 2026, that $180,000 was gone. The Ontario Securities Commission announced that Altmore's operator had pleaded guilty after an investigation revealed the funds were never deployed as described. Karen was one of roughly 30 investors. Combined, they lost $5.3 million.
The mortgage label did most of the work
Mortgage Investment Corporations occupy a specific niche in Canadian finance. They allow smaller investors to participate in pools of private mortgages, the kind that fund construction projects, bridge financing, or borrowers who don't qualify at the big banks. The structure is attractive because it's flow-through for tax purposes, income passes directly to investors, and because the term "mortgage" implies a lien on property. That implication is where the vulnerability sits.
A mortgage is only as secure as the registration process behind it. If the funds never reach a lawyer's trust account, if no mortgage gets registered on title, if the borrower doesn't exist or the property is encumbered beyond its value, the word "mortgage" on the marketing material is decorative. The Altmore case turned on that gap. Investors believed their capital was secured by real estate because that's what the corporate structure was designed to suggest. The OSC investigation showed the money went elsewhere.
Thirty investors is a pattern, not an anomaly
The number of victims is worth noting. Thirty people is not a crowd. It's a neighbourhood seminar, a referral chain, a small network event. That scale tells you something about how these schemes work. They don't need mass advertising. They need a few early participants who speak well of the returns, a professional-looking pitch deck, and the kind of credibility that comes from operating under a regulated label like "Mortgage Investment Corporation."
The OSC regulates capital-raising by MICs under securities law. The Financial Services Regulatory Authority of Ontario oversees mortgage brokering. That dual framework creates a seam. An operator who files the right forms in one jurisdiction and keeps a low profile in the other can operate for years before red flags accumulate. By the time enforcement catches up, the money is spent or hidden.
The yield chase made bad diligence feel reasonable
Between 2018 and 2022, GIC rates in Canada sat below 3% for most terms. Bond yields were similarly compressed. Retirees and near-retirees with fixed-income portfolios faced a choice: accept returns that didn't keep pace with inflation, or hunt for yield in less-regulated corners of the market. Private mortgages offered a middle path, real estate backing, monthly income, a rate in the 6-8% range. The risk looked manageable because the underlying asset was housing, and Canadian housing had been a one-way bet for two decades.
The problem is that "backed by real estate" only works if the backing is real. Karen never asked to see a registered mortgage. She didn't request audited financials or ask how Altmore's loan-to-value ratios were calculated. Those questions felt unnecessary because the structure itself seemed to answer them.
Recovery rarely follows enforcement
A guilty plea is a win for the OSC in terms of deterrence and accountability. It almost never results in full recovery for the victims. By the time enforcement proceedings reach a courtroom, the funds are typically gone, spent on operating expenses, diverted to personal accounts, or tied up in legal defenses. Karen got a letter explaining the conviction. She did not get her principal back.
She still attends financial seminars. She asks more questions now.
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure