Canada's $1.7 Trillion Housing Fix Would Hijack Capital Markets for a Decade
Doubling Canada's residential construction rate over ten years sounds like a plan. It's also a capital reallocation so large that every other borrower in the economy will feel it.
The arithmetic comes from CMHC's 3.5 million unit supply gap, the distance between current housing stock and what's needed to restore 2004-level affordability. Building that many homes while maintaining baseline replacement construction requires approximately $1.7 trillion in new investment by 2030, according to recent economic projections. That figure isn't speculative. It's what happens when you price out land acquisition, materials, labour, permits, and carrying costs at the current run rate and scale it to the target volume.
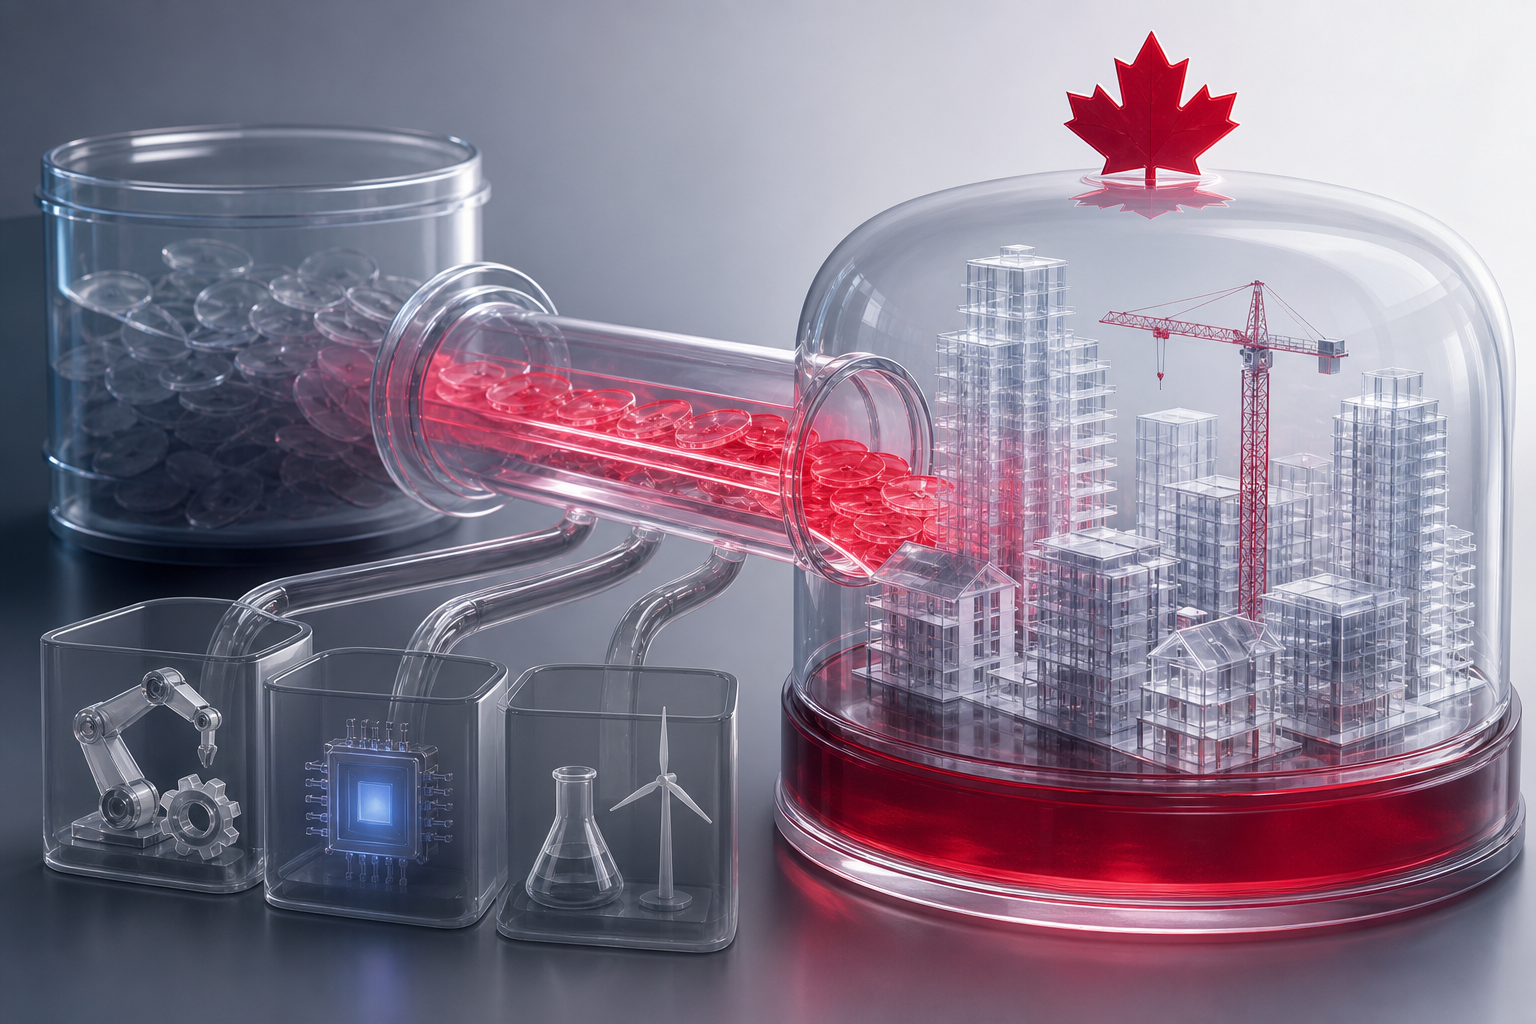
The problem isn't whether Canada can find $1.7 trillion. The problem is what happens to everyone else when housing becomes the dominant bid in the capital markets.
The Interest Rate Feedback Loop
Construction finance doesn't run on equity. It runs on debt. Developers borrow against land, borrow to build, and repay once units sell or stabilize as rentals. Doubling the sector's activity means doubling its claim on the pool of long-term credit that pension funds, insurers, and bond buyers currently spread across infrastructure, corporate expansion, and government deficit financing.
When one borrower suddenly demands twice as much of a fixed resource, the price of that resource rises. In this case, the resource is capital, and the price is the interest rate. The construction boom required to hit affordability targets would put sustained upward pressure on long-term rates, potentially keeping the five-year fixed mortgage in the 5-7% range even if the Bank of Canada cuts the overnight rate. The sector's own financing needs would make the homes it's trying to build more expensive to buy.
That's not a theoretical concern. The 2021-2022 condo construction wave in Toronto saw developers competing so aggressively for construction loans that lenders began requiring 30% equity instead of the traditional 20%, effectively pricing smaller builders out of the market. Scale that dynamic across the entire national housing stock for a decade.
Crowding Out the Productive Economy
Capital diverted to residential construction is capital not going somewhere else. The green energy transition requires an estimated $2 trillion in infrastructure investment by 2050. Aging water and transit systems need roughly $1 trillion over the same period, according to municipal infrastructure reports. A $1.7 trillion housing push doesn't happen alongside these priorities, it competes with them for the same financing.
The question isn't whether housing is more important than grid modernization or port expansions. The question is whether Canada's capital markets can supply both simultaneously without starving one to feed the other. Manufacturing productivity in Canada has lagged the US for two decades partly because firms here face higher capital costs and tighter credit. Adding a housing construction arms race to that environment makes the productivity gap worse.
The Capacity Wall Nobody Mentions
Even if the $1.7 trillion materializes tomorrow, the physical capacity to deploy it doesn't exist. Canada's construction workforce is aging out, retirements are projected to accelerate through 2028 , and training replacements takes years, not months. You can't double crane capacity, concrete production, and skilled trades with a policy announcement.
The only way to hit these targets with a constrained labour pool is an industrial-scale pivot to modular and prefabricated housing, which currently represents less than 3% of Canadian residential construction. That shift requires factory buildout, supply chain restructuring, and regulatory changes to allow factory-built units in zoning codes written for stick-frame homes. None of that happens fast.
The housing crisis is real. The $1.7 trillion figure is defensible. What's missing from the conversation is the acknowledgment that fixing affordability at this scale isn't a housing policy question. It's a decade-long economic reorientation that subordinates nearly every other capital allocation decision to one goal.
That may be the right choice. But pretending it's cost-free is dishonest.


Doubling Canada's residential construction rate over ten years sounds like a plan. It's also a capital reallocation so large that every other borrower in the economy will feel it.
The arithmetic comes from CMHC's 3.5 million unit supply gap, the distance between current housing stock and what's needed to restore 2004-level affordability. Building that many homes while maintaining baseline replacement construction requires approximately $1.7 trillion in new investment by 2030, according to recent economic projections. That figure isn't speculative. It's what happens when you price out land acquisition, materials, labour, permits, and carrying costs at the current run rate and scale it to the target volume.
The problem isn't whether Canada can find $1.7 trillion. The problem is what happens to everyone else when housing becomes the dominant bid in the capital markets.
The Interest Rate Feedback Loop
Construction finance doesn't run on equity. It runs on debt. Developers borrow against land, borrow to build, and repay once units sell or stabilize as rentals. Doubling the sector's activity means doubling its claim on the pool of long-term credit that pension funds, insurers, and bond buyers currently spread across infrastructure, corporate expansion, and government deficit financing.
When one borrower suddenly demands twice as much of a fixed resource, the price of that resource rises. In this case, the resource is capital, and the price is the interest rate. The construction boom required to hit affordability targets would put sustained upward pressure on long-term rates, potentially keeping the five-year fixed mortgage in the 5-7% range even if the Bank of Canada cuts the overnight rate. The sector's own financing needs would make the homes it's trying to build more expensive to buy.
That's not a theoretical concern. The 2021-2022 condo construction wave in Toronto saw developers competing so aggressively for construction loans that lenders began requiring 30% equity instead of the traditional 20%, effectively pricing smaller builders out of the market. Scale that dynamic across the entire national housing stock for a decade.
Crowding Out the Productive Economy
Capital diverted to residential construction is capital not going somewhere else. The green energy transition requires an estimated $2 trillion in infrastructure investment by 2050. Aging water and transit systems need roughly $1 trillion over the same period, according to municipal infrastructure reports. A $1.7 trillion housing push doesn't happen alongside these priorities, it competes with them for the same financing.
The question isn't whether housing is more important than grid modernization or port expansions. The question is whether Canada's capital markets can supply both simultaneously without starving one to feed the other. Manufacturing productivity in Canada has lagged the US for two decades partly because firms here face higher capital costs and tighter credit. Adding a housing construction arms race to that environment makes the productivity gap worse.
The Capacity Wall Nobody Mentions
Even if the $1.7 trillion materializes tomorrow, the physical capacity to deploy it doesn't exist. Canada's construction workforce is aging out, retirements are projected to accelerate through 2028 , and training replacements takes years, not months. You can't double crane capacity, concrete production, and skilled trades with a policy announcement.
The only way to hit these targets with a constrained labour pool is an industrial-scale pivot to modular and prefabricated housing, which currently represents less than 3% of Canadian residential construction. That shift requires factory buildout, supply chain restructuring, and regulatory changes to allow factory-built units in zoning codes written for stick-frame homes. None of that happens fast.
The housing crisis is real. The $1.7 trillion figure is defensible. What's missing from the conversation is the acknowledgment that fixing affordability at this scale isn't a housing policy question. It's a decade-long economic reorientation that subordinates nearly every other capital allocation decision to one goal.
That may be the right choice. But pretending it's cost-free is dishonest.
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure