Canada's Labour Blowout Just Killed Trump's Tariff Leverage
Canada added 75,000 jobs in July while the U.S. shed 23,000 and watched workers abandon the labour force entirely. The unemployment gap between the two countries now sits at the widest spread since early 2022, and the timing could not be worse for an administration that spent the last six months threatening tariffs to extract concessions from a supposedly fragile northern neighbour.
The leverage calculus was simple: crack Canada's job market, force Ottawa to the table, win CUSMA renegotiation points before the 2028 election cycle. But when the target economy is adding 60,000 jobs a month on a three-month average and dragging unemployment to a two-year low of 6.4%, the threat loses most of its bite.
The Split-Screen Labour Market
July's employment reports couldn't have painted a sharper contrast. Canada's 75,000-job gain crushed consensus forecasts near 20,000. The labour force expanded by 60,500 despite depopulation trends. Full-time employment among workers 25 and older, the cohort that drives mortgage demand, rose 33,000. Hours worked climbed 0.6%, enough for BMO's Doug Porter to estimate nearly 4% annualized GDP growth in Q3.
South of the border, nonfarm payrolls contracted by 23,000 against forecasts of +85,000. May and June were revised down by a combined 103,000. Unemployment fell to 4.1%, but only because labour force participation dropped to 61.4%, outside the pandemic, the lowest reading since the 1970s. CIBC called it a head scratcher: fewer jobs, fewer workers, falling headline rate. David Rosenberg was less charitable, pointing to three straight anaemic months and a three-month average he described as microscopic at 20,000.
The unemployment rate dropped for all the wrong reasons. People stopped looking.
What Gets Complicated for Tariff Leverage
Trump's August 19 tariff threat was designed to land on a weakened Canadian economy that would flinch at the prospect of trade restrictions. The actual economy he's facing is running too hot for the Bank of Canada's comfort and generating job growth that looks suspiciously durable.
Wage growth did cool to 2.8% year-over-year, the slowest in four years, which keeps inflationary pressure off the central bank's radar. That's the sweet spot: strong hiring, no pay spiral. The combination historically keeps central banks on hold, not scrambling to ease into a downturn.
Governing Council can point to that 2.8% wage figure every time someone asks why it isn't tightening into potentially 4% Q3 GDP. And with tariffs sitting directly in the policy path, no one in Ottawa will be eager to hike rates preemptively. Consensus has the Bank on hold through year-end, with markets fully pricing a 25-basis-point hike for January 2027.
The leverage problem is structural. Tariffs work as economic coercion when the target is already fragile and the threat credible. Canada's labour market just made the threat less credible.
Where This Leaves Fixed and Variable Borrowers
Canadian data argues for higher five-year government bond yields. Falling U.S. Treasury yields pull the other way. The two markets rarely move in opposite directions for long, but when they do, it creates a tug-of-war that makes forward pricing unreliable.
Setting client expectations for cheaper fixed pricing over the next few quarters is probably unwise. Any rate improvement is more likely to come from an unexpected crisis, including tariff fallout, than from a general disinflation-driven bond rally.
The variable pitch just lost its best argument. "Take variable, cuts are coming" doesn't survive 6.4% unemployment and 4% growth. Variable now has to win on upfront discount, hopes for a short hike cycle, prepayment flexibility, and disaster optionality. That's a harder sell.
Risk-averse borrowers with terms maturing in six to nine months should consider early renewal or a low-cost blend if the math justifies it. Waiting for rescue from a weakening economy that isn't weakening is a bet against the data.
The August 19 Wild Card
If Trump's tariffs land hard next week, Canada's hiring strength gets tested immediately and the entire rate conversation potentially reverses. That's the scenario where variable might pay as a hedge, though it's not a forecast.
Both Prime Minister Carney and President Trump have characterized the negotiations as "nasty" in recent days. Inflationary retaliation is on the table if the tariffs arrive as threatened. Prediction market Kalshi puts the odds of those 50% tariffs arriving on schedule at just 3 in 10, so the market thinks August 19 is far more likely to be an ordinary Wednesday than a crisis.
The tariff threat was designed to exploit weakness. The weakness didn't show up.

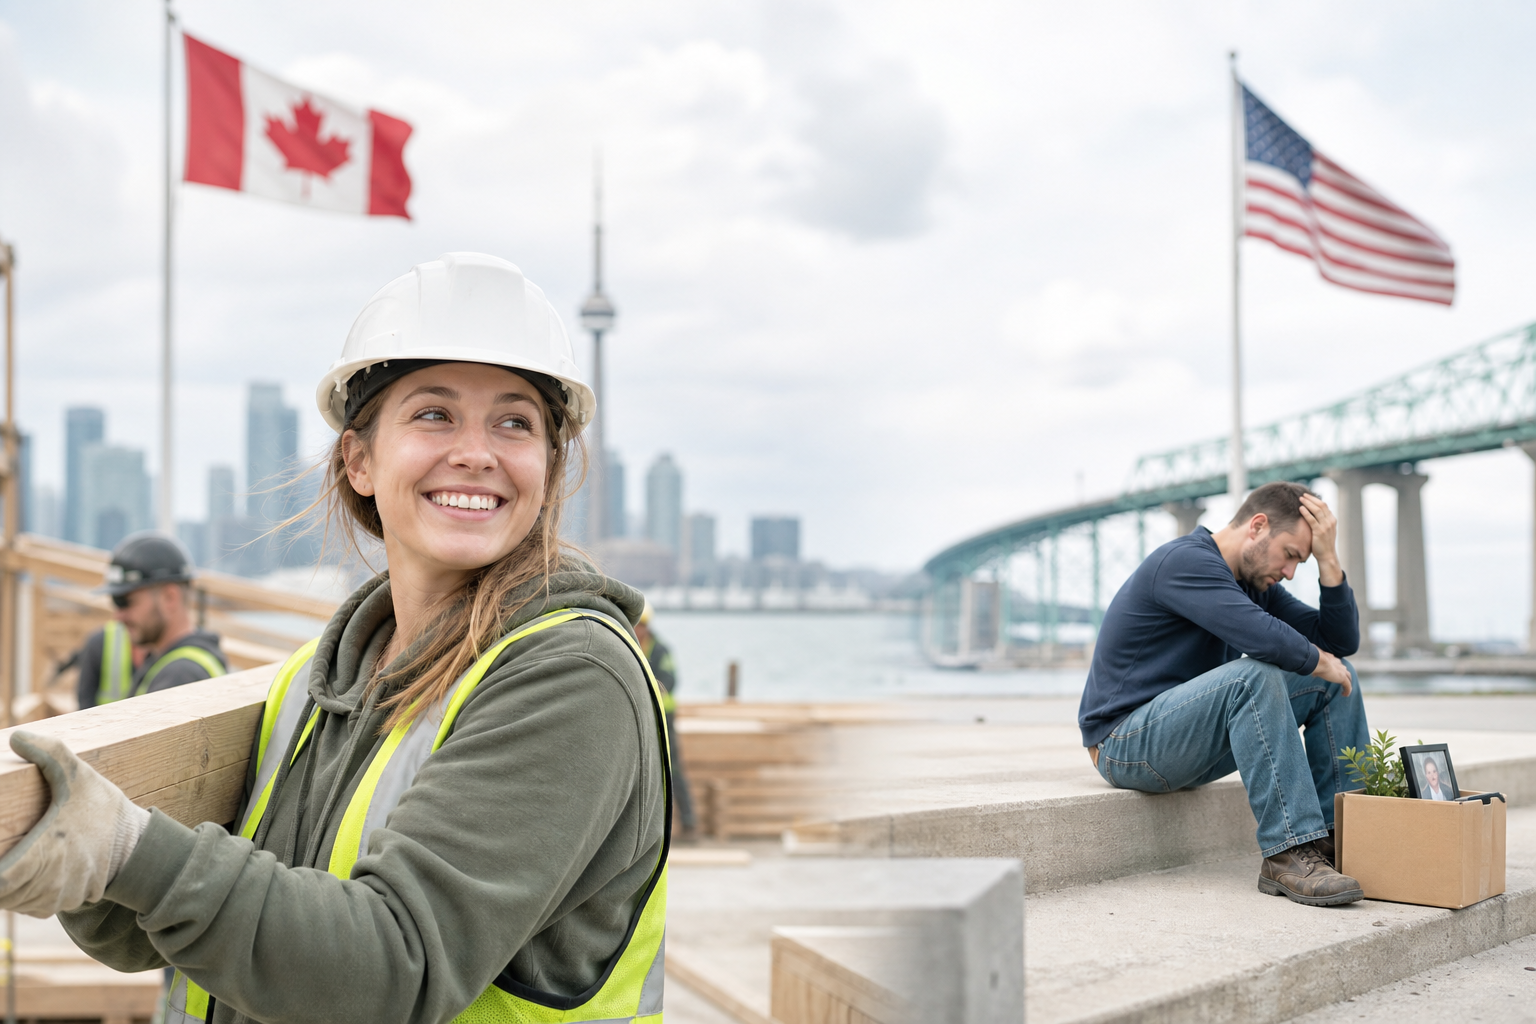

Canada added 75,000 jobs in July while the U.S. shed 23,000 and watched workers abandon the labour force entirely. The unemployment gap between the two countries now sits at the widest spread since early 2022, and the timing could not be worse for an administration that spent the last six months threatening tariffs to extract concessions from a supposedly fragile northern neighbour.
The leverage calculus was simple: crack Canada's job market, force Ottawa to the table, win CUSMA renegotiation points before the 2028 election cycle. But when the target economy is adding 60,000 jobs a month on a three-month average and dragging unemployment to a two-year low of 6.4%, the threat loses most of its bite.
The Split-Screen Labour Market
July's employment reports couldn't have painted a sharper contrast. Canada's 75,000-job gain crushed consensus forecasts near 20,000. The labour force expanded by 60,500 despite depopulation trends. Full-time employment among workers 25 and older, the cohort that drives mortgage demand, rose 33,000. Hours worked climbed 0.6%, enough for BMO's Doug Porter to estimate nearly 4% annualized GDP growth in Q3.
South of the border, nonfarm payrolls contracted by 23,000 against forecasts of +85,000. May and June were revised down by a combined 103,000. Unemployment fell to 4.1%, but only because labour force participation dropped to 61.4%, outside the pandemic, the lowest reading since the 1970s. CIBC called it a head scratcher: fewer jobs, fewer workers, falling headline rate. David Rosenberg was less charitable, pointing to three straight anaemic months and a three-month average he described as microscopic at 20,000.
The unemployment rate dropped for all the wrong reasons. People stopped looking.
What Gets Complicated for Tariff Leverage
Trump's August 19 tariff threat was designed to land on a weakened Canadian economy that would flinch at the prospect of trade restrictions. The actual economy he's facing is running too hot for the Bank of Canada's comfort and generating job growth that looks suspiciously durable.
Wage growth did cool to 2.8% year-over-year, the slowest in four years, which keeps inflationary pressure off the central bank's radar. That's the sweet spot: strong hiring, no pay spiral. The combination historically keeps central banks on hold, not scrambling to ease into a downturn.
Governing Council can point to that 2.8% wage figure every time someone asks why it isn't tightening into potentially 4% Q3 GDP. And with tariffs sitting directly in the policy path, no one in Ottawa will be eager to hike rates preemptively. Consensus has the Bank on hold through year-end, with markets fully pricing a 25-basis-point hike for January 2027.
The leverage problem is structural. Tariffs work as economic coercion when the target is already fragile and the threat credible. Canada's labour market just made the threat less credible.
Where This Leaves Fixed and Variable Borrowers
Canadian data argues for higher five-year government bond yields. Falling U.S. Treasury yields pull the other way. The two markets rarely move in opposite directions for long, but when they do, it creates a tug-of-war that makes forward pricing unreliable.
Setting client expectations for cheaper fixed pricing over the next few quarters is probably unwise. Any rate improvement is more likely to come from an unexpected crisis, including tariff fallout, than from a general disinflation-driven bond rally.
The variable pitch just lost its best argument. "Take variable, cuts are coming" doesn't survive 6.4% unemployment and 4% growth. Variable now has to win on upfront discount, hopes for a short hike cycle, prepayment flexibility, and disaster optionality. That's a harder sell.
Risk-averse borrowers with terms maturing in six to nine months should consider early renewal or a low-cost blend if the math justifies it. Waiting for rescue from a weakening economy that isn't weakening is a bet against the data.
The August 19 Wild Card
If Trump's tariffs land hard next week, Canada's hiring strength gets tested immediately and the entire rate conversation potentially reverses. That's the scenario where variable might pay as a hedge, though it's not a forecast.
Both Prime Minister Carney and President Trump have characterized the negotiations as "nasty" in recent days. Inflationary retaliation is on the table if the tariffs arrive as threatened. Prediction market Kalshi puts the odds of those 50% tariffs arriving on schedule at just 3 in 10, so the market thinks August 19 is far more likely to be an ordinary Wednesday than a crisis.
The tariff threat was designed to exploit weakness. The weakness didn't show up.
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure