De la Espriella's Colombia Gamble: Hard Right Turn as Violence Surges and Debt Mounts
The lawyer who built a career defending narcos and politicians now holds the country's highest office. Abelardo de la Espriella took the presidential oath on Friday, August 7, 2026, with the peso trading above 4,050 to the dollar and homicide rates climbing in Cauca and Nariño for the fourth straight quarter. The optics matter. This is not a technocrat inheriting a stable ship.
De la Espriella's platform centers on what he calls "mano dura", a throwback iron-fist doctrine that reverses Gustavo Petro's four-year experiment in "Paz Total." Where Petro negotiated ceasefires with the ELN and FARC splinter groups, the new president has vowed prosecution and military deployment. The Estado Mayor Central, which held fragile talks with the previous government, now faces a different calculus. Ceasefires expire. Commanders go back underground. The cycle restarts, but this time the state's posture is explicitly confrontational rather than conciliatory.
The security pivot arrives at an inconvenient fiscal moment. Colombia's public debt-to-GDP ratio hovers near 52%, high enough to keep S&P and Moody's watching for triggers. De la Espriella inherits a treasury constrained by rising debt service costs and limited revenue growth. His campaign promised both a military buildup and tax relief for businesses stifled under Petro's policies. Those promises sit awkwardly beside the budget math. Adding battalions costs money. Cutting corporate taxes reduces it. Something does not fit.
The Market Is Pricing In Doubt
International investors spent the Petro years complaining about regulatory uncertainty in the oil and gas sector. Exploration contracts stalled. New offshore blocks went untendered. The hope now is that De la Espriella reopens the valve. Energy exports fund a significant slice of government revenue, and restarting the licensing process could stabilize the fiscal outlook without touching the third rail of tax increases. But energy projects take years to yield revenue, and the debt service schedule does not wait. Bond markets are not rewarding the transition yet. Peso volatility since the inauguration suggests skepticism, not relief.
The question facing the new administration is whether a hard-right security agenda can coexist with the kind of investor confidence that prevents a ratings downgrade. Military escalation in rural departments historically correlates with higher human rights complaints from international NGOs. Those complaints, in turn, generate headlines that spook ESG-focused funds. De la Espriella may find that his base demands visible action against the Clan del Golfo while his finance minister needs to reassure Frankfurt and New York that Colombia remains a stable credit.
The Legislator Problem
De la Espriella does not control Congress the way his rhetoric suggests he controls the agenda. The legislative arithmetic is messier. His coalition holds a plurality, not a supermajority, meaning any attempt to pass controversial security reforms or restructure the tax code will require negotiation with centrist blocs that spent the campaign sitting out the ideological fight. A president elected on populist-conservative energy now has to practice the transactional politics he spent months denouncing. The mano dura works on a podium. It works less well in committee rooms where vote-counting determines outcomes.
The early weeks will clarify whether this administration can thread the gap between its base and its constraints. Campaign rhetoric promised total order. The treasury, the legislature, and the bond market are offering something closer to conditional cooperation. De la Espriella gambled that Colombians wanted a clean break from Petro's model. He won that bet. Whether he can deliver the break without triggering the fiscal or security crisis he inherited is now the only question that matters.

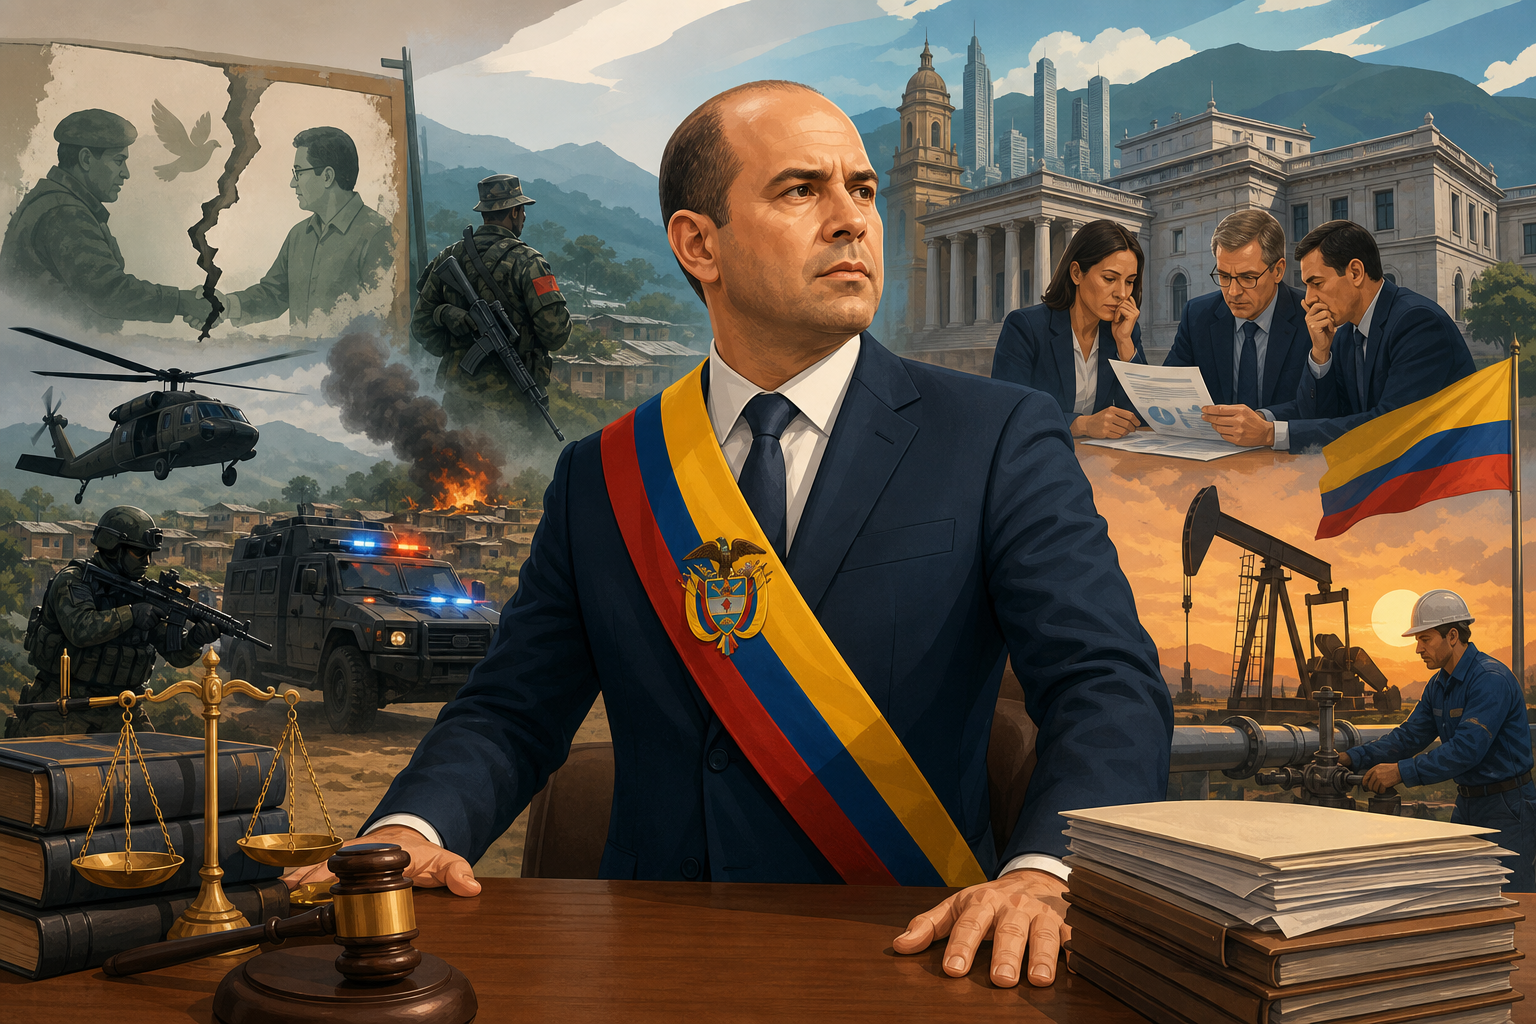

The lawyer who built a career defending narcos and politicians now holds the country's highest office. Abelardo de la Espriella took the presidential oath on Friday, August 7, 2026, with the peso trading above 4,050 to the dollar and homicide rates climbing in Cauca and Nariño for the fourth straight quarter. The optics matter. This is not a technocrat inheriting a stable ship.
De la Espriella's platform centers on what he calls "mano dura", a throwback iron-fist doctrine that reverses Gustavo Petro's four-year experiment in "Paz Total." Where Petro negotiated ceasefires with the ELN and FARC splinter groups, the new president has vowed prosecution and military deployment. The Estado Mayor Central, which held fragile talks with the previous government, now faces a different calculus. Ceasefires expire. Commanders go back underground. The cycle restarts, but this time the state's posture is explicitly confrontational rather than conciliatory.
The security pivot arrives at an inconvenient fiscal moment. Colombia's public debt-to-GDP ratio hovers near 52%, high enough to keep S&P and Moody's watching for triggers. De la Espriella inherits a treasury constrained by rising debt service costs and limited revenue growth. His campaign promised both a military buildup and tax relief for businesses stifled under Petro's policies. Those promises sit awkwardly beside the budget math. Adding battalions costs money. Cutting corporate taxes reduces it. Something does not fit.
The Market Is Pricing In Doubt
International investors spent the Petro years complaining about regulatory uncertainty in the oil and gas sector. Exploration contracts stalled. New offshore blocks went untendered. The hope now is that De la Espriella reopens the valve. Energy exports fund a significant slice of government revenue, and restarting the licensing process could stabilize the fiscal outlook without touching the third rail of tax increases. But energy projects take years to yield revenue, and the debt service schedule does not wait. Bond markets are not rewarding the transition yet. Peso volatility since the inauguration suggests skepticism, not relief.
The question facing the new administration is whether a hard-right security agenda can coexist with the kind of investor confidence that prevents a ratings downgrade. Military escalation in rural departments historically correlates with higher human rights complaints from international NGOs. Those complaints, in turn, generate headlines that spook ESG-focused funds. De la Espriella may find that his base demands visible action against the Clan del Golfo while his finance minister needs to reassure Frankfurt and New York that Colombia remains a stable credit.
The Legislator Problem
De la Espriella does not control Congress the way his rhetoric suggests he controls the agenda. The legislative arithmetic is messier. His coalition holds a plurality, not a supermajority, meaning any attempt to pass controversial security reforms or restructure the tax code will require negotiation with centrist blocs that spent the campaign sitting out the ideological fight. A president elected on populist-conservative energy now has to practice the transactional politics he spent months denouncing. The mano dura works on a podium. It works less well in committee rooms where vote-counting determines outcomes.
The early weeks will clarify whether this administration can thread the gap between its base and its constraints. Campaign rhetoric promised total order. The treasury, the legislature, and the bond market are offering something closer to conditional cooperation. De la Espriella gambled that Colombians wanted a clean break from Petro's model. He won that bet. Whether he can deliver the break without triggering the fiscal or security crisis he inherited is now the only question that matters.
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure