How Borrowing a Rental Down Payment Changes Your Interest Deduction
The Canada Revenue Agency does not care what property you used as collateral. It cares what you did with the money.
That distinction becomes expensive when a British Columbia or Alberta investor borrows against their home equity to fund a rental property down payment. The interest on that borrowed money is generally deductible against rental income, but only if the "use test" holds up under audit. The CRA applies what it calls the Direct Use Test: the borrowed funds must be used directly to earn income from property or business. If the link between the loan and the income-producing asset breaks, the deduction disappears.
The link breaks more easily than most investors expect.
Where the trail goes cold
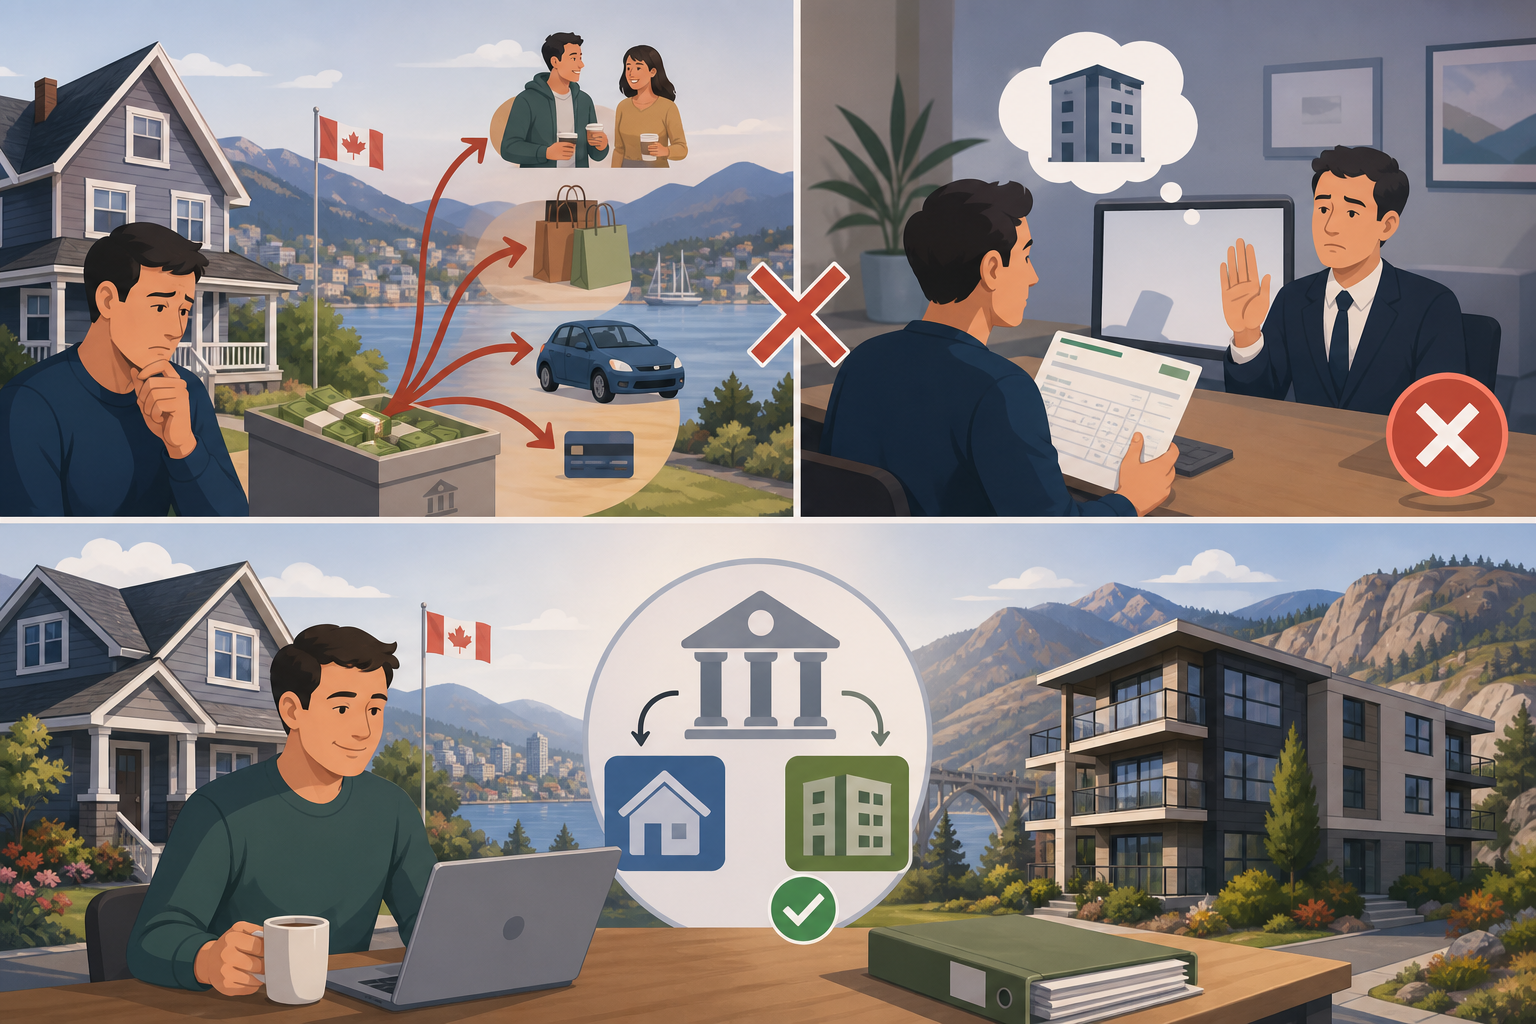
Borrowing $100,000 against a Victoria home and using it to purchase a Kelowna rental property sounds straightforward. The interest on that $100,000 should be deductible against the Kelowna property's rental income. But if the $100,000 passes through a personal chequing account that also holds grocery money, car payments, and vacation savings, the CRA may argue the funds were commingled with personal capital. At that point, the agency can deny the deduction on the grounds that you cannot prove which specific dollars went to the rental and which were used for consumption.
This is not theoretical caution. The CRA requires taxpayers who use mixed-use credit lines to demonstrate that borrowed money moved directly to the income-producing use, with the burden of proof sitting entirely on the investor. The burden of proof sits entirely with the investor. You must demonstrate that the borrowed money moved directly from the lender to the income-producing use. If the paper trail is unclear, the deduction is denied.
The loan should advance directly to the lawyer's trust account at closing, or to a segregated sub-account used only for the rental property. Many Home Equity Lines of Credit in BC and Alberta can be structured with dedicated segments: one segment for the rental down payment, another for personal expenses. Each segment generates its own monthly statement, with the interest on the rental segment deductible and the interest on the personal segment not deductible.
What counts as direct use
Under the Income Tax Act, interest is deductible when borrowed money is used for the purpose of earning income from a business or property. The Supreme Court of Canada confirmed in Singleton v. Canada that taxpayers can structure their affairs to borrow for investments and gain the deduction, provided the use is legitimate and documented.
The issue is documentation. A rental property generates rental income, so borrowing to purchase it satisfies the test. Borrowing to renovate the same property also qualifies, as long as the renovation expense is capital in nature and the funds trace directly to the contractor or materials. Borrowing to pay down the mortgage on your principal residence does not qualify, even if that principal residence later becomes a rental, because the character of the loan is determined at the moment the funds are used.
This creates a one-way street. Once a loan is designated for personal use, you cannot retroactively convert it to an investment loan by changing the property's use later. The reverse is also true: once funds are used for an investment, the interest remains deductible as long as the asset continues to exist or produce income, even if the rental becomes cash-flow negative.
The numbers that matter
Interest deductibility can be worth thousands annually. A $100,000 loan at 6.5% generates $6,500 in annual interest. If that loan is properly traced to a rental property producing $18,000 in gross rent, the $6,500 becomes a deduction against that income. If the trail is broken, the deduction is $0.
Only the interest is deductible. Principal repayments do not reduce taxable income. The deduction applies in the year the interest is paid, and it is limited to the amount of interest actually incurred on the specific portion of the loan used for the rental. If a $150,000 HELOC was used to buy a $100,000 rental down payment and a $50,000 vehicle, only two-thirds of the monthly interest is deductible, and only if the two uses were kept in separate sub-accounts from the start.
Investors often wait until tax season to sort this out. The stronger approach is to design the loan structure before the money moves.


The Canada Revenue Agency does not care what property you used as collateral. It cares what you did with the money.
That distinction becomes expensive when a British Columbia or Alberta investor borrows against their home equity to fund a rental property down payment. The interest on that borrowed money is generally deductible against rental income, but only if the "use test" holds up under audit. The CRA applies what it calls the Direct Use Test: the borrowed funds must be used directly to earn income from property or business. If the link between the loan and the income-producing asset breaks, the deduction disappears.
The link breaks more easily than most investors expect.
Where the trail goes cold
Borrowing $100,000 against a Victoria home and using it to purchase a Kelowna rental property sounds straightforward. The interest on that $100,000 should be deductible against the Kelowna property's rental income. But if the $100,000 passes through a personal chequing account that also holds grocery money, car payments, and vacation savings, the CRA may argue the funds were commingled with personal capital. At that point, the agency can deny the deduction on the grounds that you cannot prove which specific dollars went to the rental and which were used for consumption.
This is not theoretical caution. The CRA requires taxpayers who use mixed-use credit lines to demonstrate that borrowed money moved directly to the income-producing use, with the burden of proof sitting entirely on the investor. The burden of proof sits entirely with the investor. You must demonstrate that the borrowed money moved directly from the lender to the income-producing use. If the paper trail is unclear, the deduction is denied.
The loan should advance directly to the lawyer's trust account at closing, or to a segregated sub-account used only for the rental property. Many Home Equity Lines of Credit in BC and Alberta can be structured with dedicated segments: one segment for the rental down payment, another for personal expenses. Each segment generates its own monthly statement, with the interest on the rental segment deductible and the interest on the personal segment not deductible.
What counts as direct use
Under the Income Tax Act, interest is deductible when borrowed money is used for the purpose of earning income from a business or property. The Supreme Court of Canada confirmed in Singleton v. Canada that taxpayers can structure their affairs to borrow for investments and gain the deduction, provided the use is legitimate and documented.
The issue is documentation. A rental property generates rental income, so borrowing to purchase it satisfies the test. Borrowing to renovate the same property also qualifies, as long as the renovation expense is capital in nature and the funds trace directly to the contractor or materials. Borrowing to pay down the mortgage on your principal residence does not qualify, even if that principal residence later becomes a rental, because the character of the loan is determined at the moment the funds are used.
This creates a one-way street. Once a loan is designated for personal use, you cannot retroactively convert it to an investment loan by changing the property's use later. The reverse is also true: once funds are used for an investment, the interest remains deductible as long as the asset continues to exist or produce income, even if the rental becomes cash-flow negative.
The numbers that matter
Interest deductibility can be worth thousands annually. A $100,000 loan at 6.5% generates $6,500 in annual interest. If that loan is properly traced to a rental property producing $18,000 in gross rent, the $6,500 becomes a deduction against that income. If the trail is broken, the deduction is $0.
Only the interest is deductible. Principal repayments do not reduce taxable income. The deduction applies in the year the interest is paid, and it is limited to the amount of interest actually incurred on the specific portion of the loan used for the rental. If a $150,000 HELOC was used to buy a $100,000 rental down payment and a $50,000 vehicle, only two-thirds of the monthly interest is deductible, and only if the two uses were kept in separate sub-accounts from the start.
Investors often wait until tax season to sort this out. The stronger approach is to design the loan structure before the money moves.
Sources
Read Next
The Expensive Relief of Locking in at the Top
A 4% Mortgage Qualifies at 6%: Reading the Stress Test Correctly in 2026
Economists Forecast Interest Rates as a Herd, and Borrowers Pay for the Misses
Rents Move Last: Read Employer Investment to Spot Demand 18 to 24 Months Early