Manulife's $2.1 Billion Quarter Hides a 22% Profit Collapse in Canada
The company that spent the last decade building an Asian growth engine just posted numbers that show exactly why it needed one.
Manulife Financial Corp. reported $2.1 billion in net income for the second quarter of 2026, a figure that landed favorably with analysts focused on the headline. Core earnings hit $1.9 billion, up 6% year-over-year, and the company's Contractual Service Margin, the deferred profit pile under IFRS 17 accounting, grew roughly 9%. On the surface, this looks like steady execution. Strip out the geographic detail and you see something else: the Canadian business, which still represents the company's legal domicile and a meaningful chunk of its historical brand equity, saw net income fall 22% to $306 million.
That is not a rounding error. It is the domestic operation delivering less than one-seventh of total group profit while carrying a disproportionate share of legacy liability risk.
The Geography Problem
Manulife's Asian segment and its Global Wealth and Asset Management division are doing the work. New business value jumped roughly 17% globally, driven overwhelmingly by Hong Kong, mainland China, and Southeast Asian markets where demand for participating life products remains strong. GWAM pulled in $8.2 billion in net inflows during the quarter, continuing a multi-year run as the company's most stable profit generator. These businesses are capital-light, fee-driven, and insulated from the interest rate volatility that hammers traditional life insurance margins.
Canada, meanwhile, is dealing with higher-than-expected claims in certain life insurance segments and what management described as unfavorable market movements affecting local hedging positions. The translation: mortality experience went the wrong direction, investment returns didn't offset it, and the domestic book is more sensitive to these swings than the company would like. This is what happens when you are sitting on a mature portfolio of guaranteed products written decades ago under pricing assumptions that no longer hold.
The strongest objection here is that one quarter doesn't make a trend. Fair. But this isn't one quarter. Manulife has been systematically shifting capital away from Canada for years, offloading long-term care blocks, reinsuring legacy annuity risks, and throttling new sales of capital-intensive products in the domestic market. The 22% drop is not an aberration. It's the realization of a portfolio the company has been trying to shrink.
What the Market is Actually Pricing
Analysts covering Manulife care far more about core return on equity, currently around 16.2%, than they do about Canadian net income in isolation. The company's valuation is increasingly a bet on whether GWAM can keep compounding and whether the Asian franchise can grow NBV faster than capital requirements expand. The domestic business is background noise in that calculus, tolerated as long as it doesn't blow up.
The risk is that "doesn't blow up" becomes harder to guarantee. If claims trends in Canada don't normalize in the back half of 2026, and if hedging losses repeat, the domestic operation stops being neutral and starts being a drag that offsets growth elsewhere. That changes the math on share buybacks, dividend raises, and how much excess capital the company can actually deploy.
The other risk lives overseas. Manulife's dependence on Asian growth exposes it to regulatory shifts in mainland China and geopolitical friction that could disrupt cross-border capital flows. The Hong Kong protests in 2019 and subsequent regulatory tightening showed how fast a high-NBV market can turn unpredictable. A company that generates the majority of its momentum from that region does not have a domestically anchored fallback if things go sideways.
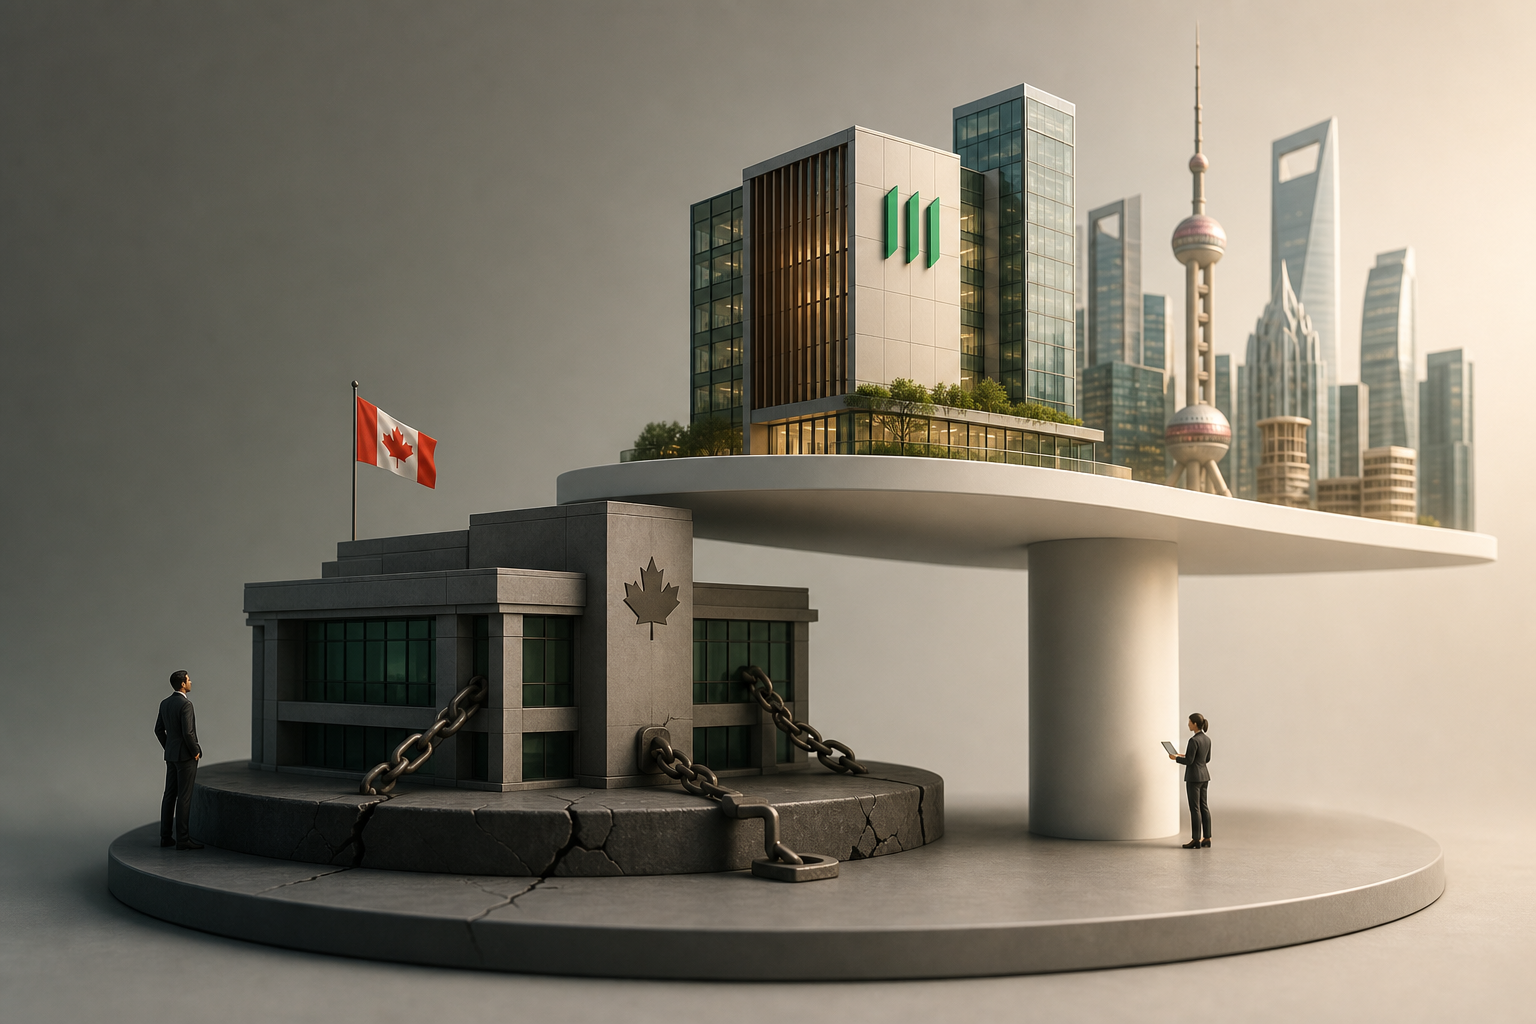
Manulife is running a two-speed model by necessity, not choice. The home market isn't funding future growth. It's being managed down as gracefully as possible while Asia and GWAM carry the load. The $2.1 billion headline hides that structural imbalance. The $306 million Canadian figure makes it visible.


The company that spent the last decade building an Asian growth engine just posted numbers that show exactly why it needed one.
Manulife Financial Corp. reported $2.1 billion in net income for the second quarter of 2026, a figure that landed favorably with analysts focused on the headline. Core earnings hit $1.9 billion, up 6% year-over-year, and the company's Contractual Service Margin, the deferred profit pile under IFRS 17 accounting, grew roughly 9%. On the surface, this looks like steady execution. Strip out the geographic detail and you see something else: the Canadian business, which still represents the company's legal domicile and a meaningful chunk of its historical brand equity, saw net income fall 22% to $306 million.
That is not a rounding error. It is the domestic operation delivering less than one-seventh of total group profit while carrying a disproportionate share of legacy liability risk.
The Geography Problem
Manulife's Asian segment and its Global Wealth and Asset Management division are doing the work. New business value jumped roughly 17% globally, driven overwhelmingly by Hong Kong, mainland China, and Southeast Asian markets where demand for participating life products remains strong. GWAM pulled in $8.2 billion in net inflows during the quarter, continuing a multi-year run as the company's most stable profit generator. These businesses are capital-light, fee-driven, and insulated from the interest rate volatility that hammers traditional life insurance margins.
Canada, meanwhile, is dealing with higher-than-expected claims in certain life insurance segments and what management described as unfavorable market movements affecting local hedging positions. The translation: mortality experience went the wrong direction, investment returns didn't offset it, and the domestic book is more sensitive to these swings than the company would like. This is what happens when you are sitting on a mature portfolio of guaranteed products written decades ago under pricing assumptions that no longer hold.
The strongest objection here is that one quarter doesn't make a trend. Fair. But this isn't one quarter. Manulife has been systematically shifting capital away from Canada for years, offloading long-term care blocks, reinsuring legacy annuity risks, and throttling new sales of capital-intensive products in the domestic market. The 22% drop is not an aberration. It's the realization of a portfolio the company has been trying to shrink.
What the Market is Actually Pricing
Analysts covering Manulife care far more about core return on equity, currently around 16.2%, than they do about Canadian net income in isolation. The company's valuation is increasingly a bet on whether GWAM can keep compounding and whether the Asian franchise can grow NBV faster than capital requirements expand. The domestic business is background noise in that calculus, tolerated as long as it doesn't blow up.
The risk is that "doesn't blow up" becomes harder to guarantee. If claims trends in Canada don't normalize in the back half of 2026, and if hedging losses repeat, the domestic operation stops being neutral and starts being a drag that offsets growth elsewhere. That changes the math on share buybacks, dividend raises, and how much excess capital the company can actually deploy.
The other risk lives overseas. Manulife's dependence on Asian growth exposes it to regulatory shifts in mainland China and geopolitical friction that could disrupt cross-border capital flows. The Hong Kong protests in 2019 and subsequent regulatory tightening showed how fast a high-NBV market can turn unpredictable. A company that generates the majority of its momentum from that region does not have a domestically anchored fallback if things go sideways.
Manulife is running a two-speed model by necessity, not choice. The home market isn't funding future growth. It's being managed down as gracefully as possible while Asia and GWAM carry the load. The $2.1 billion headline hides that structural imbalance. The $306 million Canadian figure makes it visible.
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure