Nearly half of Canada's newest homebuyers now bypass banks for brokers
A 27-year-old first-time buyer in Winnipeg with a stable tech job, no debt, and a $90,000 down payment walked into her bank in early 2025 expecting approval. She left with a spreadsheet of questions about debt-service ratios, stress-test thresholds, and loan-to-income caps she had never heard of. Two weeks later, she closed through a broker who mapped every regulatory hurdle in one sitting.
That pattern played out enough times last year to shift the structure of the mortgage market. Mortgage brokers now account for 38% of all originations nationally, according to Mortgage Professionals Canada's 2026 report. Among recent first-time buyers, the figure is 48%, meaning brokers facilitated nearly half of all entry purchases in a single year.
The complexity problem driving the shift
The standard explanation for broker growth is rate shopping. The real driver is regulatory density. Since OSFI introduced loan-to-income limits in 2024 and tightened stress-test formulas again in 2025, the mortgage application has become a multi-variable calculation most borrowers cannot perform themselves. A broker doesn't just find a lower rate. They interpret whether a given lender will approve based on how that lender models income, debt, property type, and down payment source under the current ruleset.
Consider a buyer earning $95,000 annually with $18,000 in student loan payments remaining. Under the revised LTI framework, their maximum borrowing capacity depends on which lender counts residual student debt as ongoing servicing and which writes it off post-verification. A branch employee at one of the Big Five banks will run that buyer through their institution's underwriting engine. A broker will test it against twelve engines and find the one with the formula that works.
That difference matters more than 15 basis points on rate. Buyers are learning this the first time they're declined.
Regional growth beyond the usual hubs
Broker adoption used to concentrate in Toronto and Vancouver, where prices forced buyers into creative lending structures. The 2025 data shows meaningful uptake across the Prairies and Atlantic Canada, regions where the median home price sits below $500,000 but where buyers still face the same federal stress tests as someone purchasing in Oakville.
A $400,000 home in Moncton requires the same regulatory navigation as a $1.2 million semi in Mississauga. The stress test doesn't scale to local affordability. Brokers do.
Monoline lenders as the hidden infrastructure
The broker channel works because monoline lenders exist. These are institutions that offer only mortgages, carry no branch network, and operate exclusively through broker referrals. They can undercut Big Five pricing because their cost structure is stripped down to underwriting and servicing. A buyer working directly with TD or RBC is competing against the bank's branch overhead. A buyer working with a broker gets access to a lender whose only expense is processing the loan.
Monoline lenders held roughly 30% of broker-originated volume in 2024. That share grew in 2025 as traditional banks tightened pipelines under capital adequacy requirements. The regulatory squeeze on bank lending creates the margin for broker-fed alternatives.
The renewal gap remains
Brokers are winning new business. They are not winning renewals. Banks still retain the majority of borrowers when the term expires, because renewal is opt-out rather than opt-in. The borrower receives a renewal offer in the mail, signs it, and stays. Breaking that inertia requires effort most people don't expend unless rate差 is severe.
This matters for how the 48% figure should be read. It measures acquisition, not retention. First-time buyers are choosing brokers at the point of entry, but whether they stay in the broker channel through two or three renewals is a separate question the data doesn't yet answer.
The lasting implication is generational. Millennials and Gen Z buyers are treating the mortgage as a standalone transaction, not as an anchor to a lifelong banking relationship. If that behavior holds through the renewal cycle, the 38% national share becomes a floor, not a ceiling.

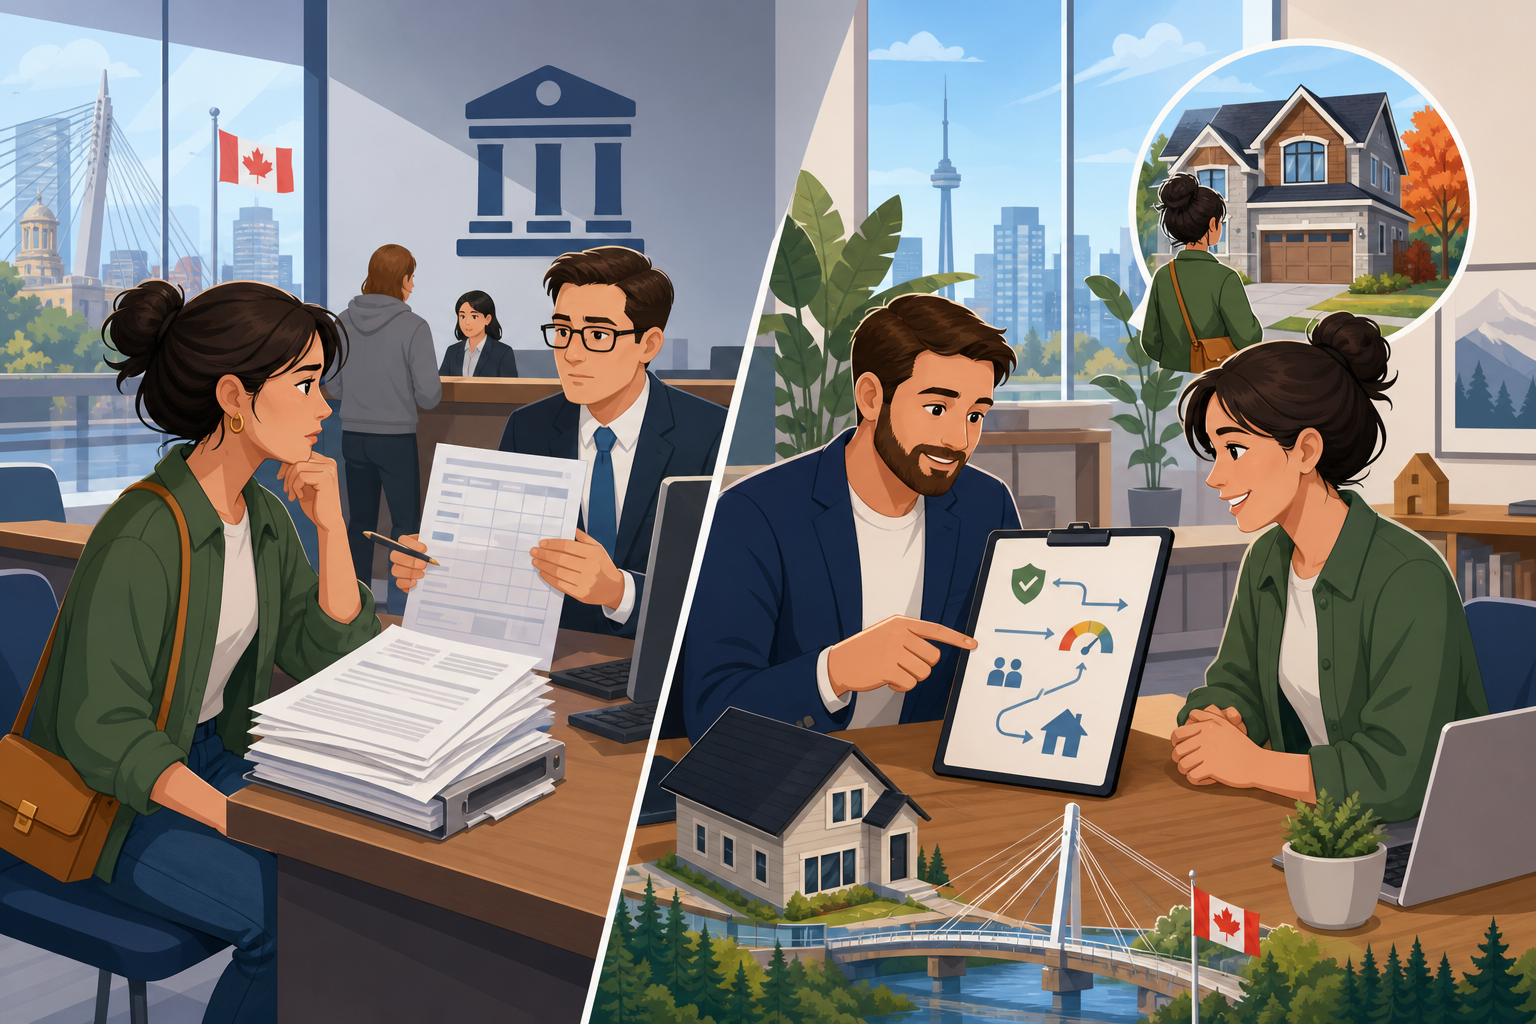

A 27-year-old first-time buyer in Winnipeg with a stable tech job, no debt, and a $90,000 down payment walked into her bank in early 2025 expecting approval. She left with a spreadsheet of questions about debt-service ratios, stress-test thresholds, and loan-to-income caps she had never heard of. Two weeks later, she closed through a broker who mapped every regulatory hurdle in one sitting.
That pattern played out enough times last year to shift the structure of the mortgage market. Mortgage brokers now account for 38% of all originations nationally, according to Mortgage Professionals Canada's 2026 report. Among recent first-time buyers, the figure is 48%, meaning brokers facilitated nearly half of all entry purchases in a single year.
The complexity problem driving the shift
The standard explanation for broker growth is rate shopping. The real driver is regulatory density. Since OSFI introduced loan-to-income limits in 2024 and tightened stress-test formulas again in 2025, the mortgage application has become a multi-variable calculation most borrowers cannot perform themselves. A broker doesn't just find a lower rate. They interpret whether a given lender will approve based on how that lender models income, debt, property type, and down payment source under the current ruleset.
Consider a buyer earning $95,000 annually with $18,000 in student loan payments remaining. Under the revised LTI framework, their maximum borrowing capacity depends on which lender counts residual student debt as ongoing servicing and which writes it off post-verification. A branch employee at one of the Big Five banks will run that buyer through their institution's underwriting engine. A broker will test it against twelve engines and find the one with the formula that works.
That difference matters more than 15 basis points on rate. Buyers are learning this the first time they're declined.
Regional growth beyond the usual hubs
Broker adoption used to concentrate in Toronto and Vancouver, where prices forced buyers into creative lending structures. The 2025 data shows meaningful uptake across the Prairies and Atlantic Canada, regions where the median home price sits below $500,000 but where buyers still face the same federal stress tests as someone purchasing in Oakville.
A $400,000 home in Moncton requires the same regulatory navigation as a $1.2 million semi in Mississauga. The stress test doesn't scale to local affordability. Brokers do.
Monoline lenders as the hidden infrastructure
The broker channel works because monoline lenders exist. These are institutions that offer only mortgages, carry no branch network, and operate exclusively through broker referrals. They can undercut Big Five pricing because their cost structure is stripped down to underwriting and servicing. A buyer working directly with TD or RBC is competing against the bank's branch overhead. A buyer working with a broker gets access to a lender whose only expense is processing the loan.
Monoline lenders held roughly 30% of broker-originated volume in 2024. That share grew in 2025 as traditional banks tightened pipelines under capital adequacy requirements. The regulatory squeeze on bank lending creates the margin for broker-fed alternatives.
The renewal gap remains
Brokers are winning new business. They are not winning renewals. Banks still retain the majority of borrowers when the term expires, because renewal is opt-out rather than opt-in. The borrower receives a renewal offer in the mail, signs it, and stays. Breaking that inertia requires effort most people don't expend unless rate差 is severe.
This matters for how the 48% figure should be read. It measures acquisition, not retention. First-time buyers are choosing brokers at the point of entry, but whether they stay in the broker channel through two or three renewals is a separate question the data doesn't yet answer.
The lasting implication is generational. Millennials and Gen Z buyers are treating the mortgage as a standalone transaction, not as an anchor to a lifelong banking relationship. If that behavior holds through the renewal cycle, the 38% national share becomes a floor, not a ceiling.
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure