Nvidia's $96B Quarter: When One Chipmaker's Earnings Move Global Markets
Jensen Huang now ranks as the eighth-richest person on Earth, a position he claimed within 48 hours of his company's latest earnings call. The $96.2 billion revenue figure Nvidia reported for its most recent quarter didn't just beat analyst expectations, it moved the needle on the S&P 500, shifted pension allocations across Canadian institutional portfolios, and reminded every fund manager holding a diversified ETF that "broad market exposure" now means heavy exposure to a single semiconductor firm headquartered in Santa Clara.
The scale is difficult to parse without context. Nvidia's quarterly revenue exceeds the annual GDP of Sri Lanka. It rivals the market capitalization of Costco. For a company selling chips, physical objects smaller than a credit card, the figure represents a structural shift in how capital flows through the global economy.
The Bet on Chips That Proved Out
Microsoft, Google, Amazon Web Services, and Meta are spending at rates that would have seemed delusional five years ago. AWS alone committed $32 billion in capital expenditures during the first half of 2026, much of it directed at Nvidia's H-series and Blackwell architecture chips. The logic is simple: if artificial intelligence is the next platform, the company that controls the hardware layer controls the terms of access.
This isn't speculative. The "AI arms race" narrative assumes companies are building data center capacity and AI software systems before they have fully solved monetization. But the revenue Nvidia posted confirms that hyperscalers are treating these chips as foundational the same way telecom companies treated fiber in the 1990s. Demand isn't frothy. It's structural.
Canada Pension Plan Investment Board (CPPIB) held roughly $4.8 billion in direct and indirect Nvidia exposure as of its last disclosed holdings update in Q1 2026. BC Investment Management Corporation (BCI), which manages public sector pension assets in British Columbia, has similarly positioned itself to capture tech-sector growth through significant Nvidia allocations. For a Victoria-based public sector retiree, this means Nvidia's quarterly swings now dictate a measurable portion of pension fund returns, whether they know it or not.
What Makes This Different From Prior Cycles
The semiconductor industry has seen booms before. Gaming drove Nvidia's valuation in the mid-2010s. Cryptocurrency mining created a spike in 2021. Both cycles cooled. The AI super-cycle feels different for three reasons.
First, the customer base is concentrated but solvent. Nvidia isn't selling to retail consumers or speculative crypto miners. It's selling to the five largest technology companies in the world, all of which have balance sheets capable of sustaining multi-year capital expenditure programs. These aren't customers who disappear when sentiment shifts.
Second, the software moat is deeper. Nvidia's CUDA platform, the software layer that sits between the hardware and the applications developers build, has become the de facto standard for AI workloads. Competitors like AMD have comparable chips. They don't have comparable ecosystems. Switching costs aren't just financial. They're architectural.
Third, the supply chain is tight and getting tighter. Nvidia's growth is constrained by Taiwan Semiconductor Manufacturing Company's (TSMC) production capacity, not by a lack of buyers. TSMC is currently running its most advanced fabs at full utilization, with lead times stretching into 2027 for certain Blackwell configurations. That's the opposite of a demand problem.
The Victoria Angle Most Investors Miss
Victoria's tech sector has grown significantly as a hub for software firms, ocean-tech R&D labs, and AI-focused remote work, supporting a knowledge economy increasingly reliant on Nvidia GPUs. These companies aren't just holding Nvidia stock. They're running code and models on Nvidia GPUs.
Local developers working on machine learning applications for marine data analysis, climate modelling, or supply chain planning are running their models on cloud instances backed by Nvidia GPUs. The CUDA toolkit is standard across most university AI labs in British Columbia. Nvidia isn't just an equity holding for Canadian investors. It's the literal substrate of the local knowledge economy.
This creates a feedback loop. As Nvidia's market cap grows, so does its ability to subsidize developer tools, academic partnerships, and cloud credits for startups. A Victoria-based AI firm gets free compute credits through Google Cloud or AWS, runs its models on Nvidia hardware, validates its business case, raises venture funding, and scales, at which point it becomes a paying customer for the same hardware. Nvidia wins at every step.
The Concentration Risk Nobody Wants to Name
The S&P 500 is weighted by market capitalization, which means Nvidia's $5 trillion valuation (as of August 2026) gives it outsize influence over index returns. On days when Nvidia moves 4%, the index often moves 0.8-1.2%, even when the other 499 stocks are mixed. For Canadian investors holding U.S.-listed index funds through their RRSPs or TFSAs, this is portfolio concentration wearing the costume of diversification.
A 60/40 balanced portfolio with 60% in a global equity ETF tracking the MSCI World Index is carrying roughly 3-4% Nvidia exposure, depending on the fund's methodology. That doesn't sound like much until you realize it's single-company exposure inside a product marketed as broadly diversified. During Nvidia's last earnings-driven rally, that 3-4% slice accounted for nearly a quarter of the portfolio's quarterly gain.
The risk isn't that Nvidia collapses. The risk is that its valuation implies perpetual execution without error. The company must navigate TSMC production constraints, manage U.S.-China export restrictions that limit sales of high-end chips to Chinese customers, and deliver generation-over-generation performance gains that justify continued capital spending by hyperscalers. Any stumble, a Blackwell production delay, a new competitor breaking CUDA's moat, a regulatory limit on data center energy consumption, gets amplified across global equity indexes.
The Energy Ceiling
Nvidia's growth is no longer constrained by demand or silicon production alone. It's constrained by electricity. A single Blackwell-based server rack consumes roughly 120 kilowatts under full load. A data center fielding 10,000 Nvidia GPUs requires the equivalent power of a small city. Utilities in Virginia, Texas, and Ireland are fielding requests for multi-gigawatt connections from hyperscalers planning to build AI-focused facilities.
Canada has an advantage here. Cheap hydroelectric power in Quebec and British Columbia has already attracted data center development. But the global constraint remains. If hyperscalers keep adding GPUs and data centers at the current pace, electricity availability becomes the limiting factor by 2028, not chip supply. Nvidia can't solve that with better engineering.
What the $96.2 Billion Actually Measures
Nvidia's revenue figure measures how much the world is willing to spend on chips and systems for artificial intelligence before those AI applications have generated enough revenue to justify the expense. It's a measure of conviction, not of realized economic value from AI itself.
That doesn't make it irrational. It makes it a bet. The hyperscalers are betting that owning the chips gives them optionality on every application built on top. Nvidia is betting that remaining the preferred supplier to those hyperscalers keeps it at the center of the value chain. Canadian institutional investors are betting that the bet holds.
The $96.2 billion quarter proves the bet is still on. It doesn't prove the bet was right. That gets answered in the 2027-2030 window, when the applications either justify the spending on chips and data centers or don't.

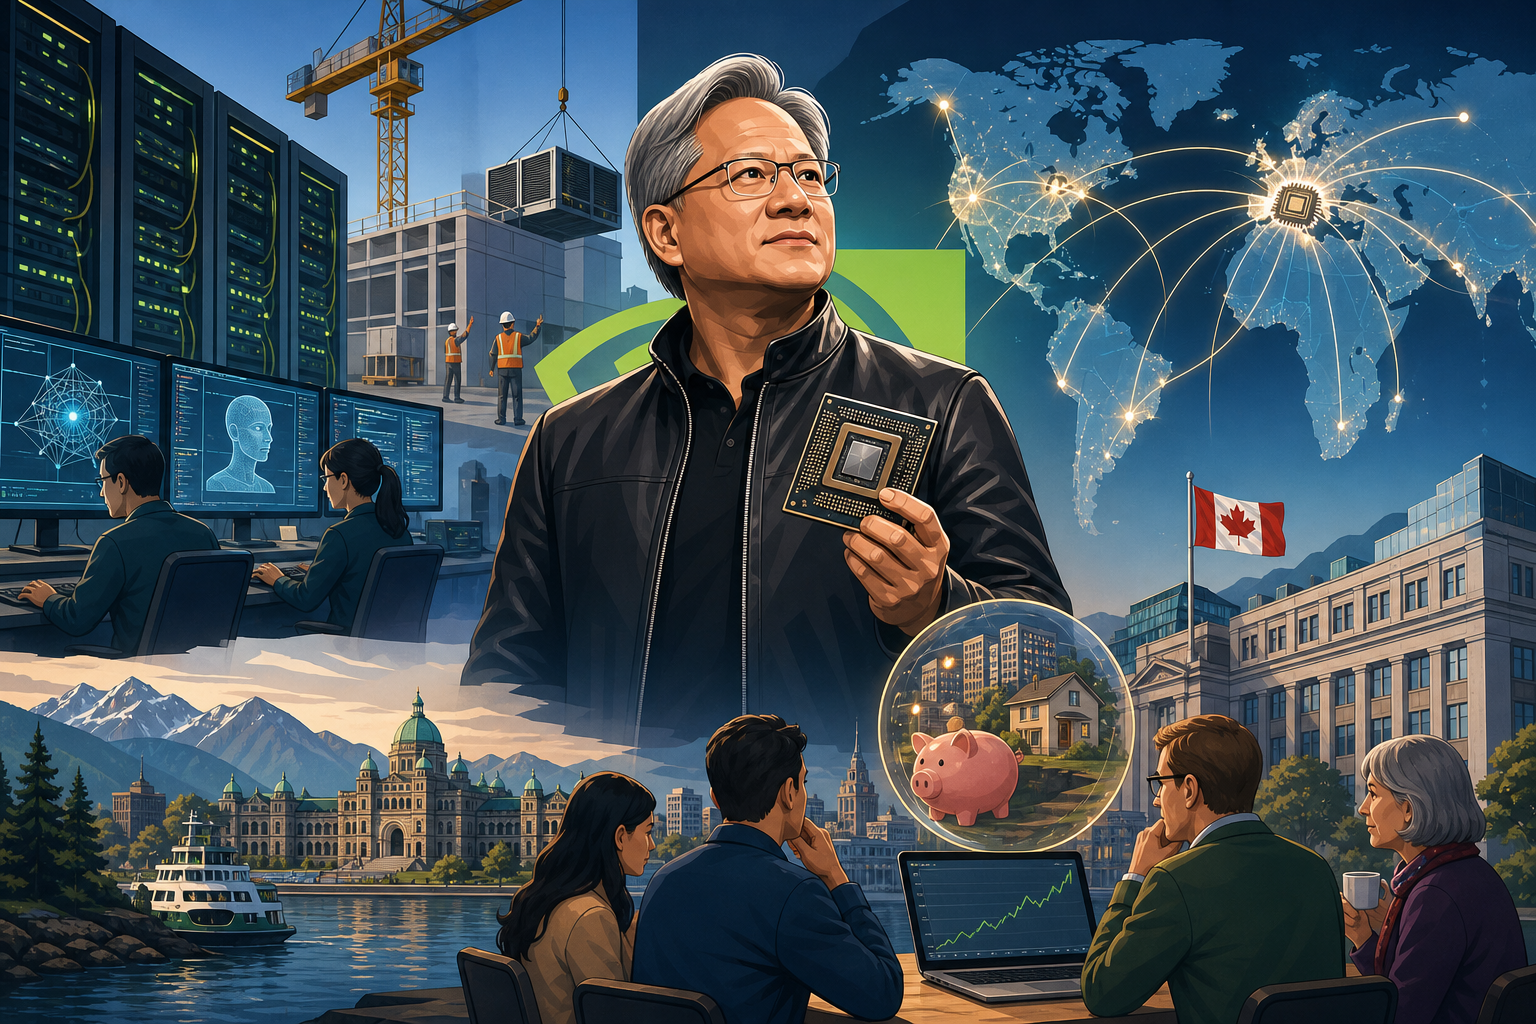

Jensen Huang now ranks as the eighth-richest person on Earth, a position he claimed within 48 hours of his company's latest earnings call. The $96.2 billion revenue figure Nvidia reported for its most recent quarter didn't just beat analyst expectations, it moved the needle on the S&P 500, shifted pension allocations across Canadian institutional portfolios, and reminded every fund manager holding a diversified ETF that "broad market exposure" now means heavy exposure to a single semiconductor firm headquartered in Santa Clara.
The scale is difficult to parse without context. Nvidia's quarterly revenue exceeds the annual GDP of Sri Lanka. It rivals the market capitalization of Costco. For a company selling chips, physical objects smaller than a credit card, the figure represents a structural shift in how capital flows through the global economy.
The Bet on Chips That Proved Out
Microsoft, Google, Amazon Web Services, and Meta are spending at rates that would have seemed delusional five years ago. AWS alone committed $32 billion in capital expenditures during the first half of 2026, much of it directed at Nvidia's H-series and Blackwell architecture chips. The logic is simple: if artificial intelligence is the next platform, the company that controls the hardware layer controls the terms of access.
This isn't speculative. The "AI arms race" narrative assumes companies are building data center capacity and AI software systems before they have fully solved monetization. But the revenue Nvidia posted confirms that hyperscalers are treating these chips as foundational the same way telecom companies treated fiber in the 1990s. Demand isn't frothy. It's structural.
Canada Pension Plan Investment Board (CPPIB) held roughly $4.8 billion in direct and indirect Nvidia exposure as of its last disclosed holdings update in Q1 2026. BC Investment Management Corporation (BCI), which manages public sector pension assets in British Columbia, has similarly positioned itself to capture tech-sector growth through significant Nvidia allocations. For a Victoria-based public sector retiree, this means Nvidia's quarterly swings now dictate a measurable portion of pension fund returns, whether they know it or not.
What Makes This Different From Prior Cycles
The semiconductor industry has seen booms before. Gaming drove Nvidia's valuation in the mid-2010s. Cryptocurrency mining created a spike in 2021. Both cycles cooled. The AI super-cycle feels different for three reasons.
First, the customer base is concentrated but solvent. Nvidia isn't selling to retail consumers or speculative crypto miners. It's selling to the five largest technology companies in the world, all of which have balance sheets capable of sustaining multi-year capital expenditure programs. These aren't customers who disappear when sentiment shifts.
Second, the software moat is deeper. Nvidia's CUDA platform, the software layer that sits between the hardware and the applications developers build, has become the de facto standard for AI workloads. Competitors like AMD have comparable chips. They don't have comparable ecosystems. Switching costs aren't just financial. They're architectural.
Third, the supply chain is tight and getting tighter. Nvidia's growth is constrained by Taiwan Semiconductor Manufacturing Company's (TSMC) production capacity, not by a lack of buyers. TSMC is currently running its most advanced fabs at full utilization, with lead times stretching into 2027 for certain Blackwell configurations. That's the opposite of a demand problem.
The Victoria Angle Most Investors Miss
Victoria's tech sector has grown significantly as a hub for software firms, ocean-tech R&D labs, and AI-focused remote work, supporting a knowledge economy increasingly reliant on Nvidia GPUs. These companies aren't just holding Nvidia stock. They're running code and models on Nvidia GPUs.
Local developers working on machine learning applications for marine data analysis, climate modelling, or supply chain planning are running their models on cloud instances backed by Nvidia GPUs. The CUDA toolkit is standard across most university AI labs in British Columbia. Nvidia isn't just an equity holding for Canadian investors. It's the literal substrate of the local knowledge economy.
This creates a feedback loop. As Nvidia's market cap grows, so does its ability to subsidize developer tools, academic partnerships, and cloud credits for startups. A Victoria-based AI firm gets free compute credits through Google Cloud or AWS, runs its models on Nvidia hardware, validates its business case, raises venture funding, and scales, at which point it becomes a paying customer for the same hardware. Nvidia wins at every step.
The Concentration Risk Nobody Wants to Name
The S&P 500 is weighted by market capitalization, which means Nvidia's $5 trillion valuation (as of August 2026) gives it outsize influence over index returns. On days when Nvidia moves 4%, the index often moves 0.8-1.2%, even when the other 499 stocks are mixed. For Canadian investors holding U.S.-listed index funds through their RRSPs or TFSAs, this is portfolio concentration wearing the costume of diversification.
A 60/40 balanced portfolio with 60% in a global equity ETF tracking the MSCI World Index is carrying roughly 3-4% Nvidia exposure, depending on the fund's methodology. That doesn't sound like much until you realize it's single-company exposure inside a product marketed as broadly diversified. During Nvidia's last earnings-driven rally, that 3-4% slice accounted for nearly a quarter of the portfolio's quarterly gain.
The risk isn't that Nvidia collapses. The risk is that its valuation implies perpetual execution without error. The company must navigate TSMC production constraints, manage U.S.-China export restrictions that limit sales of high-end chips to Chinese customers, and deliver generation-over-generation performance gains that justify continued capital spending by hyperscalers. Any stumble, a Blackwell production delay, a new competitor breaking CUDA's moat, a regulatory limit on data center energy consumption, gets amplified across global equity indexes.
The Energy Ceiling
Nvidia's growth is no longer constrained by demand or silicon production alone. It's constrained by electricity. A single Blackwell-based server rack consumes roughly 120 kilowatts under full load. A data center fielding 10,000 Nvidia GPUs requires the equivalent power of a small city. Utilities in Virginia, Texas, and Ireland are fielding requests for multi-gigawatt connections from hyperscalers planning to build AI-focused facilities.
Canada has an advantage here. Cheap hydroelectric power in Quebec and British Columbia has already attracted data center development. But the global constraint remains. If hyperscalers keep adding GPUs and data centers at the current pace, electricity availability becomes the limiting factor by 2028, not chip supply. Nvidia can't solve that with better engineering.
What the $96.2 Billion Actually Measures
Nvidia's revenue figure measures how much the world is willing to spend on chips and systems for artificial intelligence before those AI applications have generated enough revenue to justify the expense. It's a measure of conviction, not of realized economic value from AI itself.
That doesn't make it irrational. It makes it a bet. The hyperscalers are betting that owning the chips gives them optionality on every application built on top. Nvidia is betting that remaining the preferred supplier to those hyperscalers keeps it at the center of the value chain. Canadian institutional investors are betting that the bet holds.
The $96.2 billion quarter proves the bet is still on. It doesn't prove the bet was right. That gets answered in the 2027-2030 window, when the applications either justify the spending on chips and data centers or don't.
Sources
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure