Seven Documentation Mistakes That Disqualify Your Borrowed-Money Interest Deduction With CRA
A 2023 CRA review program flagged over 4,200 taxpayers who claimed interest deductions on loans that were never traceable to income-producing assets. Most lost the audit not because their intent was wrong, but because they couldn't prove where the money actually went.
Here's what trips people up.
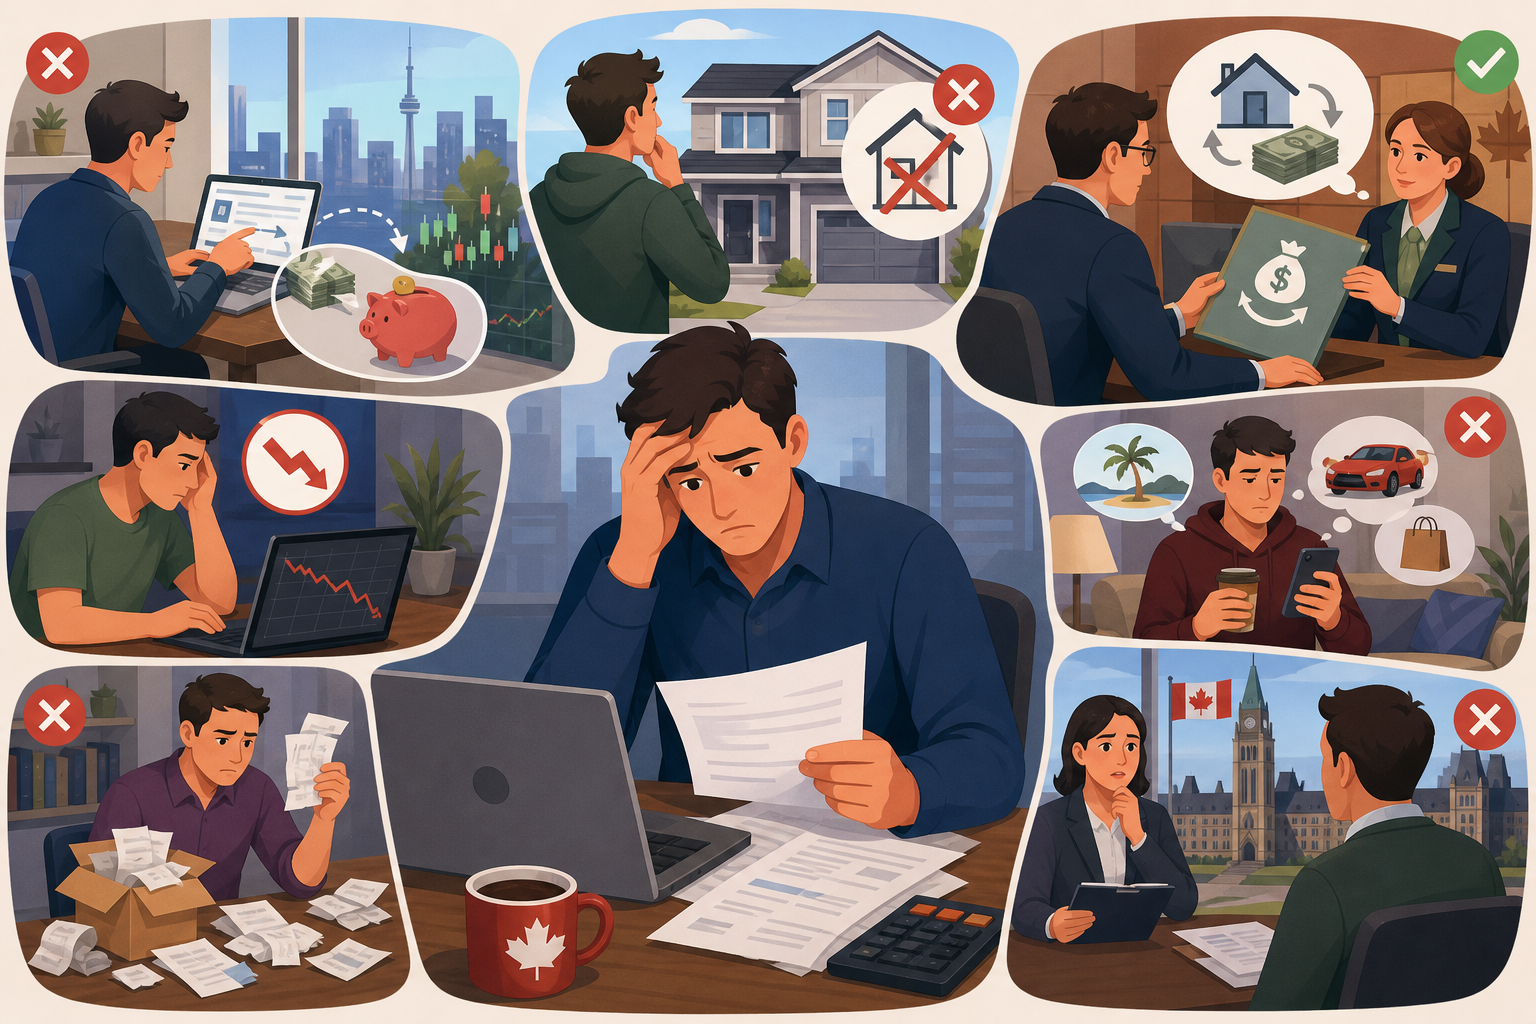
1. Opening a readvanceable HELOC but never segregating the borrowed funds into a separate account.
The CRA's tracing principle requires a direct, documentable link between the borrowed money and the asset that produces income. If you take $80,000 from your HELOC to buy dividend stocks but the money flows into your main chequing account alongside your paycheque and groceries, the trail is broken. Open a dedicated investment account. Transfer the borrowed funds into it. Buy the asset from that account. Never commingle.
2. Claiming interest on a loan used to buy a principal residence.
Your home is personal-use property. It doesn't generate taxable income. Even if the property appreciates, capital gains on a principal residence are exempt under the tax code, which means there's no taxable income stream to justify the deduction. This holds true whether you used a conventional mortgage or a HELOC. The CRA's position is ironclad: no taxable income from the asset, no interest deduction.
3. Investing in companies with stated no-dividend policies and expecting the interest to be deductible.
Section 20(1)(c) of the Income Tax Act requires a reasonable expectation of income. Income means interest, dividends, or rent, things that hit your T5 or T3. It does not mean capital gains. If you borrow to buy shares in a high-growth tech company that publicly states it will never pay dividends, the CRA's administrative position is that you have no reasonable expectation of income. The investment might triple. The interest stays non-deductible.
4. Selling the income-producing asset and not immediately reinvesting the proceeds, but continuing to deduct the interest.
Once you sell the dividend stock, the bond, the rental condo, the original "source" of income disappears. The interest on the loan that funded it stops being deductible unless you reinvest the sale proceeds into another qualifying asset right away. Parking the cash in a savings account for six months while you "decide what to do" kills the deduction for that period. The disappearing-source rules are unforgiving.
5. Borrowing money to contribute to an RRSP, TFSA, or FHSA and claiming the interest.
Registered accounts shelter income from tax. You don't report the dividends or interest earned inside them. The CRA will not allow you to deduct interest on money borrowed to fund a tax-sheltered vehicle. This is explicit in the legislation. If you want the deduction, the income has to be taxable when it's earned.
6. Keeping only bank statements as proof, with no investment account records showing what was actually purchased.
A printout showing a $50,000 wire from your HELOC is not enough. The CRA wants to see the brokerage statement showing what you bought, the date, the asset type, and proof that it's income-producing. If you're claiming $3,200 in interest annually, the auditor will ask for the T5 showing the dividends that justify it. No T5, no asset detail, no deduction.
7. Using indirect logic to claim the deduction, like borrowing for a vacation so you don't have to sell stocks.
The CRA looks at direct use. The loan funded the vacation. The vacation produces no income. The stocks you didn't sell are irrelevant to the analysis. Restructuring to create deductibility is legal, the Supreme Court affirmed this in Singleton, but it has to be done with proper legal separation and timing. Borrowing for one thing and mentally earmarking it as "freeing up cash for investments" doesn't count.
The one that costs people the most money is #1. Traceability is the entire game.


A 2023 CRA review program flagged over 4,200 taxpayers who claimed interest deductions on loans that were never traceable to income-producing assets. Most lost the audit not because their intent was wrong, but because they couldn't prove where the money actually went.
Here's what trips people up.
1. Opening a readvanceable HELOC but never segregating the borrowed funds into a separate account.
The CRA's tracing principle requires a direct, documentable link between the borrowed money and the asset that produces income. If you take $80,000 from your HELOC to buy dividend stocks but the money flows into your main chequing account alongside your paycheque and groceries, the trail is broken. Open a dedicated investment account. Transfer the borrowed funds into it. Buy the asset from that account. Never commingle.
2. Claiming interest on a loan used to buy a principal residence.
Your home is personal-use property. It doesn't generate taxable income. Even if the property appreciates, capital gains on a principal residence are exempt under the tax code, which means there's no taxable income stream to justify the deduction. This holds true whether you used a conventional mortgage or a HELOC. The CRA's position is ironclad: no taxable income from the asset, no interest deduction.
3. Investing in companies with stated no-dividend policies and expecting the interest to be deductible.
Section 20(1)(c) of the Income Tax Act requires a reasonable expectation of income. Income means interest, dividends, or rent, things that hit your T5 or T3. It does not mean capital gains. If you borrow to buy shares in a high-growth tech company that publicly states it will never pay dividends, the CRA's administrative position is that you have no reasonable expectation of income. The investment might triple. The interest stays non-deductible.
4. Selling the income-producing asset and not immediately reinvesting the proceeds, but continuing to deduct the interest.
Once you sell the dividend stock, the bond, the rental condo, the original "source" of income disappears. The interest on the loan that funded it stops being deductible unless you reinvest the sale proceeds into another qualifying asset right away. Parking the cash in a savings account for six months while you "decide what to do" kills the deduction for that period. The disappearing-source rules are unforgiving.
5. Borrowing money to contribute to an RRSP, TFSA, or FHSA and claiming the interest.
Registered accounts shelter income from tax. You don't report the dividends or interest earned inside them. The CRA will not allow you to deduct interest on money borrowed to fund a tax-sheltered vehicle. This is explicit in the legislation. If you want the deduction, the income has to be taxable when it's earned.
6. Keeping only bank statements as proof, with no investment account records showing what was actually purchased.
A printout showing a $50,000 wire from your HELOC is not enough. The CRA wants to see the brokerage statement showing what you bought, the date, the asset type, and proof that it's income-producing. If you're claiming $3,200 in interest annually, the auditor will ask for the T5 showing the dividends that justify it. No T5, no asset detail, no deduction.
7. Using indirect logic to claim the deduction, like borrowing for a vacation so you don't have to sell stocks.
The CRA looks at direct use. The loan funded the vacation. The vacation produces no income. The stocks you didn't sell are irrelevant to the analysis. Restructuring to create deductibility is legal, the Supreme Court affirmed this in Singleton, but it has to be done with proper legal separation and timing. Borrowing for one thing and mentally earmarking it as "freeing up cash for investments" doesn't count.
The one that costs people the most money is #1. Traceability is the entire game.
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure