Silence About Finances Is Toxic for Gen Z and Younger Millennial Couples
A twenty-six-year-old with $32,000 in student debt and a partner who just got approved for a $450,000 mortgage walks into a shared apartment in Victoria. One wants to accelerate the loan. The other wants joint ownership on the property. Neither has asked the other what they actually owe or earn. That gap, the one where the money conversation should be, destroys more relationships than most people admit.
Financial infidelity rates among younger couples now rival or exceed sexual infidelity as a source of breakups, according to surveys from major Canadian banks. The mechanics are simple. One person hides debt. The other discovers it during a mortgage application or a joint tax filing. Trust collapses. What looked like a partnership reveals itself as two people running separate balance sheets under one roof.
Why This Generation Can't Afford Silence
Gen Z and younger Millennials entered adulthood during the 2008 crisis, the pandemic, and the highest interest-rate environment in fifteen years. They don't have the luxury of deferring financial alignment. In Victoria, the benchmark price for a single-family home remains well above the national average as of mid-2026, often requiring two high incomes to even qualify. The median household income in Greater Victoria sits at $86,400. A couple earning that figure jointly cannot afford a detached home without external help or a radical debt-to-income calculation.
That affordability crunch makes early transparency necessary, not optional. Under British Columbia's Family Law Act, assets and debts divide 50/50 after two years of marriage-like cohabitation. Most couples cross that threshold without realizing they've just entered a legal partnership with binding financial consequences. The student loan balance that felt private in year one becomes a shared liability in year three, whether or not it was ever discussed.
The Tools Changed, the Silence Didn't
Younger couples use shared fintech apps and digital dashboards more than any prior generation. They'll sync calendars and streaming accounts. The bank login stays private. That disconnect, radical transparency in some domains, total opacity in others, creates a strange household structure where you know your partner's Spotify algorithm better than their credit score.
The old model, where one person "handled the bills," is fading. But it hasn't been replaced by something better. It's been replaced by two people independently managing money in parallel, which works until it doesn't. The breaking point is usually a large joint decision: buying a home, having a child, or one partner losing a job.
What Replaces Silence
Couples who avoid financial blowups tend to do three things early. They disclose all existing debt with balances and interest rates. They agree on a contribution model, equal splits, percentage-of-income, or something hybrid. They set shared goals with dollar figures and deadlines attached: $40,000 in combined savings by 2028, or maxing two TFSAs before making an FHSA contribution.
A cohabitation agreement or pre-nuptial agreement isn't planning for divorce. It's a business plan for the relationship. Younger couples in BC, where housing costs force financial interdependence faster than trust naturally builds, need that document more than their parents did.
The "financial first date" concept, laying out income, debt, and spending habits within the first few serious months, sounds clinical. It is. It also prevents the scenario where one partner discovers $18,000 in credit card debt two weeks before a mortgage closes.
The Cost of Waiting
In a high-rate environment, silence has a literal price. A couple that doesn't discuss debt consolidation or joint savings strategies leaves thousands of dollars on the table annually. The FHSA allows $8,000 in contributions per year as of 2026. Two people who don't coordinate that miss $16,000 in tax-advantaged room. Small misalignments compound.
The harder truth is that financial openness requires a foundation of safety. In abusive relationships, transparency becomes a weapon. The couples who can afford radical honesty are the ones who've already built trust in other domains. For everyone else, the conversation needs to happen anyway. Just slower, with boundaries.
Transparency isn't a love language. It's arithmetic. The couples who treat it that way stay together longer and fight less. The ones who don't discover that silence has its own cost structure, and it's steeper than honesty ever was.

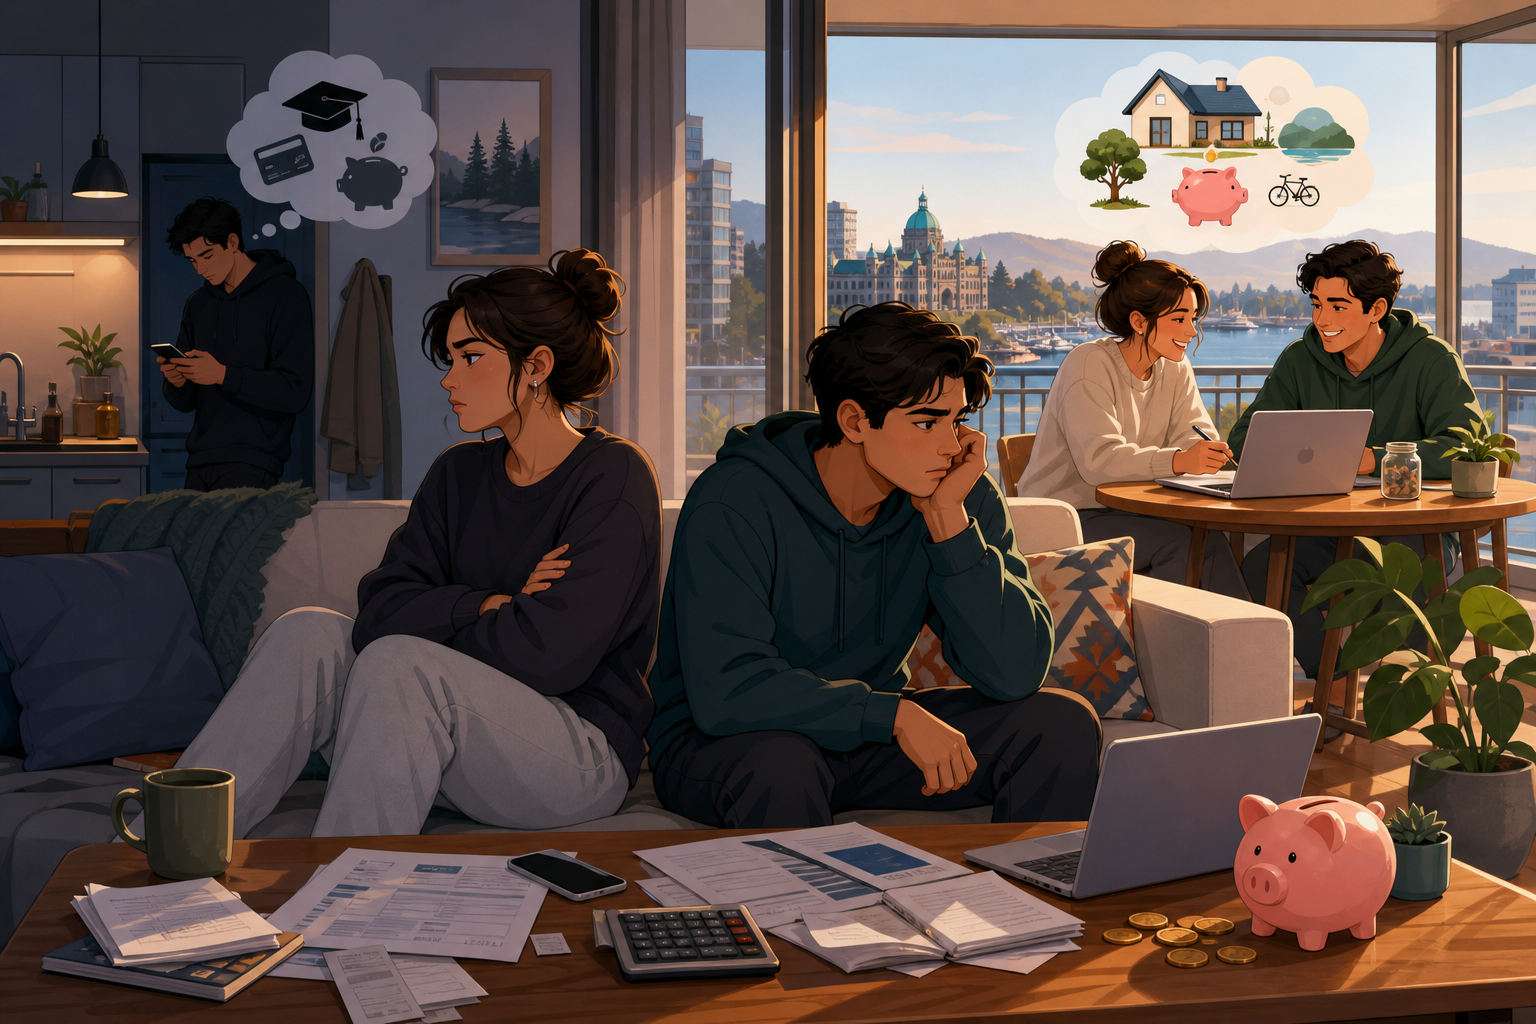

A twenty-six-year-old with $32,000 in student debt and a partner who just got approved for a $450,000 mortgage walks into a shared apartment in Victoria. One wants to accelerate the loan. The other wants joint ownership on the property. Neither has asked the other what they actually owe or earn. That gap, the one where the money conversation should be, destroys more relationships than most people admit.
Financial infidelity rates among younger couples now rival or exceed sexual infidelity as a source of breakups, according to surveys from major Canadian banks. The mechanics are simple. One person hides debt. The other discovers it during a mortgage application or a joint tax filing. Trust collapses. What looked like a partnership reveals itself as two people running separate balance sheets under one roof.
Why This Generation Can't Afford Silence
Gen Z and younger Millennials entered adulthood during the 2008 crisis, the pandemic, and the highest interest-rate environment in fifteen years. They don't have the luxury of deferring financial alignment. In Victoria, the benchmark price for a single-family home remains well above the national average as of mid-2026, often requiring two high incomes to even qualify. The median household income in Greater Victoria sits at $86,400. A couple earning that figure jointly cannot afford a detached home without external help or a radical debt-to-income calculation.
That affordability crunch makes early transparency necessary, not optional. Under British Columbia's Family Law Act, assets and debts divide 50/50 after two years of marriage-like cohabitation. Most couples cross that threshold without realizing they've just entered a legal partnership with binding financial consequences. The student loan balance that felt private in year one becomes a shared liability in year three, whether or not it was ever discussed.
The Tools Changed, the Silence Didn't
Younger couples use shared fintech apps and digital dashboards more than any prior generation. They'll sync calendars and streaming accounts. The bank login stays private. That disconnect, radical transparency in some domains, total opacity in others, creates a strange household structure where you know your partner's Spotify algorithm better than their credit score.
The old model, where one person "handled the bills," is fading. But it hasn't been replaced by something better. It's been replaced by two people independently managing money in parallel, which works until it doesn't. The breaking point is usually a large joint decision: buying a home, having a child, or one partner losing a job.
What Replaces Silence
Couples who avoid financial blowups tend to do three things early. They disclose all existing debt with balances and interest rates. They agree on a contribution model, equal splits, percentage-of-income, or something hybrid. They set shared goals with dollar figures and deadlines attached: $40,000 in combined savings by 2028, or maxing two TFSAs before making an FHSA contribution.
A cohabitation agreement or pre-nuptial agreement isn't planning for divorce. It's a business plan for the relationship. Younger couples in BC, where housing costs force financial interdependence faster than trust naturally builds, need that document more than their parents did.
The "financial first date" concept, laying out income, debt, and spending habits within the first few serious months, sounds clinical. It is. It also prevents the scenario where one partner discovers $18,000 in credit card debt two weeks before a mortgage closes.
The Cost of Waiting
In a high-rate environment, silence has a literal price. A couple that doesn't discuss debt consolidation or joint savings strategies leaves thousands of dollars on the table annually. The FHSA allows $8,000 in contributions per year as of 2026. Two people who don't coordinate that miss $16,000 in tax-advantaged room. Small misalignments compound.
The harder truth is that financial openness requires a foundation of safety. In abusive relationships, transparency becomes a weapon. The couples who can afford radical honesty are the ones who've already built trust in other domains. For everyone else, the conversation needs to happen anyway. Just slower, with boundaries.
Transparency isn't a love language. It's arithmetic. The couples who treat it that way stay together longer and fight less. The ones who don't discover that silence has its own cost structure, and it's steeper than honesty ever was.
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure