The $48,000 You Already Budgeted: How Refinance Savings Can Cut Five Years Off Your Mortgage
Morgan refinanced last March. The new mortgage dropped her monthly payment by $412. She and her partner celebrated with a weekend in Tofino, then watched the extra cash vanish into grocery drift and a second streaming service they don't remember subscribing to. Six months later, the $412 feels like it was never there.
The behavioral term for this is lifestyle creep. The money gets absorbed by the nearest expenditure gradient without registering as a decision. For most homeowners, refinancing is framed as relief, lower the payment, keep the house, move on. But the math of what happens to the gap between old payment and new payment is where the actual wealth event lives.
The Setup: What Refinancing Actually Produces
A standard BC refinance in 2026 looks like this: homeowner rolls $28,000 of credit card debt (19.8% APR) and a car loan ($9,400 at 7.2%) into a new mortgage at 5.1%. The consolidated payment drops by roughly $380 to $450 per month, depending on principal and term. That drop is real. It shows up in the bank account on the first of every month.
The question the lender never asks: what happens to that $380?
If it stays in chequing, it inflates into takeout, impulse purchases, slightly nicer versions of things the household was already buying. If it gets moved into a high-yield savings account at 2.8%, it earns about $128 over a year, pre-tax. Neither move is catastrophic. Both are wealth-neutral at best.
The third option is to treat the $380 as if it doesn't exist. Keep living on the pre-refinance budget. Redirect the difference straight back into the mortgage as a prepayment.
Scenario A: Savings Stay in Chequing
Assume $400/month in post-refinance savings. Over five years, that's $24,000 in cumulative cash flow. Some gets spent. Some sits. At a 2.8% savings rate (optimistic), the household ends up with roughly $25,400 after five years. The mortgage amortization stays on its original 23-year track. Total interest paid over the life of the loan: $187,000.
Scenario B: Savings Go to Principal
Same $400/month, but routed as an annual lump-sum prepayment under the standard 15% privilege most BC lenders allow. Over five years, the homeowner has prepaid $24,000 against principal. Because mortgage interest in Canada compounds semi-annually, early principal reduction has asymmetric impact. The amortization drops from 23 years to 18 years. Total interest paid: $139,000.
The difference is $48,000. That's the interest never paid because the principal was reduced while compounding still had two decades to run.
Why the Boundary Exists
This only works if three conditions hold. First, the homeowner must actually stay on the old budget. If the $400 drifts back into discretionary spend, there's nothing to prepay. Second, the mortgage must allow penalty-free prepayments within the annual limit (most do, but variable-rate products sometimes don't). Third, the household must have liquidity elsewhere. Money prepaid into a mortgage is locked. In an emergency, it cannot be pulled back out without a HELOC or another refinance.
Where this flips: if the homeowner still carries high-interest debt outside the mortgage (a remaining credit card at 21%, a payday loan, a tax balance), that debt should be cleared first. The guaranteed return on killing 21% debt is higher than the guaranteed return on prepaying a 5.1% mortgage.
But for a household that refinanced cleanly and has three months of expenses in reserve, redirecting the payment drop is the lowest-friction wealth move available. No new income required. No budget cut. Just treating the savings as if they were never savings at all.
The $48,000 is already in the budget. It's just currently being spent on nothing.

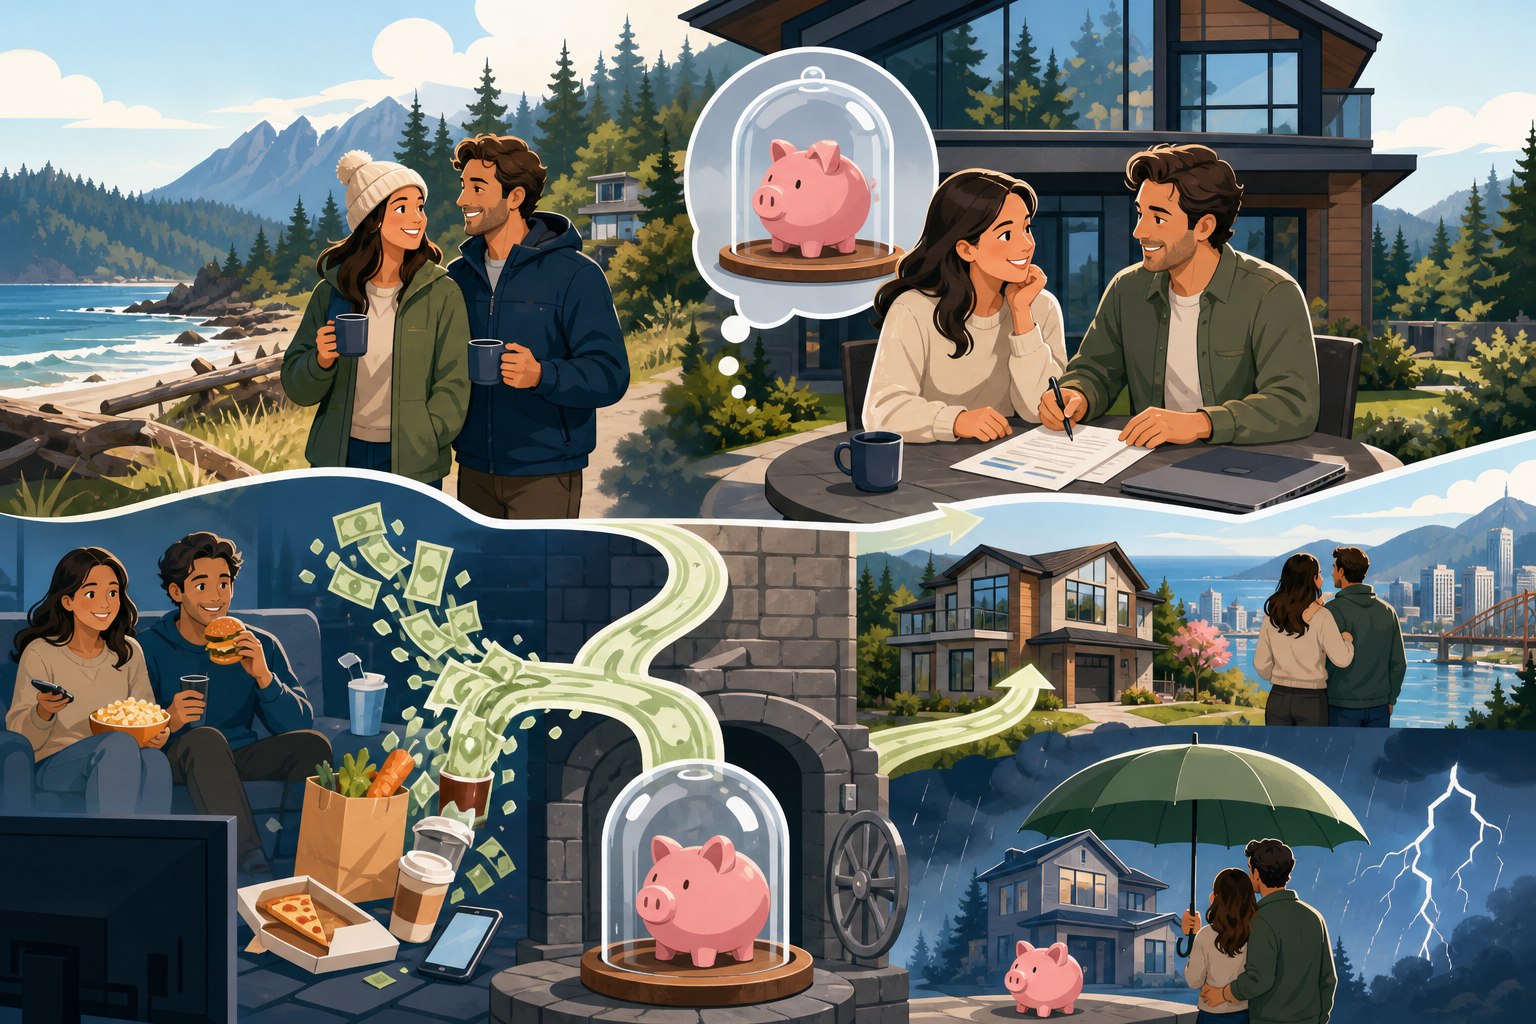

Morgan refinanced last March. The new mortgage dropped her monthly payment by $412. She and her partner celebrated with a weekend in Tofino, then watched the extra cash vanish into grocery drift and a second streaming service they don't remember subscribing to. Six months later, the $412 feels like it was never there.
The behavioral term for this is lifestyle creep. The money gets absorbed by the nearest expenditure gradient without registering as a decision. For most homeowners, refinancing is framed as relief, lower the payment, keep the house, move on. But the math of what happens to the gap between old payment and new payment is where the actual wealth event lives.
The Setup: What Refinancing Actually Produces
A standard BC refinance in 2026 looks like this: homeowner rolls $28,000 of credit card debt (19.8% APR) and a car loan ($9,400 at 7.2%) into a new mortgage at 5.1%. The consolidated payment drops by roughly $380 to $450 per month, depending on principal and term. That drop is real. It shows up in the bank account on the first of every month.
The question the lender never asks: what happens to that $380?
If it stays in chequing, it inflates into takeout, impulse purchases, slightly nicer versions of things the household was already buying. If it gets moved into a high-yield savings account at 2.8%, it earns about $128 over a year, pre-tax. Neither move is catastrophic. Both are wealth-neutral at best.
The third option is to treat the $380 as if it doesn't exist. Keep living on the pre-refinance budget. Redirect the difference straight back into the mortgage as a prepayment.
Scenario A: Savings Stay in Chequing
Assume $400/month in post-refinance savings. Over five years, that's $24,000 in cumulative cash flow. Some gets spent. Some sits. At a 2.8% savings rate (optimistic), the household ends up with roughly $25,400 after five years. The mortgage amortization stays on its original 23-year track. Total interest paid over the life of the loan: $187,000.
Scenario B: Savings Go to Principal
Same $400/month, but routed as an annual lump-sum prepayment under the standard 15% privilege most BC lenders allow. Over five years, the homeowner has prepaid $24,000 against principal. Because mortgage interest in Canada compounds semi-annually, early principal reduction has asymmetric impact. The amortization drops from 23 years to 18 years. Total interest paid: $139,000.
The difference is $48,000. That's the interest never paid because the principal was reduced while compounding still had two decades to run.
Why the Boundary Exists
This only works if three conditions hold. First, the homeowner must actually stay on the old budget. If the $400 drifts back into discretionary spend, there's nothing to prepay. Second, the mortgage must allow penalty-free prepayments within the annual limit (most do, but variable-rate products sometimes don't). Third, the household must have liquidity elsewhere. Money prepaid into a mortgage is locked. In an emergency, it cannot be pulled back out without a HELOC or another refinance.
Where this flips: if the homeowner still carries high-interest debt outside the mortgage (a remaining credit card at 21%, a payday loan, a tax balance), that debt should be cleared first. The guaranteed return on killing 21% debt is higher than the guaranteed return on prepaying a 5.1% mortgage.
But for a household that refinanced cleanly and has three months of expenses in reserve, redirecting the payment drop is the lowest-friction wealth move available. No new income required. No budget cut. Just treating the savings as if they were never savings at all.
The $48,000 is already in the budget. It's just currently being spent on nothing.
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure