US ETF Market Hits $15.7 Trillion as Product Complexity Outpaces Investor Understanding
A 62-year-old accountant in Phoenix bought what she thought was a simple S&P 500 tracker last April. What she actually purchased was a daily-reset leveraged fund that uses derivatives to amplify intraday moves by 200%. She discovered this in August when a 3% market dip erased 18% of her position in four trading sessions. The fund's prospectus described the mechanism in detail across eleven pages. She had not read past the ticker symbol and the word "growth."
The gap between what exists and what most buyers understand has become a feature of the landscape: a market grown so large and so fast that it outpaces the comprehension of most people entering it.
The Scale and the Shift
[1]The US exchange-traded fund market now holds approximately $15.7 trillion in assets as of May 2026. That figure alone is unremarkable in isolation, it represents continued migration from mutual funds into more tax-efficient wrappers. What has changed is the composition of new launches. Actively managed ETFs accounted for roughly 25% to 30% of net inflows during 2024 and 2025, despite representing a far smaller fraction of total assets. New product launches have accelerated dramatically—2025 saw a record 1,138 launches—and the momentum is entirely in structures the industry used to reserve for institutional desks.
The SEC's 2019 ETF Rule streamlined the approval process by eliminating the need for individual exemptive relief. This was intended to reduce regulatory friction. It worked. It also removed one of the few checkpoints that forced issuers to explain, in plain language, what a product actually did before bringing it to market. The result is a catalogue that now includes zero-days-to-expiration options funds, single-stock leveraged trackers, crypto-linked derivatives, and "defined outcome" structures that cap gains in exchange for buffering the first 10% or 15% of losses.
What Complexity Looks Like in Practice
A covered-call ETF generates monthly income by selling call options on its underlying holdings. The investor receives cash now in exchange for giving up price appreciation above the strike. That trade-off is explicit in the mechanics, but it is not explicit in the marketing, which leads with "monthly income" and buries the upside sacrifice in the disclosures. During the 2024, 2025 rally, investors in these funds collected their distributions while watching the S&P 500 climb 40% past the level where their gains were capped. The funds delivered exactly what they promised. The buyers thought they were buying something else.
Buffered ETFs are positioned as downside protection. They use options to limit the first tier of losses, often 10% or 15%, while capping gains at a predefined ceiling. The structure resets annually, and the protection only applies if the position is held through the full term. An investor who buys mid-cycle, or sells before the reset, receives neither the buffer nor the cap in the proportions advertised. The documents lay out the reset schedule; most investors do not read it.
The Liquidity Problem No One Mentions
Broad-market index ETFs trade on liquid, transparent markets. A position in SPY or VOO can be unwound in seconds at a spread of one cent. The new complex products rely on underlying derivatives that do not have the same liquidity profile. A flash crash in 2025 saw bid-ask spreads on certain leveraged and inverse ETFs widen to 4% for several minutes as market makers pulled quotes. Retail investors discovered that what felt liquid as cash can become illiquid in minutes: during the 2025 crash, market makers pulled from certain leveraged and inverse ETFs, and spreads widened to 4% for several minutes before recovering.
The bulk of these assets are anchored by boring products. The S&P 500, total market indexes, and plain-vanilla bond funds still represent the bulk of assets. But the trajectory is in the other direction, and the friction is not showing up in the data yet because most of these complex funds are too new to have experienced a real drawdown.

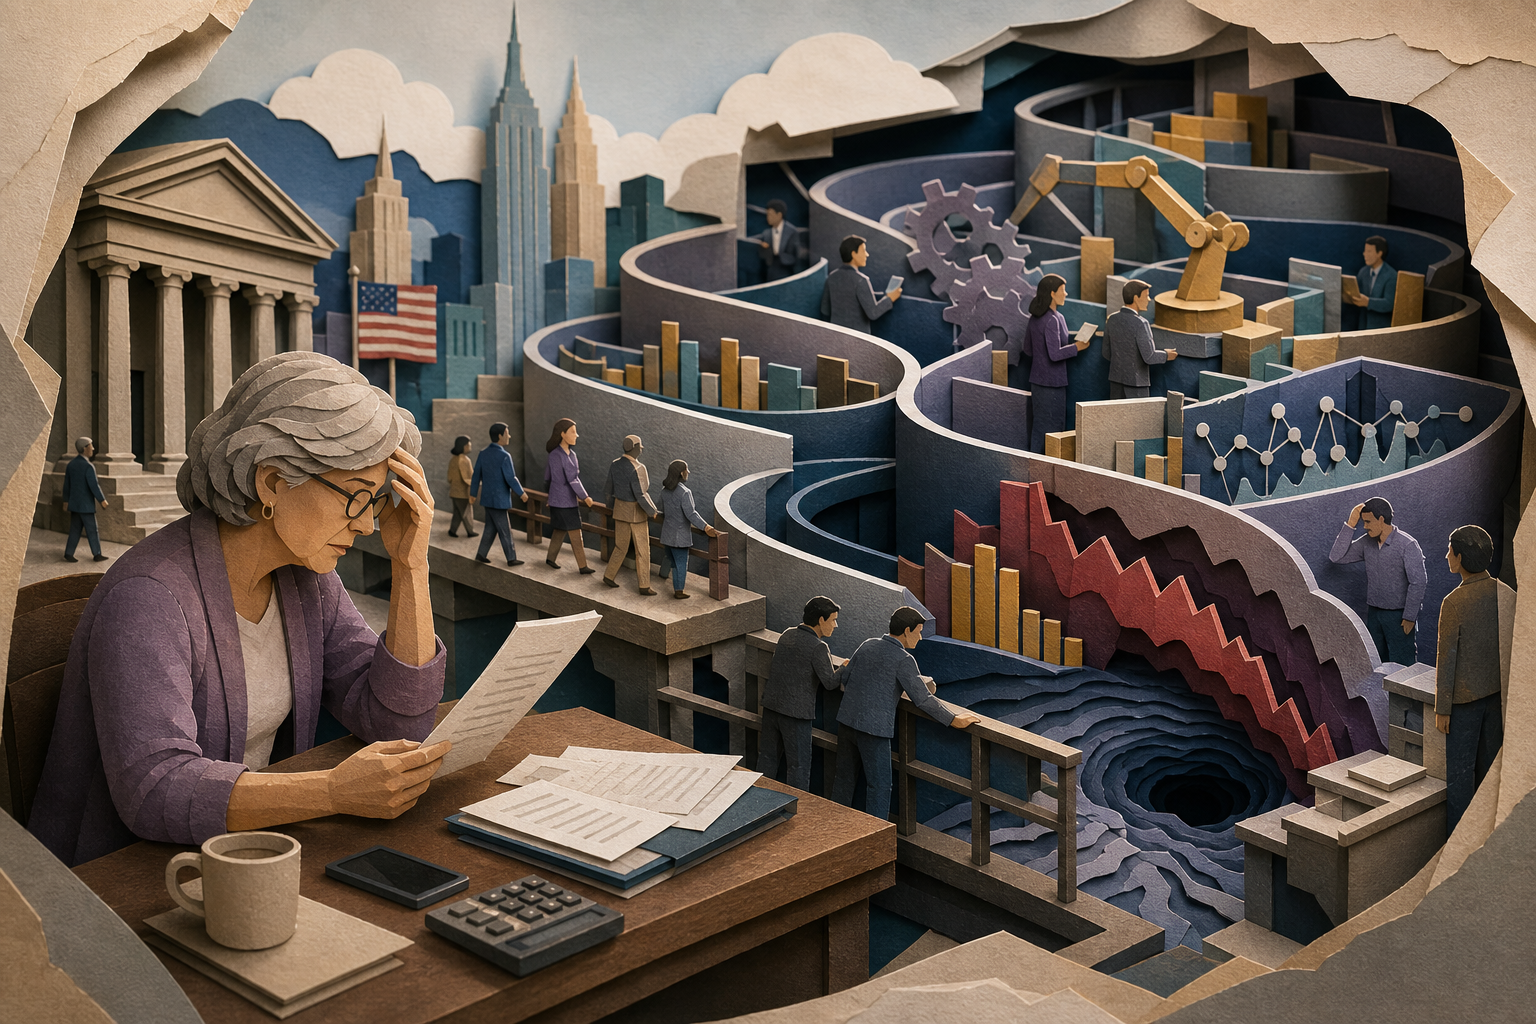

A 62-year-old accountant in Phoenix bought what she thought was a simple S&P 500 tracker last April. What she actually purchased was a daily-reset leveraged fund that uses derivatives to amplify intraday moves by 200%. She discovered this in August when a 3% market dip erased 18% of her position in four trading sessions. The fund's prospectus described the mechanism in detail across eleven pages. She had not read past the ticker symbol and the word "growth."
The gap between what exists and what most buyers understand has become a feature of the landscape: a market grown so large and so fast that it outpaces the comprehension of most people entering it.
The Scale and the Shift
[1]The US exchange-traded fund market now holds approximately $15.7 trillion in assets as of May 2026. That figure alone is unremarkable in isolation, it represents continued migration from mutual funds into more tax-efficient wrappers. What has changed is the composition of new launches. Actively managed ETFs accounted for roughly 25% to 30% of net inflows during 2024 and 2025, despite representing a far smaller fraction of total assets. New product launches have accelerated dramatically—2025 saw a record 1,138 launches—and the momentum is entirely in structures the industry used to reserve for institutional desks.
The SEC's 2019 ETF Rule streamlined the approval process by eliminating the need for individual exemptive relief. This was intended to reduce regulatory friction. It worked. It also removed one of the few checkpoints that forced issuers to explain, in plain language, what a product actually did before bringing it to market. The result is a catalogue that now includes zero-days-to-expiration options funds, single-stock leveraged trackers, crypto-linked derivatives, and "defined outcome" structures that cap gains in exchange for buffering the first 10% or 15% of losses.
What Complexity Looks Like in Practice
A covered-call ETF generates monthly income by selling call options on its underlying holdings. The investor receives cash now in exchange for giving up price appreciation above the strike. That trade-off is explicit in the mechanics, but it is not explicit in the marketing, which leads with "monthly income" and buries the upside sacrifice in the disclosures. During the 2024, 2025 rally, investors in these funds collected their distributions while watching the S&P 500 climb 40% past the level where their gains were capped. The funds delivered exactly what they promised. The buyers thought they were buying something else.
Buffered ETFs are positioned as downside protection. They use options to limit the first tier of losses, often 10% or 15%, while capping gains at a predefined ceiling. The structure resets annually, and the protection only applies if the position is held through the full term. An investor who buys mid-cycle, or sells before the reset, receives neither the buffer nor the cap in the proportions advertised. The documents lay out the reset schedule; most investors do not read it.
The Liquidity Problem No One Mentions
Broad-market index ETFs trade on liquid, transparent markets. A position in SPY or VOO can be unwound in seconds at a spread of one cent. The new complex products rely on underlying derivatives that do not have the same liquidity profile. A flash crash in 2025 saw bid-ask spreads on certain leveraged and inverse ETFs widen to 4% for several minutes as market makers pulled quotes. Retail investors discovered that what felt liquid as cash can become illiquid in minutes: during the 2025 crash, market makers pulled from certain leveraged and inverse ETFs, and spreads widened to 4% for several minutes before recovering.
The bulk of these assets are anchored by boring products. The S&P 500, total market indexes, and plain-vanilla bond funds still represent the bulk of assets. But the trajectory is in the other direction, and the friction is not showing up in the data yet because most of these complex funds are too new to have experienced a real drawdown.
Sources
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure