Why Tech's AI Spending Spree Could Be Poisoning Your Next Borrowing Decision
Microsoft spent $14.9 billion on AI servers and data centres in the first quarter of 2024 alone. Meta committed $65 billion for the full year. Alphabet's 2024 capital expenditures topped $50 billion, most of it earmarked for AI data centres and chips. Not one of these companies has published a credible internal rate of return on those investments.
They don't need to. The market rewards the narrative.
That's a problem for you, even if you've never written a line of code. Because the same logic that lets a tech CEO justify $14 billion in spending with no cash flow proof is now bleeding into real estate acquisitions, practice expansions, and equipment financing across every other sector. The belief that "we have to spend to stay competitive" has become self-justifying. And lenders, investors, and business owners are all nodding along.
Here's what actually happens when narrative replaces numbers.
The AI Capex Model Has No Clothes
Tech executives are responding to a market that has decided AI spending is strategic regardless of
Why Tech's AI Spending Spree Could Be Poisoning Your Next Borrowing Decision
In Q1 2024, Microsoft dropped $14.9 billion on AI servers and data centres. No published IRR. No disclosed payback period. No cash flow model shared with analysts. The stock went up anyway.
That tells you something about how capital allocation works when the market wants to believe a story. And that should worry you, because the same reasoning is now sitting across the table when you pitch your practice expansion, your equipment lease, or your next rental property acquisition.
The Logic That Travels
Here's the mechanism. A lender or investor watches Alphabet commit $50 billion to data centres on the promise that AI will reshape search, cloud services, and advertising, all categories where Alphabet already prints cash. The spending gets labelled "strategic." The market applauds. Nobody asks for a three-year breakeven or demands to see margin projections.
Then a dentist in Kelowna walks in asking for $800,000 to add two chairs, hire an associate, and expand into cosmetic work. The business plan projects 18-month payback based on current patient volume and local demographics. The loan officer, who spent the morning reading about Meta's $65 billion AI commitment, now sees the dentist's request through a lens that has been subtly adjusted. If Meta can justify that kind of spend on narrative, why can't this practice expansion work on optimism about patient growth?
The difference is that Meta has $120 billion in annual revenue and generates $40 billion in free cash flow even while lighting money on fire for AI experiments. The dentist has $1.2 million in collections and is asking to lever up on the assumption that demand will follow supply. Those are not the same risk profiles. But the framing has bled across.
What Narrative Spending Actually Requires
Tech companies can afford to spend without immediate returns because they sit on fortresses of existing cash generation. Microsoft's Azure business alone brought in $25 billion in Q1 2024. That buys a lot of patience for unproven AI bets. The board isn't panicking because the core business funds the experiment.
Most business owners and real estate investors are not working from that position. You're borrowing against projected cash flow, not realized cash reserves. Your lender is underwriting based on what you've done and what the market will support, not on what the narrative suggests might happen if everything breaks your way.
When you justify a borrowing decision with "we have to spend to stay competitive," you're importing tech's framing without tech's balance sheet. The question isn't whether the spending might pay off. The question is what happens to your debt service if it doesn't pay off in the timeline you projected.
The Underwriting Gap
Lenders tightened standards after 2023's rate shock, but the appetite for growth stories hasn't disappeared. A well-packaged expansion plan that sounds strategic can still get funded, especially if the borrower has been reliable in the past. The problem is that "strategic" has started to mean "the narrative makes sense" rather than "the cash flow model holds under stress."
A concrete example: a contractor in the Fraser Valley takes on $600,000 in equipment financing to add capacity for a new housing development project. The justification is that the project pipeline looks strong and competitors are scaling. The loan officer approves it because the sector is hot and the narrative fits. But the housing pipeline in late 2024 has started to slow as higher rates bite. The contractor is now carrying debt service on equipment that isn't fully utilized, and the revenue that was supposed to cover it hasn't materialized.
That's the poisoning. The decision was underwritten on optimism shaped by a different sector's tolerance for speculative spending. When rates and demand shifted, the equipment that looked like a sound bet became a drag on cash flow.
How to Inoculate Your Own Decisions
The fix is arithmetic. Before you commit to debt-financed growth, model the downside case with numbers that would make a pessimist nod. What happens if patient volume doesn't grow as fast as projected? What happens if the rental market softens and you carry two months of vacancy per year instead of zero? What happens if the equipment you're financing sits idle 40% of the time instead of 10%?
If the debt service still works in that scenario, borrow. If it doesn't, the narrative isn't good enough to bridge the gap. Tech companies can afford to be wrong because they're spending profits. You're spending borrowed money. The downside isn't a missed quarter. It's a liquidity crisis.
The market rewards tech for betting big on AI because tech can survive being wrong. You probably can't. That difference should govern every borrowing decision you make in 2026.

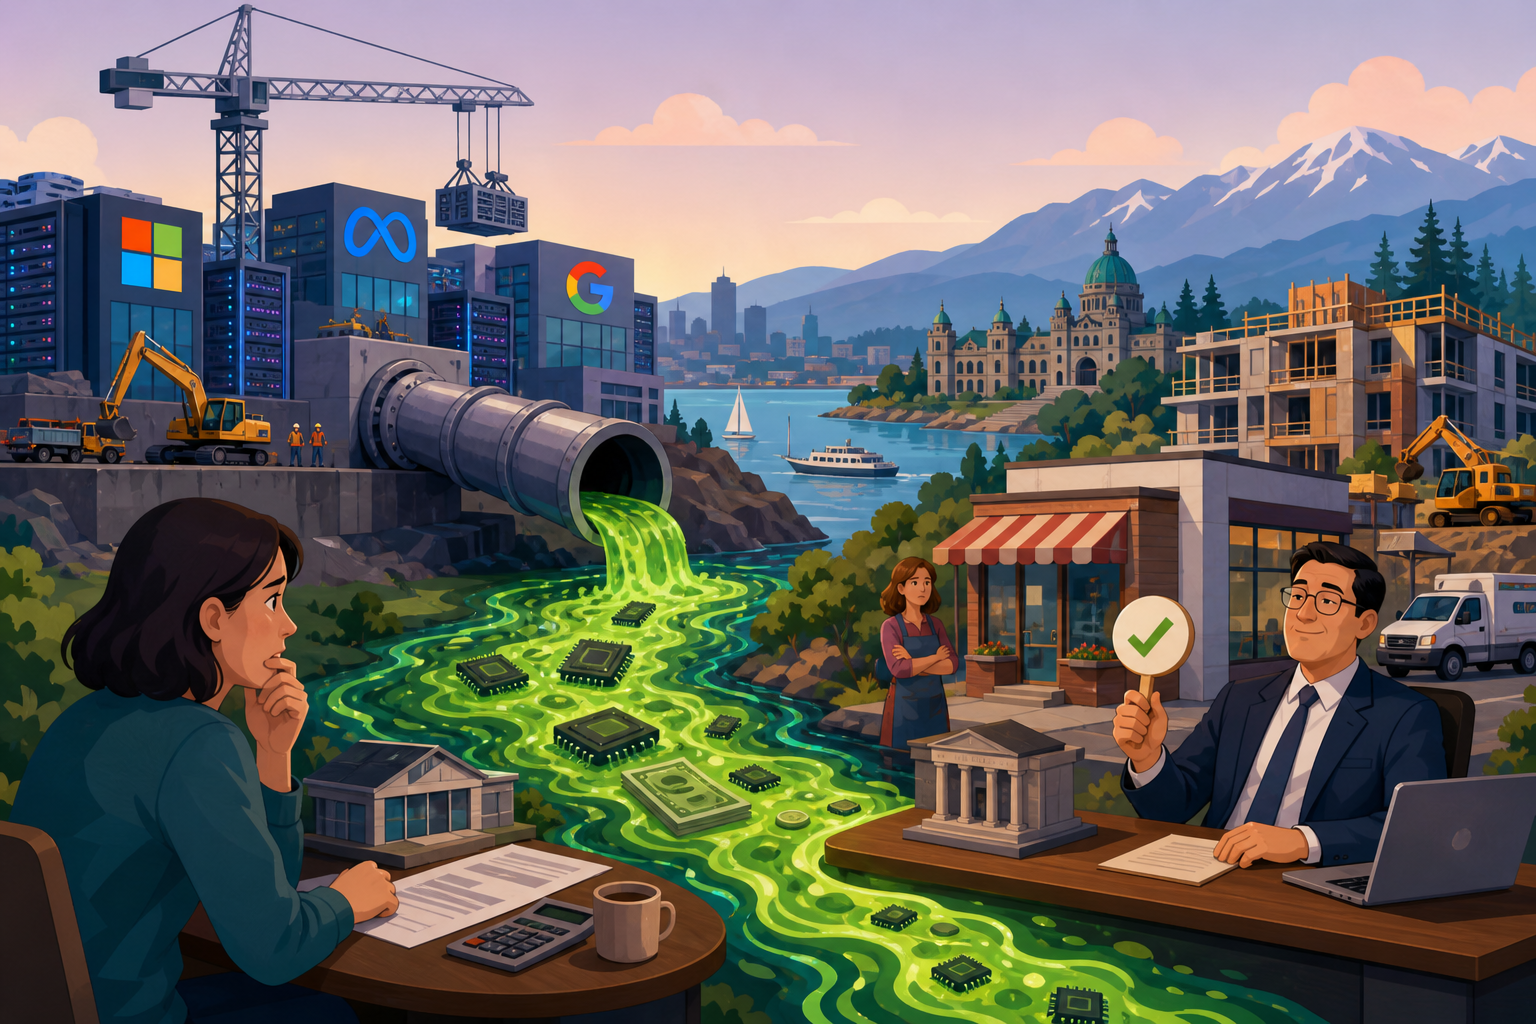

Microsoft spent $14.9 billion on AI servers and data centres in the first quarter of 2024 alone. Meta committed $65 billion for the full year. Alphabet's 2024 capital expenditures topped $50 billion, most of it earmarked for AI data centres and chips. Not one of these companies has published a credible internal rate of return on those investments.
They don't need to. The market rewards the narrative.
That's a problem for you, even if you've never written a line of code. Because the same logic that lets a tech CEO justify $14 billion in spending with no cash flow proof is now bleeding into real estate acquisitions, practice expansions, and equipment financing across every other sector. The belief that "we have to spend to stay competitive" has become self-justifying. And lenders, investors, and business owners are all nodding along.
Here's what actually happens when narrative replaces numbers.
The AI Capex Model Has No Clothes
Tech executives are responding to a market that has decided AI spending is strategic regardless of
Why Tech's AI Spending Spree Could Be Poisoning Your Next Borrowing Decision
In Q1 2024, Microsoft dropped $14.9 billion on AI servers and data centres. No published IRR. No disclosed payback period. No cash flow model shared with analysts. The stock went up anyway.
That tells you something about how capital allocation works when the market wants to believe a story. And that should worry you, because the same reasoning is now sitting across the table when you pitch your practice expansion, your equipment lease, or your next rental property acquisition.
The Logic That Travels
Here's the mechanism. A lender or investor watches Alphabet commit $50 billion to data centres on the promise that AI will reshape search, cloud services, and advertising, all categories where Alphabet already prints cash. The spending gets labelled "strategic." The market applauds. Nobody asks for a three-year breakeven or demands to see margin projections.
Then a dentist in Kelowna walks in asking for $800,000 to add two chairs, hire an associate, and expand into cosmetic work. The business plan projects 18-month payback based on current patient volume and local demographics. The loan officer, who spent the morning reading about Meta's $65 billion AI commitment, now sees the dentist's request through a lens that has been subtly adjusted. If Meta can justify that kind of spend on narrative, why can't this practice expansion work on optimism about patient growth?
The difference is that Meta has $120 billion in annual revenue and generates $40 billion in free cash flow even while lighting money on fire for AI experiments. The dentist has $1.2 million in collections and is asking to lever up on the assumption that demand will follow supply. Those are not the same risk profiles. But the framing has bled across.
What Narrative Spending Actually Requires
Tech companies can afford to spend without immediate returns because they sit on fortresses of existing cash generation. Microsoft's Azure business alone brought in $25 billion in Q1 2024. That buys a lot of patience for unproven AI bets. The board isn't panicking because the core business funds the experiment.
Most business owners and real estate investors are not working from that position. You're borrowing against projected cash flow, not realized cash reserves. Your lender is underwriting based on what you've done and what the market will support, not on what the narrative suggests might happen if everything breaks your way.
When you justify a borrowing decision with "we have to spend to stay competitive," you're importing tech's framing without tech's balance sheet. The question isn't whether the spending might pay off. The question is what happens to your debt service if it doesn't pay off in the timeline you projected.
The Underwriting Gap
Lenders tightened standards after 2023's rate shock, but the appetite for growth stories hasn't disappeared. A well-packaged expansion plan that sounds strategic can still get funded, especially if the borrower has been reliable in the past. The problem is that "strategic" has started to mean "the narrative makes sense" rather than "the cash flow model holds under stress."
A concrete example: a contractor in the Fraser Valley takes on $600,000 in equipment financing to add capacity for a new housing development project. The justification is that the project pipeline looks strong and competitors are scaling. The loan officer approves it because the sector is hot and the narrative fits. But the housing pipeline in late 2024 has started to slow as higher rates bite. The contractor is now carrying debt service on equipment that isn't fully utilized, and the revenue that was supposed to cover it hasn't materialized.
That's the poisoning. The decision was underwritten on optimism shaped by a different sector's tolerance for speculative spending. When rates and demand shifted, the equipment that looked like a sound bet became a drag on cash flow.
How to Inoculate Your Own Decisions
The fix is arithmetic. Before you commit to debt-financed growth, model the downside case with numbers that would make a pessimist nod. What happens if patient volume doesn't grow as fast as projected? What happens if the rental market softens and you carry two months of vacancy per year instead of zero? What happens if the equipment you're financing sits idle 40% of the time instead of 10%?
If the debt service still works in that scenario, borrow. If it doesn't, the narrative isn't good enough to bridge the gap. Tech companies can afford to be wrong because they're spending profits. You're spending borrowed money. The downside isn't a missed quarter. It's a liquidity crisis.
The market rewards tech for betting big on AI because tech can survive being wrong. You probably can't. That difference should govern every borrowing decision you make in 2026.
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure