Why Your 15-Stock Portfolio Might Be One Bad Contract Away From a Loss
Mark sold his consulting practice in 2019 for $3.7 million and spent the next eighteen months building a portfolio of fourteen stocks. He knew concentration risk. He'd lived it. The entire sale price was tied to three recurring contracts, and when the second-largest client left six months before closing, the valuation dropped 28%. He remembered the feeling. So when he opened his self-directed account at TD Direct Investing, he made sure no single position exceeded 8% of the portfolio.
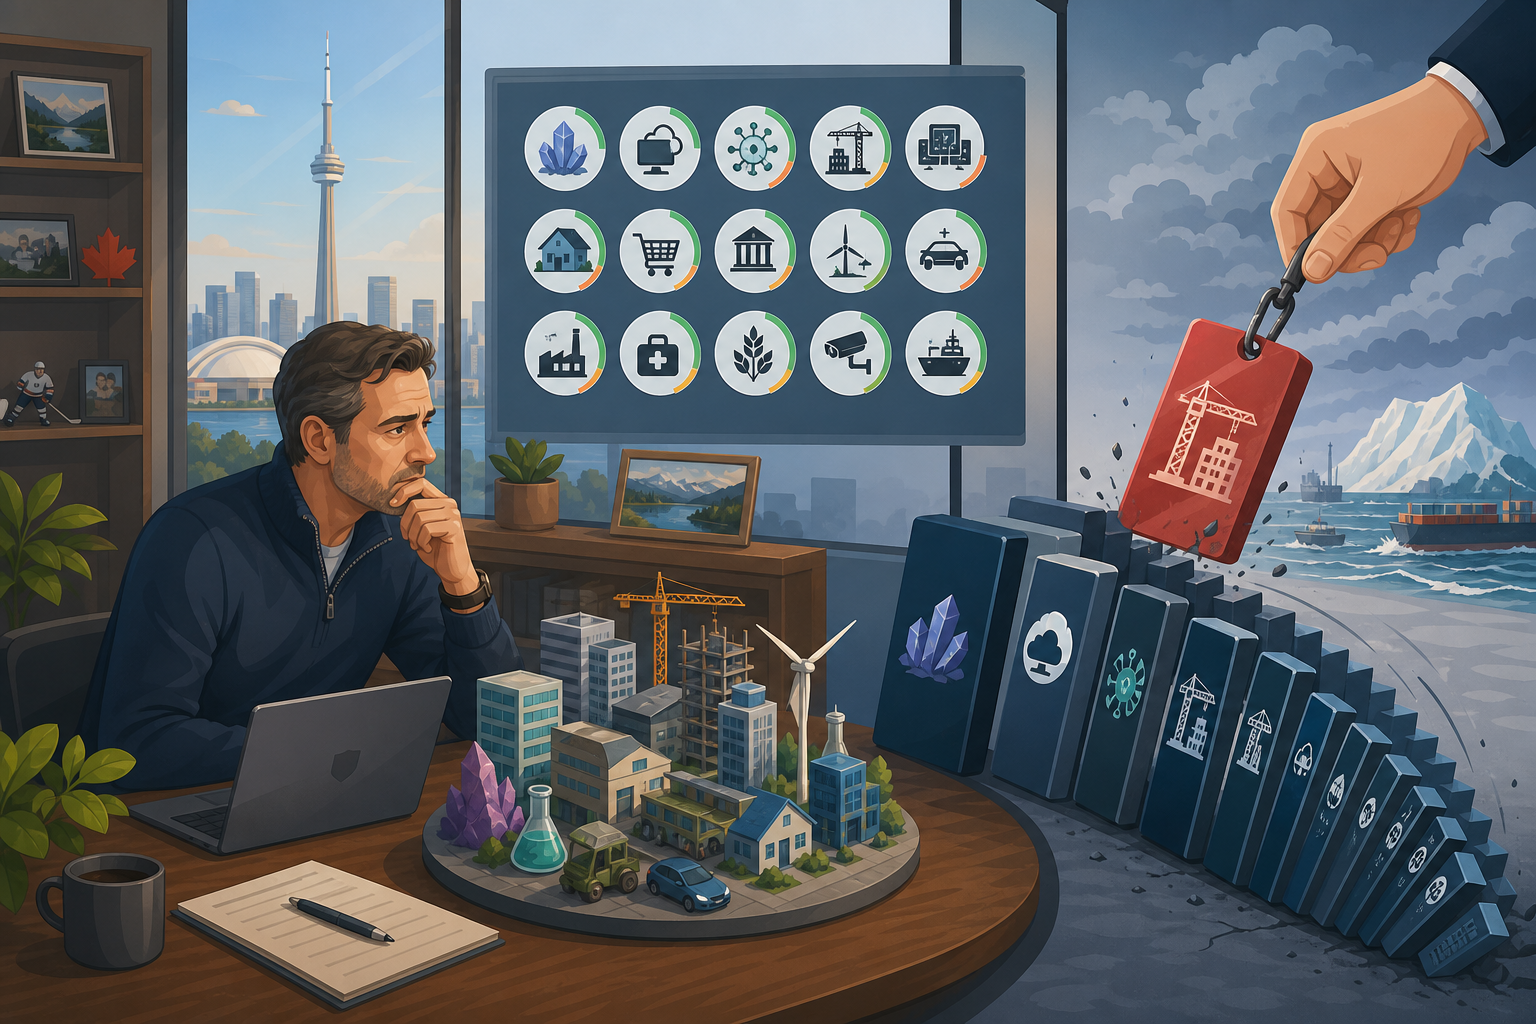
By late 2021, he owned shares in a junior lithium miner, a software firm chasing a federal procurement contract, a biotech waiting on Health Canada approval, and two construction-tech companies bidding on Ontario highway and transit projects. Fifteen names. The lithium play jumped 62% when the company announced a supply agreement with a German battery maker. Mark called it vindication. What he didn't call it, because he didn't see it, was proof that five of his positions moved on the same logic: one contract, one approval, one bid.
Independence of returns beats number of tickers
The degree to which your stocks respond to different forces matters more than the count of stocks you own. A real estate developer holding five REITs and three construction-equipment manufacturers is not diversified; they are leveraged to interest rates and housing starts seven times over. If the Bank of Canada raises rates 50 basis points, all eight positions move in the same direction, at roughly the same magnitude, for the same reason.
The question is not "What does this company do?" The question is "What makes this stock move?" If three different companies in your portfolio all hinge on the same event, a regulatory approval, a commodity price, a government tender, you own one position, not three.
Single-contract stocks are defined by binary outcomes. A pharmaceutical company with one drug in Phase III trials. A junior miner with one deposit under development. A software firm where 70% of projected revenue depends on winning a single RFP. They are high-volatility, high-specificity bets that belong in the smallest allocation category. They should not be spread across 15% of your capital just because you split them into three positions.
The 1% rule for binary bets
In Canadian portfolio construction, positions above 5% are considered core. Positions below 1% are satellite or speculative. Single-contract stocks belong in that second category because their upside is asymmetric but their downside is often total. A stock that triples doesn't need a 10% allocation to move your portfolio. A 1% position that triples adds 2 percentage points to your return without risking the principal balance if the contract falls through.
Mark's lithium position started at 6%. After the supply agreement, it was 9%. When the German partner delayed the first shipment in 2022, citing battery chemistry changes, the stock dropped 47% in eight trading days. Mark sold at a loss because he needed the cash to cover a tax bill on his 2021 capital gains, gains that had come, in part, from that same stock. The position that had been vindication became the reason he couldn't rebalance without triggering a taxable event.
The capital gains inclusion rate for realized gains by individuals in Canada is 50%. For someone managing a $3 million equity portfolio, rebalancing out of a high-volatility winner means paying tax on half of the gain. That creates friction. You hold longer than you should because selling is expensive. The single-contract stock that jumped 60% becomes a position you're stuck with because the cost of getting out is too high.
Concentration worked once
Business owners built wealth through focus. One company. One sector. Often one large contract or client that carried the business for years. That logic does not port to public equities. In your own business, you controlled the variables. You knew the client. You saw the contract terms. You could renegotiate or pivot.
In a public company, you are a passenger. When a junior mining stock drops 50% because a permitting delay pushed production out eighteen months, you don't get a board seat. You get a press release. The difference between owning the business and owning the stock is the difference between driving and being driven. One is concentration as strategy. The other is concentration as oversight.
Mark still owns fourteen stocks. Three of them are single-contract plays. They total 2.4% of his portfolio. The rest is split between broad-index ETFs, dividend payers with ten-year track records, and one position in a Canadian bank. When someone asks him about the lithium stock, he mentions it. But he doesn't call it vindication anymore.


Mark sold his consulting practice in 2019 for $3.7 million and spent the next eighteen months building a portfolio of fourteen stocks. He knew concentration risk. He'd lived it. The entire sale price was tied to three recurring contracts, and when the second-largest client left six months before closing, the valuation dropped 28%. He remembered the feeling. So when he opened his self-directed account at TD Direct Investing, he made sure no single position exceeded 8% of the portfolio.
By late 2021, he owned shares in a junior lithium miner, a software firm chasing a federal procurement contract, a biotech waiting on Health Canada approval, and two construction-tech companies bidding on Ontario highway and transit projects. Fifteen names. The lithium play jumped 62% when the company announced a supply agreement with a German battery maker. Mark called it vindication. What he didn't call it, because he didn't see it, was proof that five of his positions moved on the same logic: one contract, one approval, one bid.
Independence of returns beats number of tickers
The degree to which your stocks respond to different forces matters more than the count of stocks you own. A real estate developer holding five REITs and three construction-equipment manufacturers is not diversified; they are leveraged to interest rates and housing starts seven times over. If the Bank of Canada raises rates 50 basis points, all eight positions move in the same direction, at roughly the same magnitude, for the same reason.
The question is not "What does this company do?" The question is "What makes this stock move?" If three different companies in your portfolio all hinge on the same event, a regulatory approval, a commodity price, a government tender, you own one position, not three.
Single-contract stocks are defined by binary outcomes. A pharmaceutical company with one drug in Phase III trials. A junior miner with one deposit under development. A software firm where 70% of projected revenue depends on winning a single RFP. They are high-volatility, high-specificity bets that belong in the smallest allocation category. They should not be spread across 15% of your capital just because you split them into three positions.
The 1% rule for binary bets
In Canadian portfolio construction, positions above 5% are considered core. Positions below 1% are satellite or speculative. Single-contract stocks belong in that second category because their upside is asymmetric but their downside is often total. A stock that triples doesn't need a 10% allocation to move your portfolio. A 1% position that triples adds 2 percentage points to your return without risking the principal balance if the contract falls through.
Mark's lithium position started at 6%. After the supply agreement, it was 9%. When the German partner delayed the first shipment in 2022, citing battery chemistry changes, the stock dropped 47% in eight trading days. Mark sold at a loss because he needed the cash to cover a tax bill on his 2021 capital gains, gains that had come, in part, from that same stock. The position that had been vindication became the reason he couldn't rebalance without triggering a taxable event.
The capital gains inclusion rate for realized gains by individuals in Canada is 50%. For someone managing a $3 million equity portfolio, rebalancing out of a high-volatility winner means paying tax on half of the gain. That creates friction. You hold longer than you should because selling is expensive. The single-contract stock that jumped 60% becomes a position you're stuck with because the cost of getting out is too high.
Concentration worked once
Business owners built wealth through focus. One company. One sector. Often one large contract or client that carried the business for years. That logic does not port to public equities. In your own business, you controlled the variables. You knew the client. You saw the contract terms. You could renegotiate or pivot.
In a public company, you are a passenger. When a junior mining stock drops 50% because a permitting delay pushed production out eighteen months, you don't get a board seat. You get a press release. The difference between owning the business and owning the stock is the difference between driving and being driven. One is concentration as strategy. The other is concentration as oversight.
Mark still owns fourteen stocks. Three of them are single-contract plays. They total 2.4% of his portfolio. The rest is split between broad-index ETFs, dividend payers with ten-year track records, and one position in a Canadian bank. When someone asks him about the lithium stock, he mentions it. But he doesn't call it vindication anymore.
Sources
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure