Your Bank Doesn't Offer the Smith Maneuver Because It Serves 900,000 Clients, Not 900
The five tellers working the floor at a BMO branch in Oakville collectively handled 1,847 client interactions last week. Most lasted under four minutes. The branch itself serves a catchment area of roughly 18,000 households. One of those households is trying to convert non-deductible mortgage interest into tax-deductible investment loan interest using a readvanceable mortgage. The teller has no training for that conversation, and the branch manager has been told not to have it.
This is not a failure of the bank. It is the bank operating exactly as designed.
The Standardization Constraint
Canadian banks are built for volume. The Big Six collectively manage over 28 million active accounts. Their mortgage desks close thousands of files per quarter using a menu of pre-approved products: fixed-rate terms, variable-rate terms, combinations of the two, occasional cashback offers. The workflow is optimized for speed and regulatory compliance. A mortgage specialist's job is to match a client to a product on the menu and move the file to underwriting.
The Smith Maneuver does not fit on that menu. It requires a readvanceable mortgage, a product the banks do sell, under names like RBC Homeline or TD FlexLine, but the maneuver itself is the coordinated use of that product to systematically replace mortgage debt with investment debt while claiming the interest as a tax deduction under Section 20(1)(c) of the Income Tax Act. Executing it cleanly involves tracking every dollar borrowed from the HELOC portion, ensuring it flows directly into income-producing investments, filing the interest deduction correctly, and rebalancing the portfolio as the mortgage shrinks and the investment loan grows.
That coordination does not happen at the counter. It happens between an accountant who understands the CRA's tracing rules, a mortgage broker who structures the loan properly, and an investment advisor who builds a portfolio aligned with the client's risk tolerance and the tax strategy. Most bank branches do not employ all three, and the ones that do keep them in separate divisions with separate compliance walls.
The Misalignment Problem
There is a deeper issue. The Smith Maneuver aims to eliminate your mortgage faster while building a leveraged investment portfolio. The bank's mortgage division makes money when you carry the mortgage longer. A 25-year amortization at 5.2% generates more interest revenue than a 15-year payoff at the same rate. The strategy is not illegal, not risky in a regulatory sense, and not something the bank forbids, but it runs counter to the product's intended use case from the lender's perspective.
Banks do not market against their own revenue model. They will sell you the readvanceable mortgage because it is a product they offer. They will not train frontline staff to show you how to use it in a way that cuts the amortization by a decade.
When Specialization Beats Scale
The analogy that fits: you would not ask a Toyota dealership to explain how to modify the suspension for track racing. They sold you the car. Someone else tunes it.
A mortgage specialist at a major bank closes 8 to 12 files a month. A Smith Maneuver-accredited advisor closes perhaps 40 files a year, all using the same strategy, all requiring the same documentation rigor, all navigating the same CRA audit exposure. The specialist has seen every edge case. The bank employee has seen none.
The risk homeowners misread is institutional absence as a warning sign. If the bank will not discuss it, it must be dangerous. That logic reverses causation. The bank will not discuss it because the discussion requires expertise the bank does not staff at retail scale, not because the strategy itself fails scrutiny.
Section 20(1)(c) has been law since 1972. The CRA's position on interest deductibility is well-documented. The maneuver works when the paper trail is clean and the borrowed funds go directly into investments. It fails when funds commingle or when the homeowner cannot prove the link between the HELOC draw and the asset purchase. That is an execution problem, not a code problem.
The bank provides the tool. The specialist teaches you how to use it. Confusing the two is why most people never hear about the strategy until someone outside the branch mentions it.

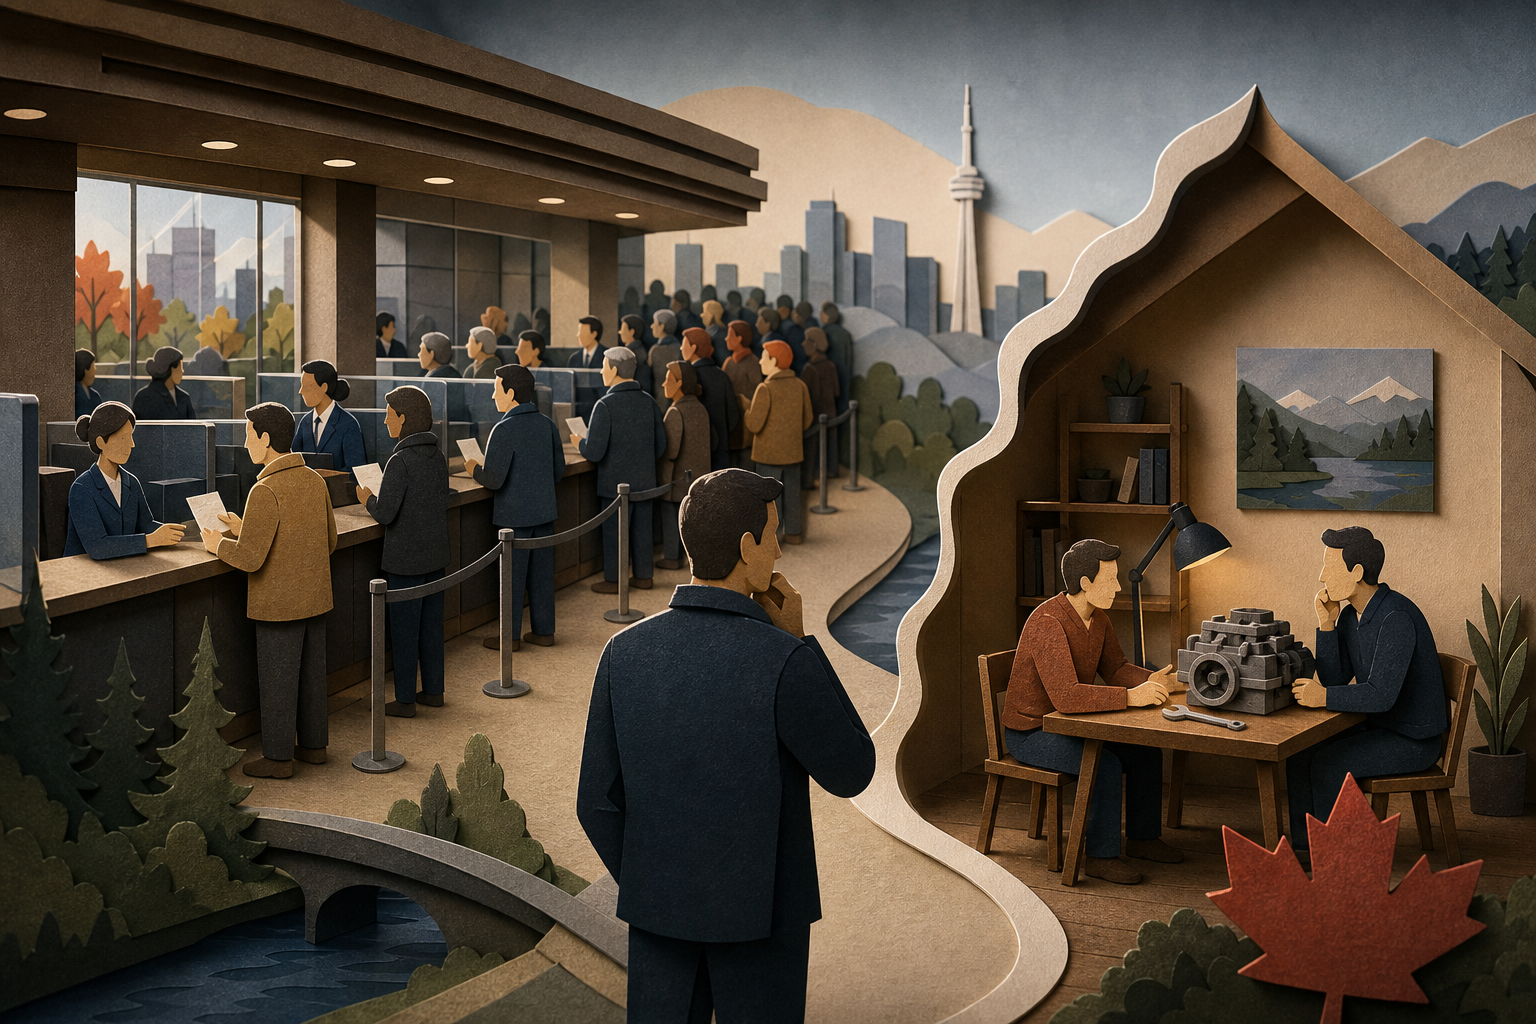

The five tellers working the floor at a BMO branch in Oakville collectively handled 1,847 client interactions last week. Most lasted under four minutes. The branch itself serves a catchment area of roughly 18,000 households. One of those households is trying to convert non-deductible mortgage interest into tax-deductible investment loan interest using a readvanceable mortgage. The teller has no training for that conversation, and the branch manager has been told not to have it.
This is not a failure of the bank. It is the bank operating exactly as designed.
The Standardization Constraint
Canadian banks are built for volume. The Big Six collectively manage over 28 million active accounts. Their mortgage desks close thousands of files per quarter using a menu of pre-approved products: fixed-rate terms, variable-rate terms, combinations of the two, occasional cashback offers. The workflow is optimized for speed and regulatory compliance. A mortgage specialist's job is to match a client to a product on the menu and move the file to underwriting.
The Smith Maneuver does not fit on that menu. It requires a readvanceable mortgage, a product the banks do sell, under names like RBC Homeline or TD FlexLine, but the maneuver itself is the coordinated use of that product to systematically replace mortgage debt with investment debt while claiming the interest as a tax deduction under Section 20(1)(c) of the Income Tax Act. Executing it cleanly involves tracking every dollar borrowed from the HELOC portion, ensuring it flows directly into income-producing investments, filing the interest deduction correctly, and rebalancing the portfolio as the mortgage shrinks and the investment loan grows.
That coordination does not happen at the counter. It happens between an accountant who understands the CRA's tracing rules, a mortgage broker who structures the loan properly, and an investment advisor who builds a portfolio aligned with the client's risk tolerance and the tax strategy. Most bank branches do not employ all three, and the ones that do keep them in separate divisions with separate compliance walls.
The Misalignment Problem
There is a deeper issue. The Smith Maneuver aims to eliminate your mortgage faster while building a leveraged investment portfolio. The bank's mortgage division makes money when you carry the mortgage longer. A 25-year amortization at 5.2% generates more interest revenue than a 15-year payoff at the same rate. The strategy is not illegal, not risky in a regulatory sense, and not something the bank forbids, but it runs counter to the product's intended use case from the lender's perspective.
Banks do not market against their own revenue model. They will sell you the readvanceable mortgage because it is a product they offer. They will not train frontline staff to show you how to use it in a way that cuts the amortization by a decade.
When Specialization Beats Scale
The analogy that fits: you would not ask a Toyota dealership to explain how to modify the suspension for track racing. They sold you the car. Someone else tunes it.
A mortgage specialist at a major bank closes 8 to 12 files a month. A Smith Maneuver-accredited advisor closes perhaps 40 files a year, all using the same strategy, all requiring the same documentation rigor, all navigating the same CRA audit exposure. The specialist has seen every edge case. The bank employee has seen none.
The risk homeowners misread is institutional absence as a warning sign. If the bank will not discuss it, it must be dangerous. That logic reverses causation. The bank will not discuss it because the discussion requires expertise the bank does not staff at retail scale, not because the strategy itself fails scrutiny.
Section 20(1)(c) has been law since 1972. The CRA's position on interest deductibility is well-documented. The maneuver works when the paper trail is clean and the borrowed funds go directly into investments. It fails when funds commingle or when the homeowner cannot prove the link between the HELOC draw and the asset purchase. That is an execution problem, not a code problem.
The bank provides the tool. The specialist teaches you how to use it. Confusing the two is why most people never hear about the strategy until someone outside the branch mentions it.
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure