Your client isn't worried about tariffs, they're worried about control
The S&P/TSX Composite dropped 340 points the day Washington floated a 25% tariff on Canadian steel. Three clients called before noon. None asked about steel exposure. All three wanted to know if they should move everything to cash.
The headlines say "tariff risk." The anxiety underneath is about something else entirely. When a client reads that cross-border policy can rewrite the rules overnight, they are registering that the variables they thought were stable - trade agreements, currency relationships, the regulatory environment their portfolio was built for - can shift without warning. The question they are asking, even when they phrase it as "should I sell," is whether they still understand the system their money lives in.
What the anxiety actually tracks
Trade policy moves through an economy in layers. The first layer is direct: a tariff raises the input cost for a manufacturer, which flows through to the price of the finished good. The second layer is indirect: the manufacturer delays a planned expansion because the cost structure is now uncertain, which means the equipment supplier loses an order, which means the financing that would have supported that order stays on the sideline. The third layer is psychological: an investor watching these ripples concludes that "everything is unpredictable" and moves to cash, which becomes a liquidity event in the market, which confirms the sense of instability for the next investor.
Advisors tend to address the first layer, sector rotation, commodity exposure, geographic diversification. Clients are responding to the third. The volatility they see ripples across all sectors at once. Systemic risk feels personal in a way that sector risk does not.
The portfolio vs. the framework
A diversified portfolio absorbs sector shocks reasonably well. A 60/40 allocation with exposure across financials, resources, technology, and fixed income can handle a 15% drawdown in energy or a currency swing of 200 basis points without requiring a fundamental reassessment. When the client believes that the assumptions the portfolio was built on no longer hold, the portfolio hits its limit. The advisor can rebalance the holdings, but cannot rebuild the framework the client trusted.
This is where the gap opens. The advisor is thinking about trailing earnings and rebalancing. The client is thinking about whether the rules still apply. When the CUSMA review was announced for 2026, the rational investment response was modest: a slight tilt toward Canadian companies that sell domestically, maybe a hedge on the Canadian dollar. The emotional response among high-net-worth clients was far larger. Advisors reported a 40% increase in "should we move offshore" conversations in the six weeks following the announcement, even though the review itself is procedural and the agreement remained in force.
The gap is not irrational. It reflects a correct intuition about the difference between volatility within a known range and volatility that might redraw the range itself. One you hedge. The other you question.
The work is reframing
No advisor can predict the outcome of a trade negotiation. Trying to is a credibility trap. What they can do is help the client separate signal from noise by naming what the noise actually is.
Canada's export dependence, roughly 68% of goods going to the United States, means portfolios here are trade-sensitive by default. This sensitivity was true in 2015, in 2020, and it will be true in 2030. What changes is how visible that sensitivity becomes. A tariff threat makes the dependency explicit, and explicit sensitivity feels different from background risk even though the risk itself has not grown.
The Canadian dollar acts as a natural shock absorber. When trade tensions rise and the dollar weakens, export competitiveness improves and foreign equity holdings gain value in domestic currency terms. The system has internal stabilizers. Clients do not feel stabilized because the headlines do not describe stability. They describe confrontation.
The advisor's role in this environment is to give clients a structure that can hold their anxiety without acting on it. That structure is a plan built to survive multiple outcomes, not a prediction of which one will occur. When the client asks if they should move to cash, the answer is not "tariffs don't matter." The answer is: here are the three scenarios, here is what the portfolio does in each one, and here is why we are not making changes based on headlines.

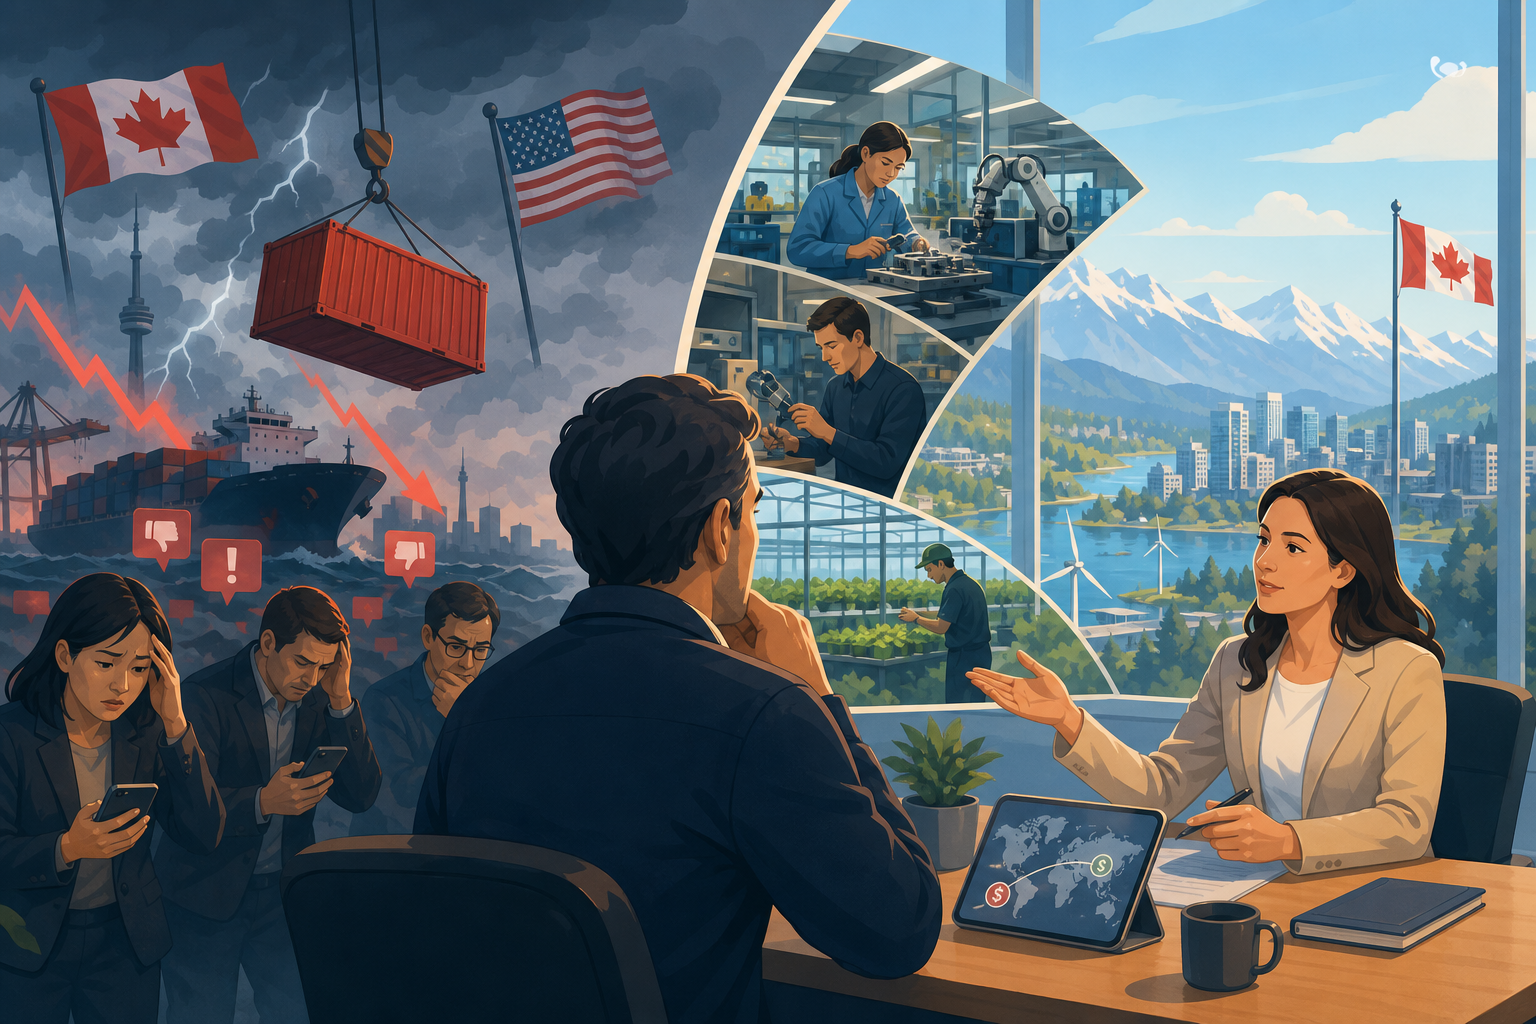

The S&P/TSX Composite dropped 340 points the day Washington floated a 25% tariff on Canadian steel. Three clients called before noon. None asked about steel exposure. All three wanted to know if they should move everything to cash.
The headlines say "tariff risk." The anxiety underneath is about something else entirely. When a client reads that cross-border policy can rewrite the rules overnight, they are registering that the variables they thought were stable - trade agreements, currency relationships, the regulatory environment their portfolio was built for - can shift without warning. The question they are asking, even when they phrase it as "should I sell," is whether they still understand the system their money lives in.
What the anxiety actually tracks
Trade policy moves through an economy in layers. The first layer is direct: a tariff raises the input cost for a manufacturer, which flows through to the price of the finished good. The second layer is indirect: the manufacturer delays a planned expansion because the cost structure is now uncertain, which means the equipment supplier loses an order, which means the financing that would have supported that order stays on the sideline. The third layer is psychological: an investor watching these ripples concludes that "everything is unpredictable" and moves to cash, which becomes a liquidity event in the market, which confirms the sense of instability for the next investor.
Advisors tend to address the first layer, sector rotation, commodity exposure, geographic diversification. Clients are responding to the third. The volatility they see ripples across all sectors at once. Systemic risk feels personal in a way that sector risk does not.
The portfolio vs. the framework
A diversified portfolio absorbs sector shocks reasonably well. A 60/40 allocation with exposure across financials, resources, technology, and fixed income can handle a 15% drawdown in energy or a currency swing of 200 basis points without requiring a fundamental reassessment. When the client believes that the assumptions the portfolio was built on no longer hold, the portfolio hits its limit. The advisor can rebalance the holdings, but cannot rebuild the framework the client trusted.
This is where the gap opens. The advisor is thinking about trailing earnings and rebalancing. The client is thinking about whether the rules still apply. When the CUSMA review was announced for 2026, the rational investment response was modest: a slight tilt toward Canadian companies that sell domestically, maybe a hedge on the Canadian dollar. The emotional response among high-net-worth clients was far larger. Advisors reported a 40% increase in "should we move offshore" conversations in the six weeks following the announcement, even though the review itself is procedural and the agreement remained in force.
The gap is not irrational. It reflects a correct intuition about the difference between volatility within a known range and volatility that might redraw the range itself. One you hedge. The other you question.
The work is reframing
No advisor can predict the outcome of a trade negotiation. Trying to is a credibility trap. What they can do is help the client separate signal from noise by naming what the noise actually is.
Canada's export dependence, roughly 68% of goods going to the United States, means portfolios here are trade-sensitive by default. This sensitivity was true in 2015, in 2020, and it will be true in 2030. What changes is how visible that sensitivity becomes. A tariff threat makes the dependency explicit, and explicit sensitivity feels different from background risk even though the risk itself has not grown.
The Canadian dollar acts as a natural shock absorber. When trade tensions rise and the dollar weakens, export competitiveness improves and foreign equity holdings gain value in domestic currency terms. The system has internal stabilizers. Clients do not feel stabilized because the headlines do not describe stability. They describe confrontation.
The advisor's role in this environment is to give clients a structure that can hold their anxiety without acting on it. That structure is a plan built to survive multiple outcomes, not a prediction of which one will occur. When the client asks if they should move to cash, the answer is not "tariffs don't matter." The answer is: here are the three scenarios, here is what the portfolio does in each one, and here is why we are not making changes based on headlines.
Sources
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure