Your mortgage payoff timeline assumes you'll save more money, but saving harder won't beat structural efficiency
A 35-year-old couple in Langford earning $140,000 with a $650,000 mortgage at 5.2% will pay that loan off in 25 years if they follow the schedule. If they save an extra $500 a month and prepay, they'll knock off maybe three years. If they route their existing paycheque through an all-in-one account instead, they'll be mortgage-free in under 15, without saving a dollar more than they already do.
The difference isn't discipline. It's plumbing.
The problem is where your money sits, not how much you earn
Traditional mortgage math assumes your income lands in a chequing account earning 0%, sits there for two weeks, then gets spent. Meanwhile, your mortgage accrues interest daily at 5.2% on the full principal. That gap, the spread between what your idle cash earns and what your debt costs, is costing you roughly $175 a month on a $650,000 balance. Over 25 years, that's not rounding error. It's $52,000 in avoidable interest.
An all-in-one account collapses that spread. Income deposits reduce the principal immediately for interest calculation purposes. Your mortgage balance still exists, but interest accrues on the net amount: principal minus whatever cash is sitting in the account. When you spend money, the balance rises again. The result is that every dollar works against your debt for the few days or weeks before you need it, rather than sitting neutral in a separate account.
Manulife and National Bank have offered versions of this structure for years. In Canada, these accounts are typically structured as a first-charge HELOC up to 65% loan-to-value, with an amortizing portion above that. The interest rate is Prime plus 0.5% to 1.0%, variable. That's higher than a 5-year fixed, but the offset mechanic more than compensates if you're carrying surplus cash flow month to month.
Why this isn't about finding extra money
Most acceleration advice is income advice in disguise. Get a side hustle. Rent the basement. Cut the subscriptions. All of that works, but it's orthogonal to the structural question: what happens to the money you already have between the day you earn it and the day you spend it?
If your household income is $11,700 a month and your expenses are $10,500, you have $1,200 in monthly float. In a traditional setup, that $1,200 earns nothing until you make a lump-sum prepayment once or twice a year. In an all-in-one account, it's working against a 5.2% liability every single day. Compounded daily over 25 years, the difference is enormous.
According to internal data from Manulife, clients with 10% monthly cash flow surplus consistently cut 8 to 12 years off a standard 25-year amortization. That's not from paying more. That's from eliminating the dead time between earning and spending.
The trade you're actually making
This setup is not free. You're giving up rate certainty, these accounts are variable, so if Prime climbs from 5.95% to 7.5%, your cost rises with it. You're also giving up separation. In a traditional mortgage, your equity is locked until you sell or refinance. In an all-in-one account, that equity is liquid and accessible 24/7. If you're the kind of person who treats available credit as permission to spend, this structure will hurt you.
But if you have positive monthly cash flow, stable income, and reasonable spending discipline, the math is hard to argue with. You're not optimizing behavior. You're eliminating a structural inefficiency that costs five figures a year and compounds against you for decades.
The mortgage payoff timeline you've been handed assumes your money will sit idle until you spend it. That assumption is expensive.

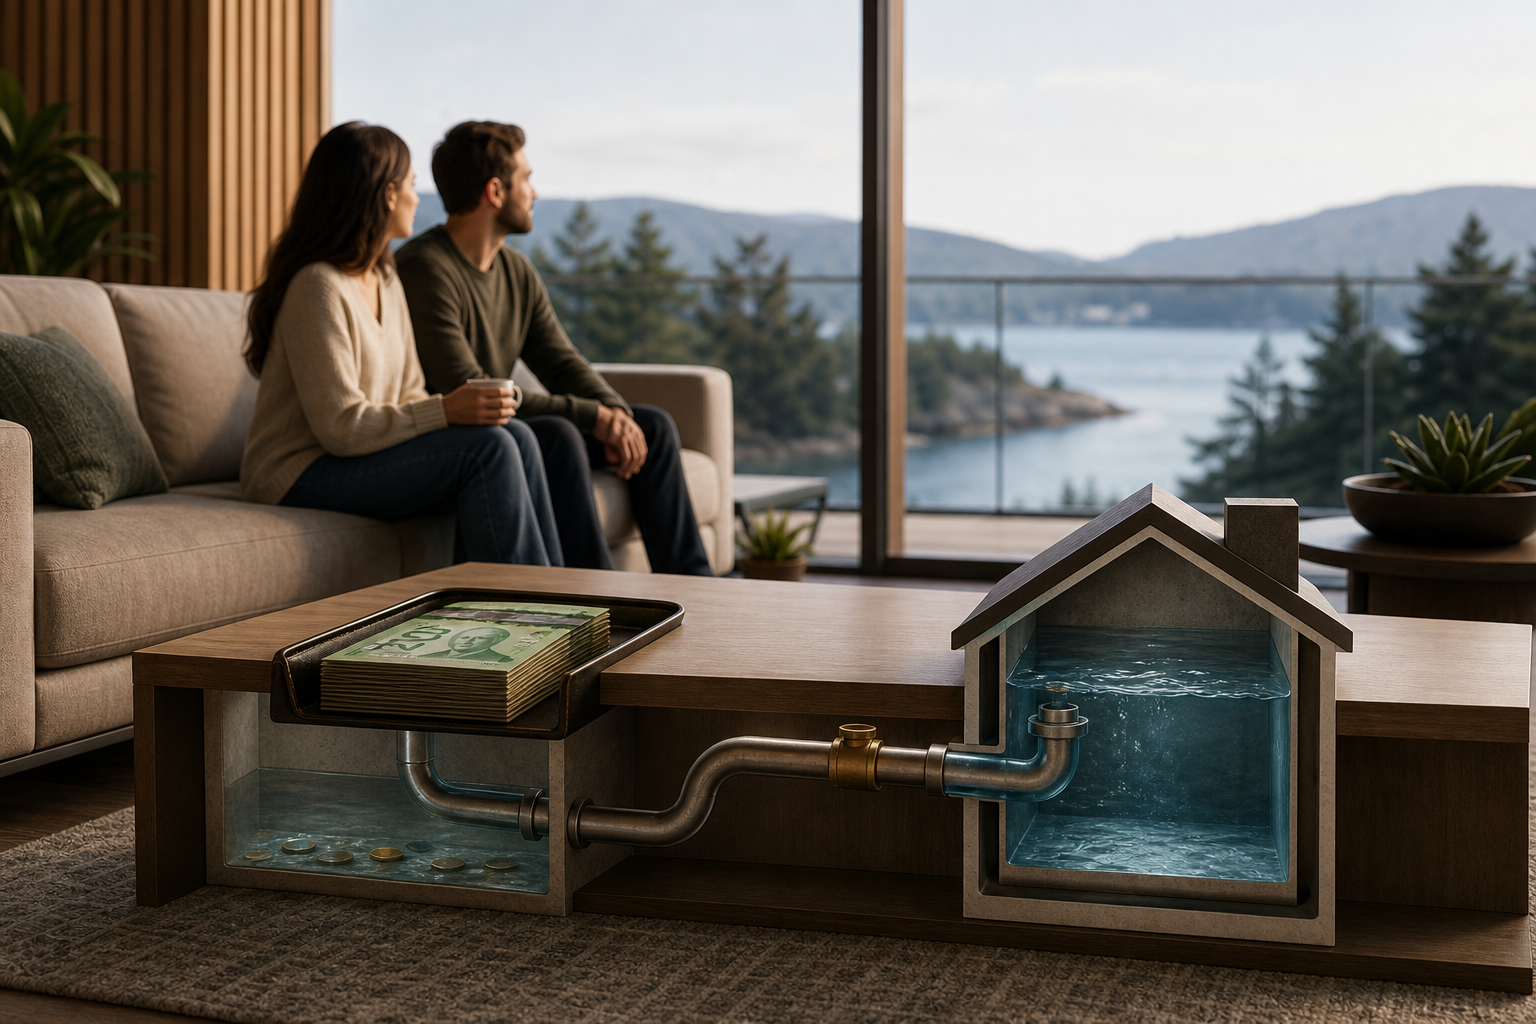

A 35-year-old couple in Langford earning $140,000 with a $650,000 mortgage at 5.2% will pay that loan off in 25 years if they follow the schedule. If they save an extra $500 a month and prepay, they'll knock off maybe three years. If they route their existing paycheque through an all-in-one account instead, they'll be mortgage-free in under 15, without saving a dollar more than they already do.
The difference isn't discipline. It's plumbing.
The problem is where your money sits, not how much you earn
Traditional mortgage math assumes your income lands in a chequing account earning 0%, sits there for two weeks, then gets spent. Meanwhile, your mortgage accrues interest daily at 5.2% on the full principal. That gap, the spread between what your idle cash earns and what your debt costs, is costing you roughly $175 a month on a $650,000 balance. Over 25 years, that's not rounding error. It's $52,000 in avoidable interest.
An all-in-one account collapses that spread. Income deposits reduce the principal immediately for interest calculation purposes. Your mortgage balance still exists, but interest accrues on the net amount: principal minus whatever cash is sitting in the account. When you spend money, the balance rises again. The result is that every dollar works against your debt for the few days or weeks before you need it, rather than sitting neutral in a separate account.
Manulife and National Bank have offered versions of this structure for years. In Canada, these accounts are typically structured as a first-charge HELOC up to 65% loan-to-value, with an amortizing portion above that. The interest rate is Prime plus 0.5% to 1.0%, variable. That's higher than a 5-year fixed, but the offset mechanic more than compensates if you're carrying surplus cash flow month to month.
Why this isn't about finding extra money
Most acceleration advice is income advice in disguise. Get a side hustle. Rent the basement. Cut the subscriptions. All of that works, but it's orthogonal to the structural question: what happens to the money you already have between the day you earn it and the day you spend it?
If your household income is $11,700 a month and your expenses are $10,500, you have $1,200 in monthly float. In a traditional setup, that $1,200 earns nothing until you make a lump-sum prepayment once or twice a year. In an all-in-one account, it's working against a 5.2% liability every single day. Compounded daily over 25 years, the difference is enormous.
According to internal data from Manulife, clients with 10% monthly cash flow surplus consistently cut 8 to 12 years off a standard 25-year amortization. That's not from paying more. That's from eliminating the dead time between earning and spending.
The trade you're actually making
This setup is not free. You're giving up rate certainty, these accounts are variable, so if Prime climbs from 5.95% to 7.5%, your cost rises with it. You're also giving up separation. In a traditional mortgage, your equity is locked until you sell or refinance. In an all-in-one account, that equity is liquid and accessible 24/7. If you're the kind of person who treats available credit as permission to spend, this structure will hurt you.
But if you have positive monthly cash flow, stable income, and reasonable spending discipline, the math is hard to argue with. You're not optimizing behavior. You're eliminating a structural inefficiency that costs five figures a year and compounds against you for decades.
The mortgage payoff timeline you've been handed assumes your money will sit idle until you spend it. That assumption is expensive.
Read Next
Asset managers cut product portfolios to fund AI and outsourcing overhauls
ETFs now hold 42% of Canadian fund assets as OSC tightens crypto and liquidity rules
One in Five Canadian Parents Still Pays Bills for Kids in Their Late Thirties
Joint mortgages surge in Ontario and B.C. as first-time buyers face rising delinquency pressure