Your paycheque cuts mortgage interest the day it arrives, then you spend it
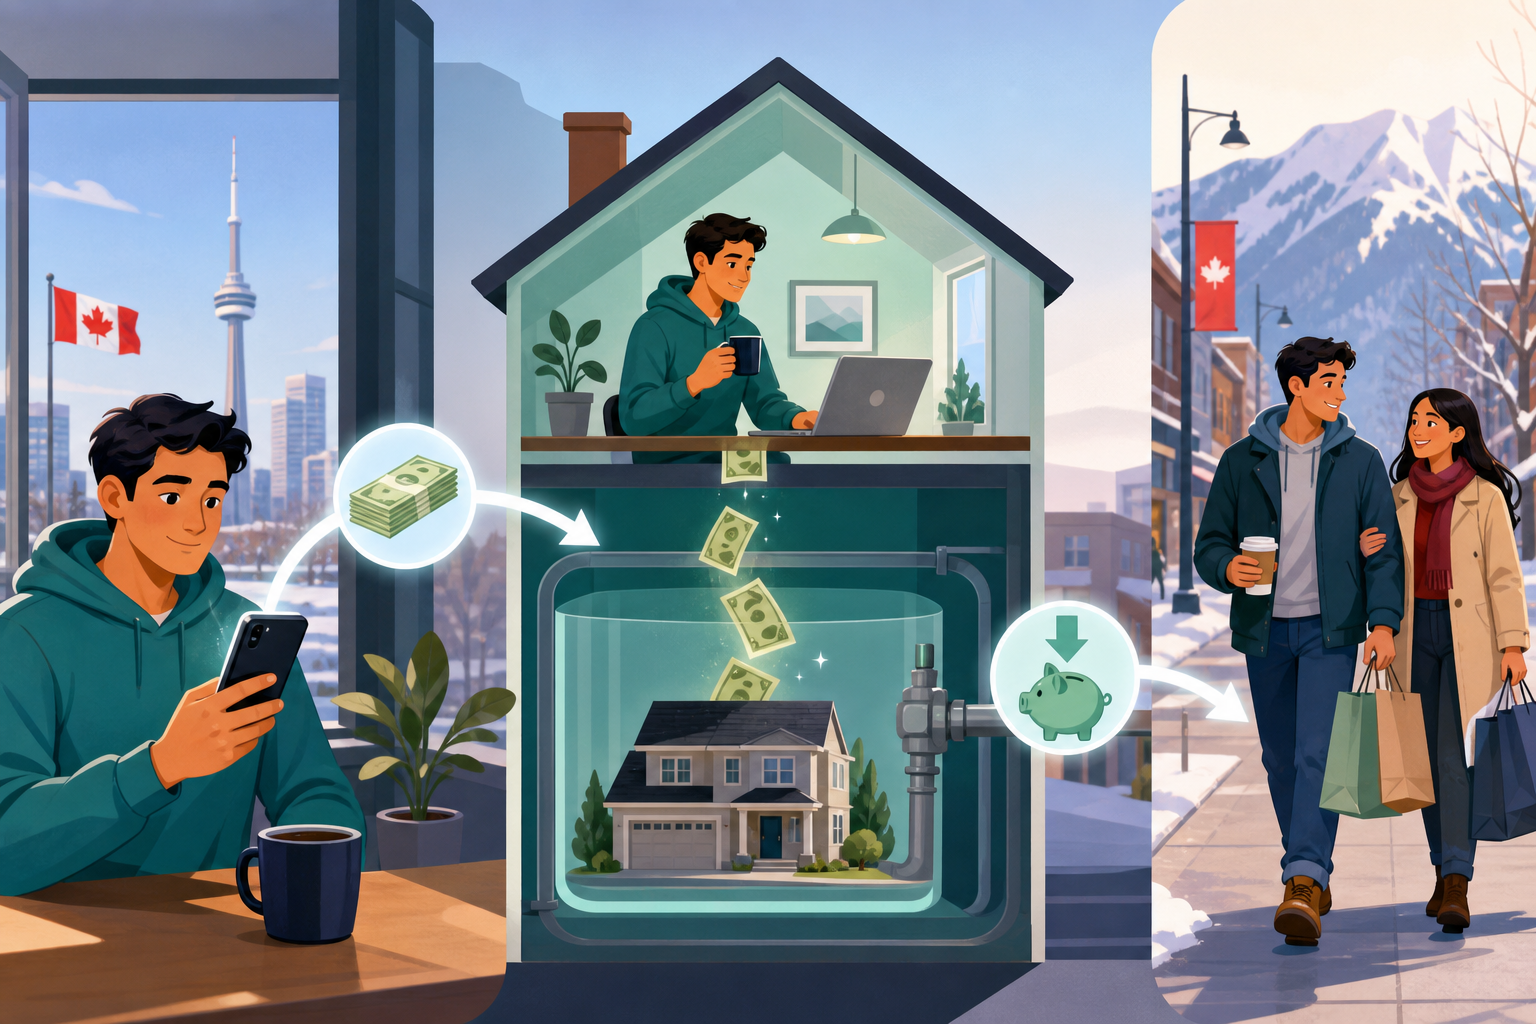
A paycheque deposited on January 2 into a traditional mortgage setup will sit in a chequing account for two weeks before you write the mortgage payment. During those 14 days, it earns roughly 0.05% in a savings account while the mortgage charges 5.2% on the full balance. The interest rate gap between where the money sits and where the debt lives is costing you money every day.
All-in-one mortgage accounts collapse that gap to zero. These products, structured as a first-position home equity line of credit, calculate interest on the daily closing balance, not monthly or semi-annually. When a paycheque arrives, it reduces the principal that same day. Interest for that day is charged on the reduced amount. The money hasn't been spent. It hasn't been locked into a prepayment. It's still yours to withdraw, transfer, or spend tomorrow. But for today, it saved you interest.
Why the daily calculation matters
Traditional Canadian mortgages compound interest semi-annually. Payments are applied monthly. The system batches everything, which is efficient for the lender but inefficient for the borrower who has cash in hand weeks before the payment date. Under that structure, depositing your paycheque early changes nothing about the interest charged.
Daily compounding changes the relationship between income timing and debt cost. A $5,000 paycheque deposited against a $400,000 balance at Prime + 0.5% (currently around 4.95%) saves roughly $0.68 in interest that day. Over 14 days before the funds are spent, that single deposit saves $9.49. Multiply that across 26 pay periods and the annual savings from income simply landing in the right account first exceeds $240, not from changing spending behaviour, just from changing where the money sits between deposit and use.
The savings scale with balance and income. A household with two earners depositing $8,000 per month combined into a $600,000 all-in-one account will see measurably lower interest costs than an identical household routing paycheques through a separate chequing account, even if both spend the same amount by month-end.
The liquidity trap most people miss
The standard objection is that this locks up emergency savings. It doesn't. The revolving portion of an all-in-one account, capped at 65% loan-to-value under OSFI's B-20 guidelines, remains accessible by debit card, e-transfer, or cheque. A dollar applied to the balance today can be withdrawn tomorrow with no penalty, no approval process, no waiting period.
Contrast that with traditional advice: keep three months of expenses in a high-interest savings account earning 2.5% while paying 5.7% on the mortgage. The spread is 3.2 percentage points. On $20,000 in savings, that gap costs $640 per year. In an all-in-one account, those savings sit against the mortgage, earning an effective return equal to the mortgage rate, while remaining fully liquid.
Where the strategy fails
This only works if spending stays below income. The danger is not the account structure, it's the lack of forced principal repayment. Traditional mortgages impose amortization schedules. Miss a payment and you default. All-in-one accounts typically require only interest payments on the revolving portion. A borrower who spends every dollar earned will never reduce the principal, and the account becomes permanent debt at a variable rate.
The second risk is rate volatility. These accounts are tied to Prime. A 1% increase in the Bank of Canada's overnight rate immediately raises the daily interest cost. Borrowers who stretched to qualify at 4.95% may find themselves underwater at 5.95%, with no fixed-rate protection.
The fee structure also matters. Most all-in-one products charge $14 to $25 monthly in administration fees. The interest savings must exceed that cost, which means the strategy works best for borrowers with meaningful balances and consistent income, not those with small mortgages or irregular cash flow.
The account does not make you wealthier. It makes existing cash flow more efficient by closing the gap between when you earn and when you spend. That efficiency, compounded daily over years, shaves time off the amortization. But only if the income keeps arriving and the spending stays disciplined.


A paycheque deposited on January 2 into a traditional mortgage setup will sit in a chequing account for two weeks before you write the mortgage payment. During those 14 days, it earns roughly 0.05% in a savings account while the mortgage charges 5.2% on the full balance. The interest rate gap between where the money sits and where the debt lives is costing you money every day.
All-in-one mortgage accounts collapse that gap to zero. These products, structured as a first-position home equity line of credit, calculate interest on the daily closing balance, not monthly or semi-annually. When a paycheque arrives, it reduces the principal that same day. Interest for that day is charged on the reduced amount. The money hasn't been spent. It hasn't been locked into a prepayment. It's still yours to withdraw, transfer, or spend tomorrow. But for today, it saved you interest.
Why the daily calculation matters
Traditional Canadian mortgages compound interest semi-annually. Payments are applied monthly. The system batches everything, which is efficient for the lender but inefficient for the borrower who has cash in hand weeks before the payment date. Under that structure, depositing your paycheque early changes nothing about the interest charged.
Daily compounding changes the relationship between income timing and debt cost. A $5,000 paycheque deposited against a $400,000 balance at Prime + 0.5% (currently around 4.95%) saves roughly $0.68 in interest that day. Over 14 days before the funds are spent, that single deposit saves $9.49. Multiply that across 26 pay periods and the annual savings from income simply landing in the right account first exceeds $240, not from changing spending behaviour, just from changing where the money sits between deposit and use.
The savings scale with balance and income. A household with two earners depositing $8,000 per month combined into a $600,000 all-in-one account will see measurably lower interest costs than an identical household routing paycheques through a separate chequing account, even if both spend the same amount by month-end.
The liquidity trap most people miss
The standard objection is that this locks up emergency savings. It doesn't. The revolving portion of an all-in-one account, capped at 65% loan-to-value under OSFI's B-20 guidelines, remains accessible by debit card, e-transfer, or cheque. A dollar applied to the balance today can be withdrawn tomorrow with no penalty, no approval process, no waiting period.
Contrast that with traditional advice: keep three months of expenses in a high-interest savings account earning 2.5% while paying 5.7% on the mortgage. The spread is 3.2 percentage points. On $20,000 in savings, that gap costs $640 per year. In an all-in-one account, those savings sit against the mortgage, earning an effective return equal to the mortgage rate, while remaining fully liquid.
Where the strategy fails
This only works if spending stays below income. The danger is not the account structure, it's the lack of forced principal repayment. Traditional mortgages impose amortization schedules. Miss a payment and you default. All-in-one accounts typically require only interest payments on the revolving portion. A borrower who spends every dollar earned will never reduce the principal, and the account becomes permanent debt at a variable rate.
The second risk is rate volatility. These accounts are tied to Prime. A 1% increase in the Bank of Canada's overnight rate immediately raises the daily interest cost. Borrowers who stretched to qualify at 4.95% may find themselves underwater at 5.95%, with no fixed-rate protection.
The fee structure also matters. Most all-in-one products charge $14 to $25 monthly in administration fees. The interest savings must exceed that cost, which means the strategy works best for borrowers with meaningful balances and consistent income, not those with small mortgages or irregular cash flow.
The account does not make you wealthier. It makes existing cash flow more efficient by closing the gap between when you earn and when you spend. That efficiency, compounded daily over years, shaves time off the amortization. But only if the income keeps arriving and the spending stays disciplined.
Read Next
The Expensive Relief of Locking in at the Top
A 4% Mortgage Qualifies at 6%: Reading the Stress Test Correctly in 2026
Economists Forecast Interest Rates as a Herd, and Borrowers Pay for the Misses
Rents Move Last: Read Employer Investment to Spot Demand 18 to 24 Months Early